


EN
Graham (GHM) Reports Stronger Earnings, Is The Stock Still Undervalued?
Why Graham’s latest earnings matter for shareholders
Graham (GHM) has just put fresh numbers on the table, reporting second quarter and first half results to 30 September 2026 along with a reaffirmed net sales outlook for fiscal 2027.
The update gives you two key reference points: recent trading performance through revenue and earnings figures, and management’s confidence level through the reaffirmed full year sales guidance range of US$285 million to US$295 million.
Graham’s latest earnings update landed alongside a sharp swing in sentiment, with the share price jumping 13.61% on the day to US$88.64 and rising 25.34% over the past week, yet still coming off a 90 day share price return that declined 18.50%. It is also sitting against a five year total shareholder return of more than 7x, which indicates strong long term wealth creation, even as shorter term momentum has been rebuilding only recently.
Spot 33 high quality undervalued stocks that, like Graham after this earnings update, combine growing sales, rising profitability, and management confidence in their forward guidance.After a week where Graham’s share price ripped higher while analyst targets and intrinsic value estimates still point to a wide gap, the real puzzle is where fair value now anchors between those two reference points.
Most Popular Narrative: 31% Undervalued
Graham closed at $88.64 while the analyst consensus Narrative on Simply Wall St anchors fair value at $128.60. This implies a sizeable valuation gap that the Narrative links to specific contracts, backlogs, and margin targets rather than just share price momentum.
Record backlog of about $557 million with roughly 35% to 40% expected to convert within 12 months, together with about 85% of that backlog tied to defense, points to multi year revenue visibility that some investors may not be fully reflecting in Graham’s current valuation, with potential future support for earnings stability.
See why 21 investors see Graham as 31% undervalued.
Result: Fair Value of $128.60 (UNDERVALUED)
Still, that bullish Graham narrative can unravel quickly if the record backlog fails to convert as expected or if the targeted margin lift simply does not show up.
Find out about the key risks to this Graham narrative.
Another view on Graham’s valuation
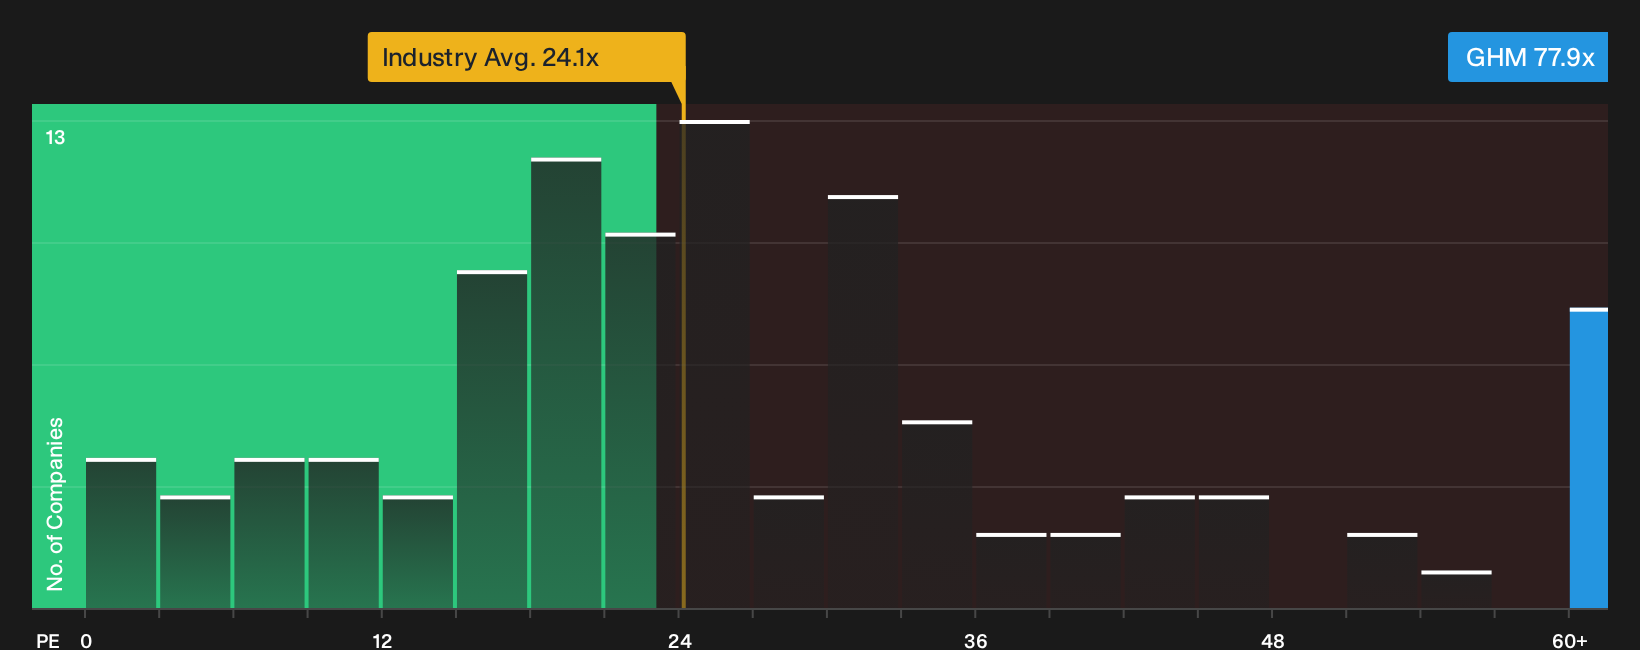
The market is currently paying a P/E of 77.9x for Graham, while the US Machinery industry sits at 23.2x and peer companies average 32.8x. The fair ratio for Graham is 32.3x. That gap points to rich expectations. The key question is whether earnings can keep justifying this premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Graham story feels optimistic on balance, do not just take it at face value. Pressure test the data and form your own view. Then check how that lines up with the 2 key rewards.
Looking for more investment ideas beyond Graham?
If Graham has sharpened your focus on quality opportunities, broaden your watchlist now. Fresh ideas today can make a real difference to tomorrow’s portfolio.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks while still delivering fundamental strength.
- Hunt for potential mispriced opportunities by running through a 33 high quality undervalued stocks that pairs quality fundamentals with attractive valuations.
- Build a portfolio with steady income potential by shortlisting 6 dividend fortresses that combine higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com