


EN
Capstone Copper (TSX:CS) Could Be 35% Below Fair Value On Weaker Guidance
Capstone Copper (TSX:CS) has become a focus after third quarter results showed lower copper volumes and a sharp drop in quarterly net income, even as sales rose. Updated guidance points to production at the low end of its 2026 range.
The recent guidance update and weaker third quarter profitability come after a choppy stretch for Capstone Copper’s shares, with a 90 day share price return down 25.29% and a 1 month share price return down 14.35%, even though the 3 year total shareholder return is up 160.58%. This indicates that long term holders have still seen gains despite fading near term momentum around the CA$11.70 level.
Scan how other copper producers are priced against their output and balance sheet strength by reviewing the hand picked 16 top copper producer stocks alongside Capstone Copper’s latest guidance reset.
The share price reset and guidance at the low end of 2026 expectations have put Capstone Copper at a crossroads. Do current levels still compensate you for operational risk in the numbers that follow?
Most Popular Narrative: 35% Undervalued
Against a last close of CA$11.70, the analyst consensus Narrative on Simply Wall St points to a fair value of CA$18.01 for Capstone Copper. This implies a material valuation gap that rests heavily on Chilean growth projects and balance sheet flexibility.
The current valuation suggests investors are paying for Capstone Copper to complete its major growth projects, incorporate the Cozamin sale proceeds, and maintain record-level EBITDA, while accepting execution, cost, and regulatory risks across its concentrated asset base.
See why 36 investors see Capstone Copper as 35% undervalued.
Result: Fair Value of CA$18.01 (UNDERVALUED)
Still, the Capstone Copper story can break if big projects overrun on cost or timing, or if drought constraints at Pinto Valley return and squeeze cash generation.
Find out about the key risks to this Capstone Copper narrative.
Another View: DCF Points The Other Way
The analyst narrative presents Capstone Copper as about 35% undervalued at a fair value of CA$18.01. Our DCF model suggests a different perspective. Based on projected cash flows it indicates a value closer to CA$8.18, which would make the current CA$11.70 quote appear expensive. Which lens should you rely on when the signals diverge?
Look into how the SWS DCF model arrives at its fair value.
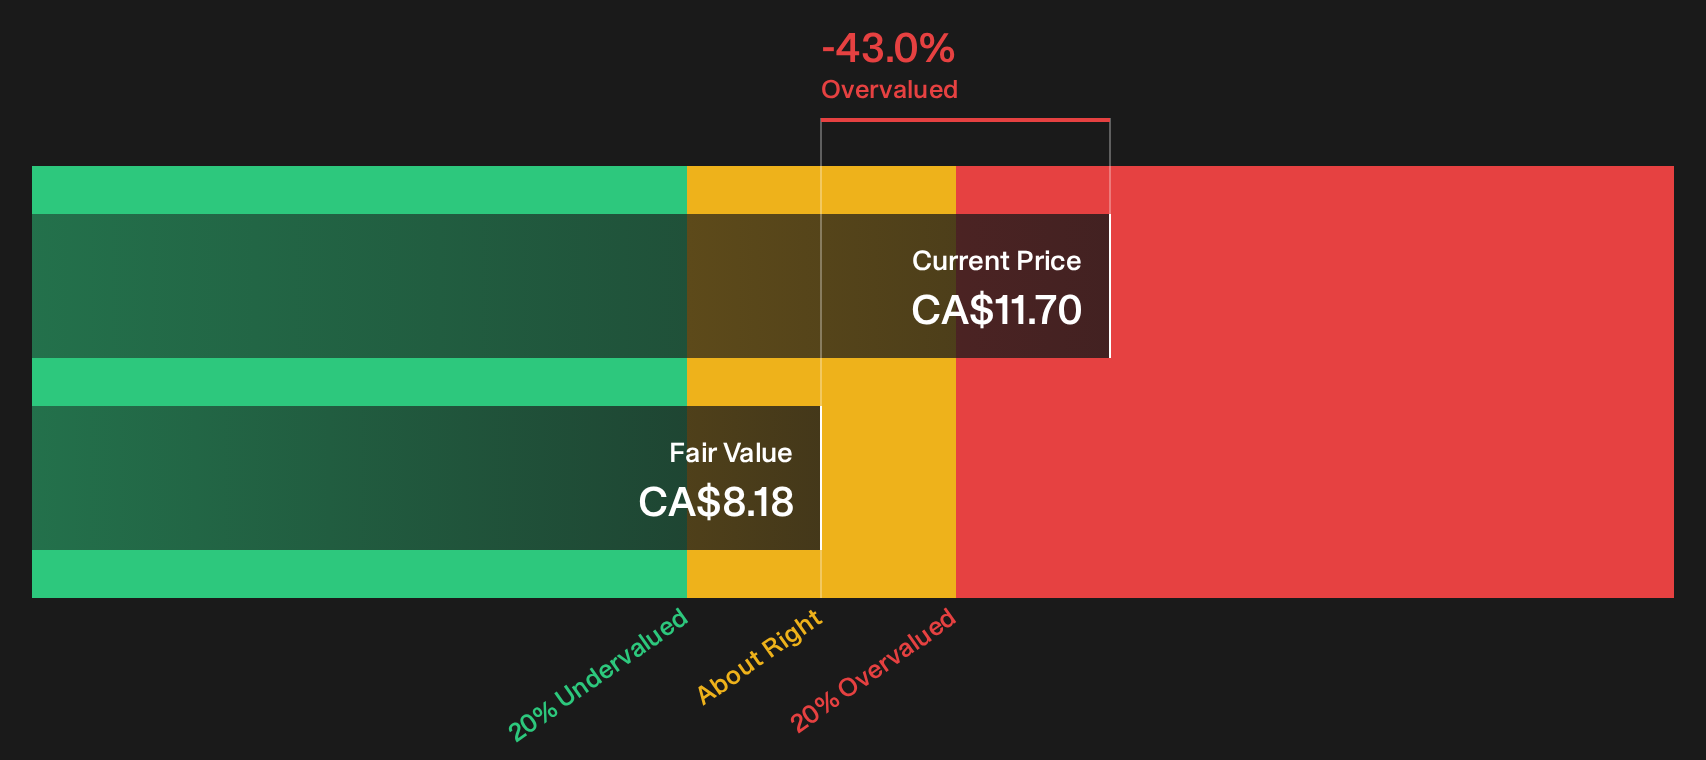
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Capstone Copper for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Capstone Copper so far. If the story feels unfinished, consider moving quickly, pressure testing the assumptions, and weighing the upside by reviewing the 3 key rewards.
Looking for more investment ideas beyond Capstone Copper?
If Capstone Copper has you rethinking your watchlist, use this as a push to scan other opportunities that might better fit your risk and return preferences.
- Target resilient balance sheets and cleaner fundamentals by reviewing the list of solid balance sheet and fundamentals (5 results) before the next bout of volatility catches you off guard.
- Chase quality at a reasonable price by working through the 6 high quality undervalued stocks so you are not relying on a single copper focused thesis.
- Stack potential income streams on top of any Capstone Copper position by checking the 3 dividend fortresses while yields and prices are still where they are today.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com