


EN
Canadian Stock Market Today: TSX Futures Edge Higher As Traders Await US CPI
The Morning Bull - Canadian Market Morning Update Tuesday, 10 Nov 2026
Canadian stocks are set for a mildly positive open, with sentiment tied tightly to a single issue today. US inflation data later in the session is setting the tone for risk appetite and rate expectations across North America.
The US releases October CPI at 1:30 p.m. UTC, with headline inflation expected at 0.3% month on month and core inflation at 0.2%. Those figures feed directly into whether investors see a live risk of a December Federal Reserve rate hike.
If inflation arrives softer than the previous 0.6% monthly reading, investors typically price less pressure for higher borrowing costs. That can support Canadian equity valuations, ease funding costs and improve the outlook for rate sensitive areas that rely heavily on debt markets.
The puzzle for markets is simple. A softer CPI print could support Canadian risk assets. In contrast, a firmer reading would revive rate hike expectations and challenge this early bounce. The entire session effectively hinges on which scenario plays out.
Stocks to Watch Before the Opening Bell
Curaleaf Holdings (CURA)
Curaleaf Holdings has cleared all competition approvals for its proposed acquisition of Aurora Cannabis. Regulators in Germany and Canada signed off, and the enhanced premium offer for all Aurora common shares now runs to 4 December 2026, subject to conditions. Attention turns to whether Aurora investors tender into the bid and how Curaleaf plans to integrate the target.
GFL Environmental (GFL)
GFL Environmental finished a review of unsolicited take private proposals, and the board chose to keep the business public. A special committee concluded the bids did not align with its plans, pointing to long term growth ambitions, financial flexibility and capital allocation priorities. Readers can watch for how management backs up that stance with execution and any future updates on its plan.
Crombie Real Estate Investment Trust (CRR.UN)
Crombie REIT launched a CA$200 million equity financing, combining a CA$117 million bought deal and a CA$83 million private placement with Empire Company, which keeps about 41.5% economic and voting interest. At the same time, Crombie is buying majority stakes in 28 grocery anchored properties for CA$216.2 million, adding roughly 1.2 million square feet of retail space.
Top Movers
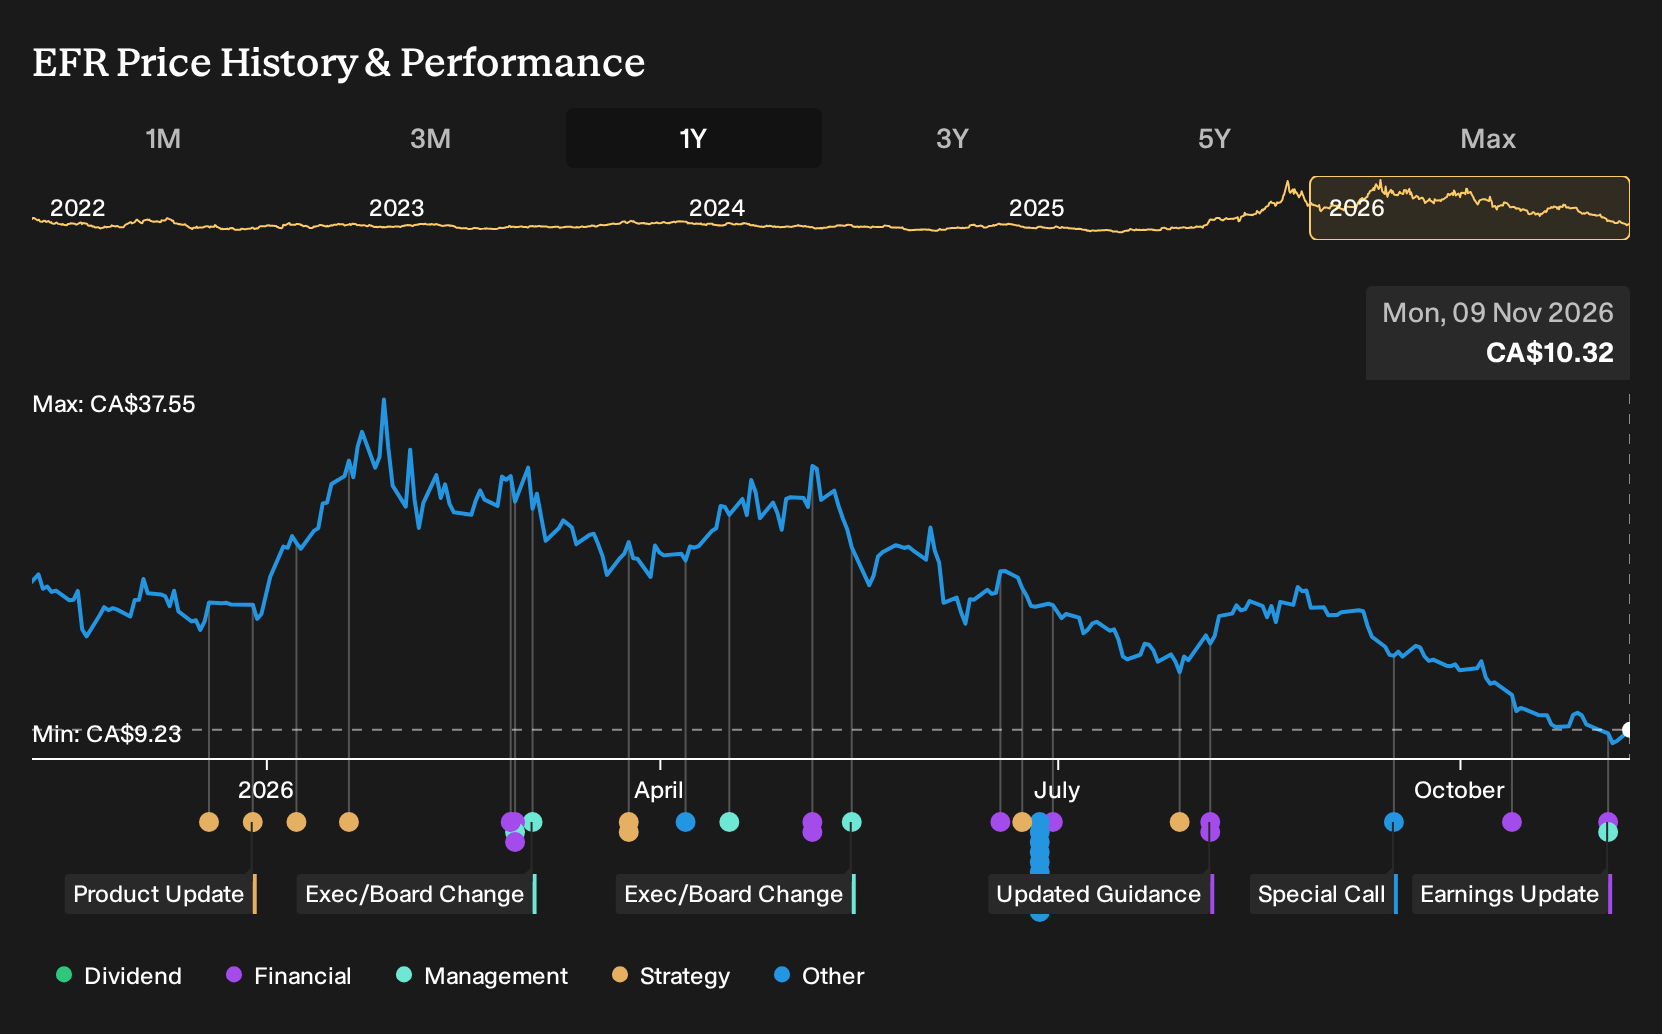
- Energy Fuels (TSX:EFR) surged 9.79% as investors reacted to higher uranium sales and progress in its rare earth business.
- Silvercorp Metals (TSX:SVM) jumped 9.14% after quarterly results showed a swing to profit and stronger first half earnings.
- Ero Copper (TSX:ERO) advanced 8.42% following recent analyst commentary and continued focus on copper exposure into 2027.
Top Losers
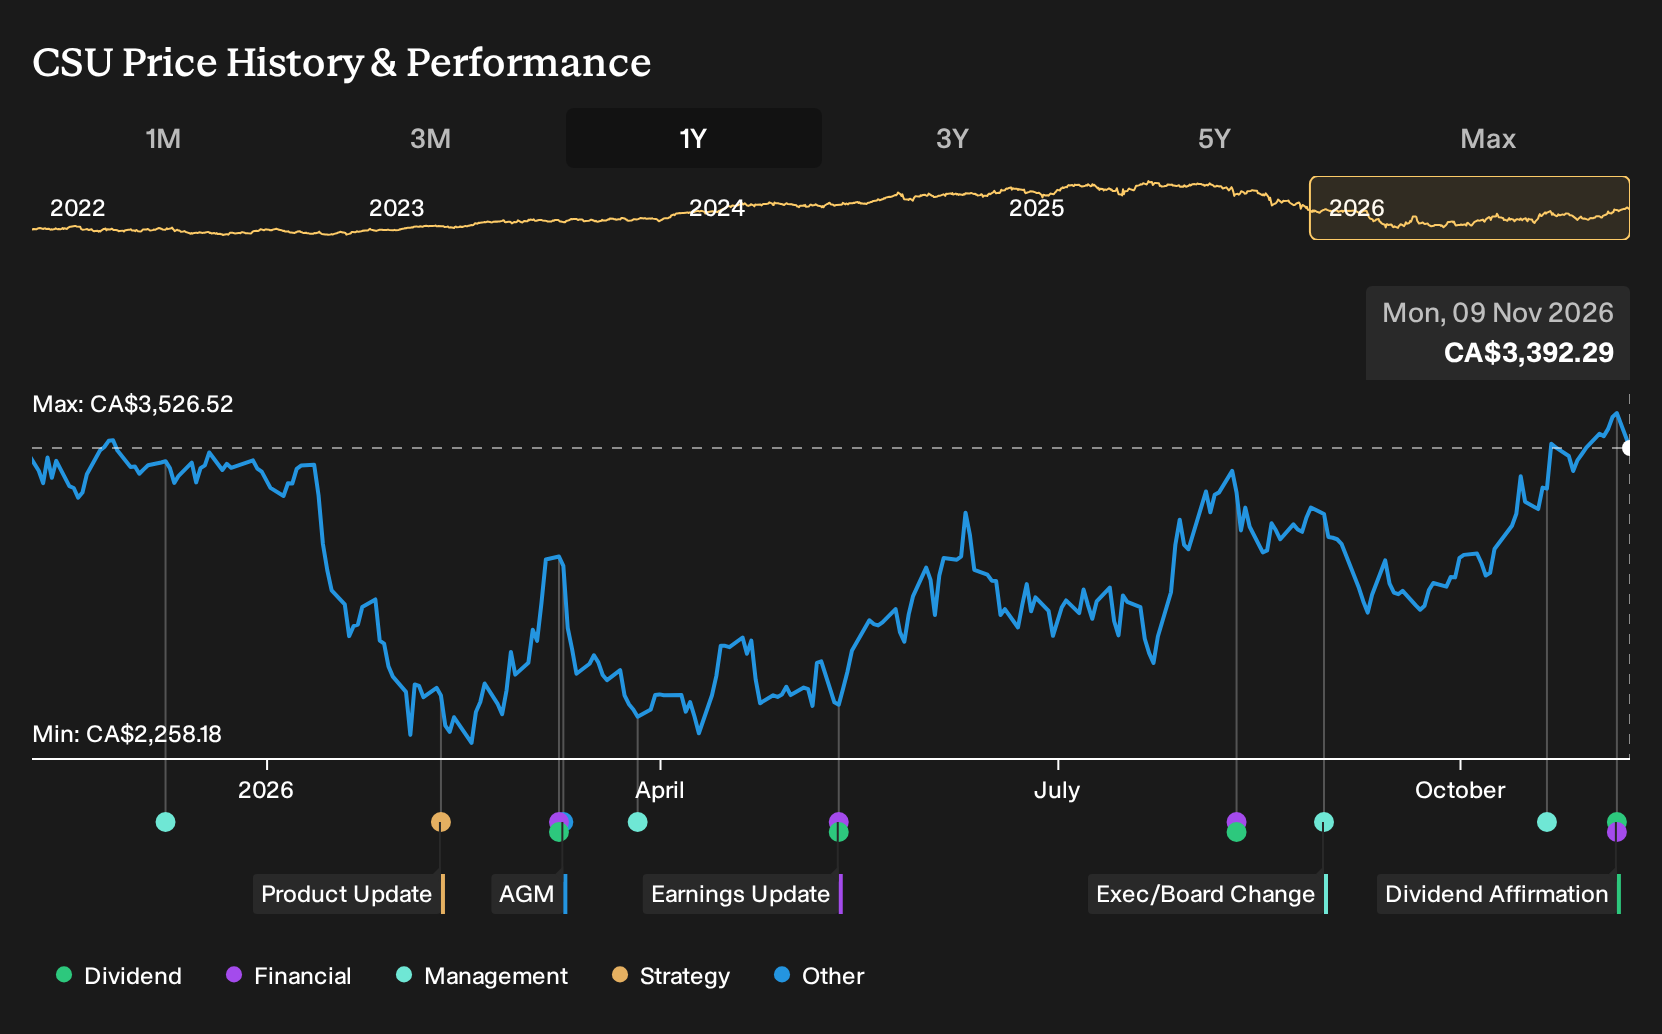
- Constellation Software (TSX:CSU) fell 3.81% as investors reacted to modest organic revenue trends despite higher analyst price targets.
- Leon's Furniture (TSX:LNF) declined 2.56% after Q3 sales slipped slightly on softer furniture demand and supply chain disruptions.
- Baytex Energy (TSX:BTE) slipped 2.03% following recent gains after earnings and analyst upgrades highlighted its capital program and production plans.
On The Radar
Canadian trading over the next few sessions revolves around inflation data and a heavy run of domestic earnings that line up directly against today’s US CPI print.
- US CPI and Core CPI Tue 10 Nov. A monthly headline reading against the 0.6% previous figure and core versus the 0.3% prior level will inform expectations for a potential December Fed hike, which often moves the Canadian dollar and local rate sensitive stocks.
- Canadian Tire Corporation Thu 12 Nov. Q3 2026 results before the open will put the focus on revenue resilience and retail margins, providing an update on how higher borrowing costs and cautious shoppers are affecting Canadian discretionary spending.
- Brookfield Thu 12 Nov. Third quarter numbers at 7:00 a.m. Eastern will shift attention to fee related earnings and capital deployment, which are important for how investors assess Canadian alternative asset cash flows when global rates are still elevated.
- Keyera Tue 10 Nov. Q3 2026 figures at 9:30 a.m. Eastern will highlight how midstream volumes and segment profitability are tracking against commodity price volatility, an important signal for income focused investors in Canadian energy infrastructure.
- Canada CPI Mon 16 Nov. October inflation is scheduled at 1:30 p.m. UTC and will be compared against the prior 3.1% headline and 2.2% core readings, with any clear move either side likely to influence Bank of Canada path expectations and domestic bond yields.
Sector & Industry Watch
Materials and Metals and Mining: Miners extend strong seven day run
Materials and Metals and Mining have led the Canadian market over the last week, with both groups posting double digit 7 day gains while the 1 year returns are also strong. Fresh updates from Barrick, Endeavour Silver, AbraSilver and others keep attention on projects tied to gold, copper and battery metals as China trade data points to firm import demand.
If you hold Canadian miners, the single macro event that can quickly confirm or cool this momentum is today’s US CPI release, since any surprise on inflation often feeds directly into gold pricing and investor appetite for long life resource projects.
Energy and Oil and Gas: Strong 12 month run, choppy week
Energy and Oil and Gas have pulled back over the last 7 days after a much stronger 1 year period, with the weekly returns down even though the annual figures remain positive. Deals at Strathcona and ongoing tax incentives mentioned by Whitecap show producers still putting cash to work on acquisitions, payouts and carbon projects despite the recent slide.
If your portfolio includes Canadian oil producers or pipelines, the key catalyst to watch is this week’s US crude and gasoline inventory data, because any surprise build or draw can quickly sway expectations for export demand and the cash flow that supports dividends and capital spending.
Financials and Banks: Income theme supported by payout moves
Financials have carried on their solid 12 month advance with a smaller 7 day gain, while Banks show a similar pattern of strong annual performance and steadier recent trading. Dividend increases and renewed buybacks at iA Financial along with repurchase plans at Quinsam Capital and overseas expansion moves from Royal Bank of Canada and Brookfield Asset Management keep income and fee growth in focus.
If you lean on Canadian Financials for yield, the main trigger now is upcoming guidance from insurers and asset managers, since any shift in tone on credit quality or capital deployment can influence how investors view the reliability of dividends and appetite for further share repurchases.
Tech and Semiconductors: Ongoing slump tests rate sensitive names
Tech and especially Semiconductors remain weak on a 7 day, 30 day and 1 year view, with Semiconductors showing a very large 12 month decline even as companies such as Enghouse Systems and Vecima Networks announce deals or dividends. The group is highly sensitive to interest rate expectations because many stocks are valued on profits that are expected further out in time.
If you own Canadian Tech or chip exposure, today’s US core CPI print is the single macro release to watch, since any change in views on the future path of rates can quickly alter how much investors are willing to pay now for longer dated growth stories.
Real Estate: REITs grind higher on retail resilience
Real Estate has edged up over the last week and month while 1 year and year to date returns remain slightly weak, helped by grocery anchored and retail focused REITs such as Crombie, CT REIT and Primaris that report high occupancy or portfolio growth. Office focused trusts including Dream Office still reflect concern about borrowing costs and tenant demand even as financing deals and acquisitions proceed in parts of the sector.
If you rely on Canadian REITs for monthly distributions, the clearest domestic catalyst now is next Monday’s Canada CPI release, because the combination of inflation and the recent 6.7% unemployment rate shapes expectations for Bank of Canada policy, refinancing terms and how much rent growth tenants can absorb without pushing vacancy higher.
How To Act On Today's Market
If steady dividends are the part of today’s story that matters most to you, start with this list of 3 dividend fortresses to see which payers look built to handle higher rates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com