


EN
Prologis (PLD) Could Be 15% Undervalued Following Joliet Logistics Park Deal
Prologis (PLD) just linked up with Gaming and Leisure Properties to turn the former Hollywood Casino Joliet into a multi-building warehouse park, a project that puts its development engine firmly in the spotlight for investors.
Set against these headlines, Prologis’ share price has moved to US$130.55, with a 1-day share price return of 2.83% and a year-to-date share price return of 1.16%. Total shareholder return of 7.81% over one year and 40.31% over three years signals longer term momentum despite a 90 day share price return that has declined 6.42%.
Scan how other logistics and warehouse players stack up against Prologis’ latest move by running your filters through 42 power grid technology and infrastructure stocks to identify potential infrastructure-linked beneficiaries across the supply chain.
Prologis is leaning hard into its development platform with Joliet, while the share price has barely budged this year. Is the current valuation still about warehouses and cash flows, or is it mostly about sentiment catching up late?
Most Popular Narrative: 14.6% Undervalued
Prologis is priced at $130.55 while the analyst consensus Narrative on Simply Wall St ascribes a fair value of $152.85. This frames Joliet and the broader development push as part of a wider cash flow story rather than a one off project.
The build out of value added services, including a dedicated data center development platform with 5.8 GW of power pipeline and an expanding on site solar and storage business of roughly 1.3 to 1.4 GW, creates additional fee and rental streams that can support higher consolidated revenue and margins as projects are delivered.
See why 114 investors see Prologis as 15% undervalued.
Result: Fair Value of $152.85 (UNDERVALUED)
Still, the Prologis narrative can break if fresh equity raises dilute per share outcomes or if the US$18.8b to US$19b SEGRO deal fails to deliver.
Find out about the key risks to this Prologis narrative.
Another View: Prologis Through The P/E Lens
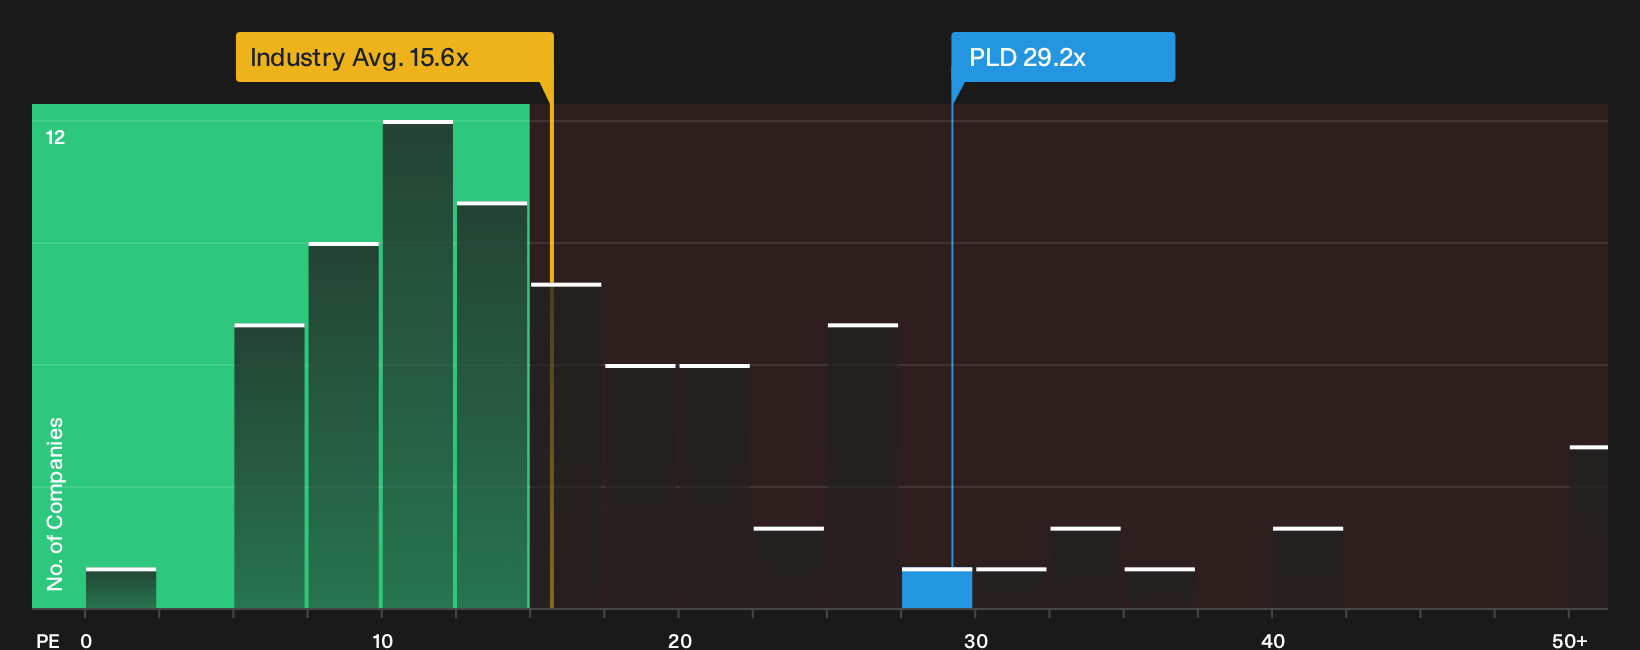
There is a different read on Prologis if you step away from cash flow models and just look at the earnings multiple. The shares trade on a P/E of 29.2x, above both direct peers at 25.5x and the wider Industrial REITs group at 15.6x, even though the fair ratio sits higher at 32.8x. That mix of premium pricing and a gap to the fair ratio leaves you with a simple question: Is this a quality premium that still has room to close, or is it extra valuation risk layered on top of a crowded Prologis story?
To unpack what this earnings multiple gap really means in practice, including how it could widen or narrow as sentiment shifts, take a closer look at our valuation breakdown through See what the numbers say about this price — find out in our valuation breakdown..
For a visual read on how Prologis stacks up against the sector on earnings, keep the P/E chart in mind as you compare those premiums and discounts over time
Next Steps
Big valuation gaps and rich P/E debates only get you so far. Act quickly, review the data yourself, then weigh Prologis through 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Prologis?
If Prologis has sharpened your focus on quality and price, do not stop here. Broaden your watchlist now so you are not late to the next setup.
- Target higher potential upside by scanning a curated pool of 19 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- Pressure test your need for stability by running your filters against a 30 resilient stocks with low risk scores that screens for resilience when conditions turn choppy.
- Tighten your margin of safety by hunting through a list of solid balance sheet and fundamentals (25 results) that focuses on durable balance sheets and fundamental strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com