


EN
Barrenjoey Group (ASX:BJY) After The Partnership Income Shift And Why Valuation Views Differ
Fresh analysis of Barrenjoey Group (ASX:BJY) has highlighted a bigger role for partnership income and a tilt toward capital light fee streams, prompting investors to reassess how its earnings mix is evolving.
Recent price action shows that Barrenjoey Group has bounced in the short term, with a 7 day share price return of 6.61% and a 30 day gain of 5.49%. However, momentum has faded compared to a 90 day share price decline of 16.16% and a modest 1 year total shareholder return of 0.35%.
Scan beyond Barrenjoey Group and compare its capital light, fee driven model with a hand picked 14 high quality undiscovered gems built around similar quality focused fundamentals.
Barrenjoey Group appears to be a solid fee-driven operator, yet the share price has only recently bounced after a longer stretch of weakness. Does that create a potential bargain, or has the market already adjusted?
Most Popular Narrative: 8% Overvalued
On Simply Wall St, the analyst consensus Narrative on Barrenjoey Group points to a fair value of A$8.39 per share. This sits below the last close of A$9.03 and frames the current price as richer than that estimate, using a 7.78% discount rate to value future cash flows.
The shift to a three pillar structure that would have produced A$778 million of pro forma FY26 revenue with roughly equal contributions from Financial Markets, Corporate Finance and Investment Management positions Magellan Financial Group to draw on more than one earnings stream, which can influence group revenue resilience and operating profit over time.
See why 46 investors see Barrenjoey Group as 8% overvalued.
Result: Fair Value of A$8.39 (OVERVALUED)
Still, fee pressure on Magellan’s global equities arm and the impact of lower revenue from repriced funds could challenge how durable that Barrenjoey linked narrative really is.
Find out about the key risks to this Barrenjoey Group narrative.
Another View: Cash Flow Signals A$14.04 Value
The earlier narrative framed Barrenjoey Group as about 8% overvalued against an A$8.39 fair value based on analyst expectations. A different lens tells a very different story. Simply Wall St’s DCF model points to a future cash flow value of A$14.04 per share, which is comfortably above the A$9.03 last close. That kind of gap can sometimes reflect a safety margin if cash flows play out as modelled, or it can highlight how sensitive long range assumptions are to small changes in growth, margins or discount rates. Which story feels closer to how you see this business playing out over time?
For a closer look at how that cash flow based estimate is built, including the key inputs that drive it, walk through the Look into how the SWS DCF model arrives at its fair value..
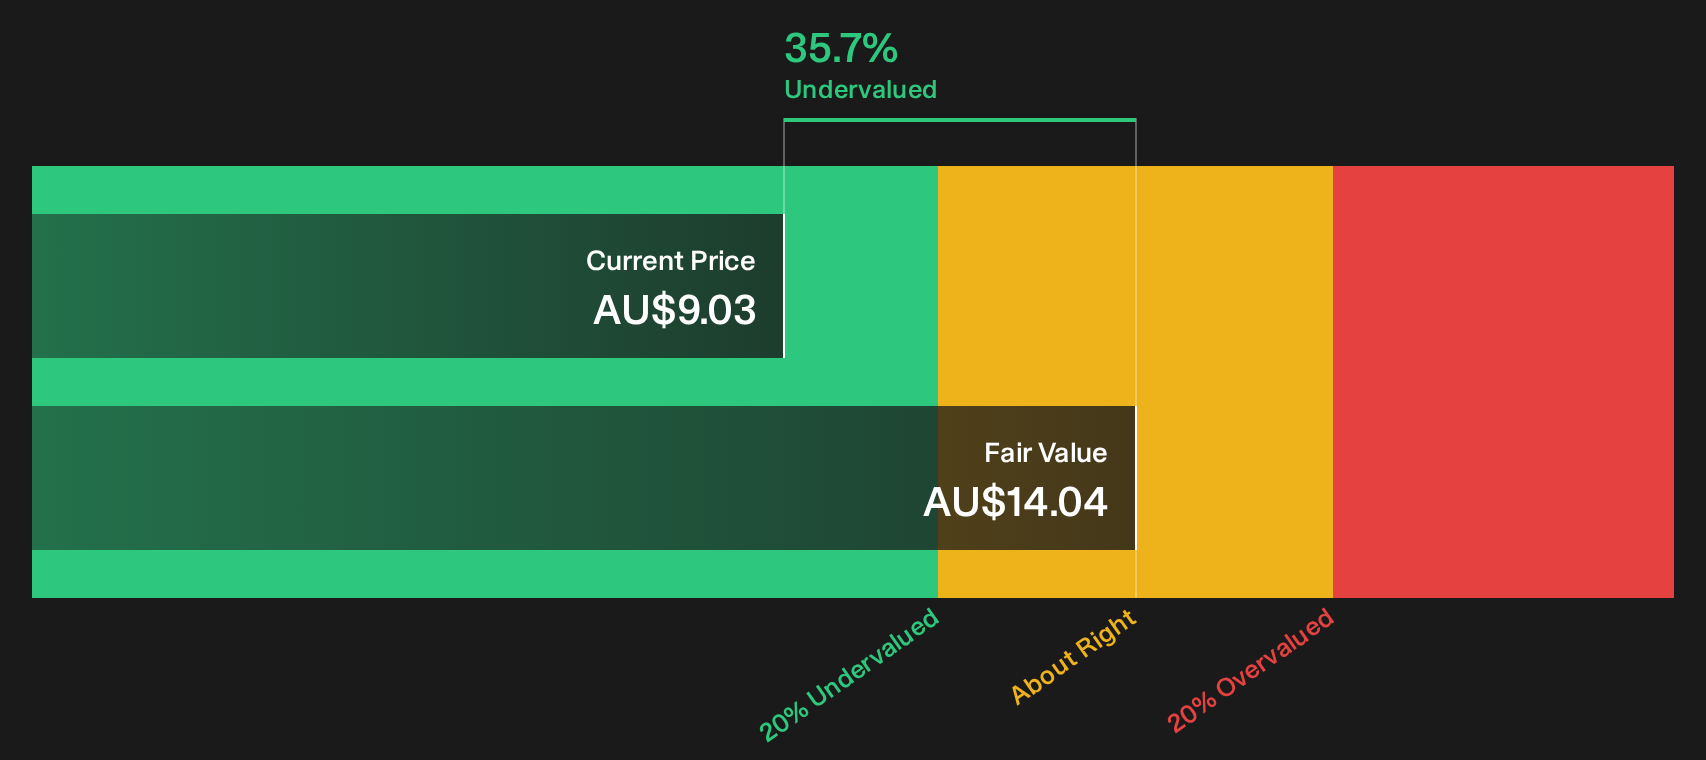
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barrenjoey Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 2 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Barrenjoey Group is clearly split, with both red flags and bright spots in view. Act quickly, review the data, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Barrenjoey Group?
If you only stop at Barrenjoey Group, you risk missing other opportunities that could fit your goals even better, so widen your research before you commit.
- Target stronger balance sheet resilience by running the list of solid balance sheet and fundamentals (12 results) and focus your time on companies with healthier financial foundations.
- Hunt for mispriced quality by scanning the 2 high quality undervalued stocks and compare those candidates with the valuation debate around Barrenjoey Group.
- Tilt toward consistency and income by reviewing a curated set of 5 dividend fortresses that could complement a fee driven stock such as Barrenjoey Group.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com