


EN
US Stock Market Today: S&P 500 Futures Edge Up On Critical CPI Decision Risk
The Morning Bull - US Market Morning Update Tuesday, Nov, 10 2026
S&P 500 futures are pointing modestly higher, with investors focused almost entirely on October US CPI. Rate sentiment leans cautiously optimistic, as the market narrative hinges on whether inflation looks contained enough to avoid a sharp policy shift.
Economists expect headline CPI at 0.3% month on month and core at 0.2%. Fed officials, including Governor Waller, have noted that a December hike, possibly up to 50 bps if inflation jumps, remains on the table, and that keeps rate expectations sensitive to today’s release.
If CPI aligns with the 0.2% to 0.3% range, that view supports the idea that borrowing costs are already restrictive and could limit pressure for aggressive tightening. Any upside surprise, combined with stubborn 1 year inflation expectations at 3.9%, would strengthen the case for higher yields and a tougher backdrop for equities.
The unresolved question is straightforward: does a single CPI print justify the Fed’s recent openness to another hike, or does it argue for a longer pause while officials reassess growth, inventories and consumer pricing pressure into year end?
Stocks to Watch Before the Opening Bell
NVIDIA (NVDA)
Fresh attention on US export rules is back in focus for NVIDIA. Three bipartisan proposals in Congress would tighten controls on advanced chip shipments, with the AI OVERWATCH Act potentially tied to the upcoming defense bill. Lawmakers are also pushing for more oversight of NVIDIA after questions around CEO Jensen Huang’s contacts. Watch for any draft text or hearing dates.
Micron Technology (MU)
Micron Technology is linked to Anthropic’s planned US$90.4b IPO and private placement. Anthropic and some existing holders aim to raise that amount, with Micron among the large tech groups participating in the private deal. The partnership ties Micron more closely to frontier AI spending. Keep an eye on final IPO terms and Micron’s disclosed commitment size.
Morgan Stanley (MS)
Morgan Stanley is adding more plumbing behind its equity compensation franchise. The bank agreed to acquire Vinyl Equity, an SEC registered digital transfer agent that handles shareholder records and cap tables. Vinyl is set to plug into Morgan Stanley at Work and follows the EquityZen deal. Closing is targeted for Q1 2027, so investors will watch for regulatory approvals and any integration costs.
Top Movers
- Coherent (COHR) jumped 16.79% after multiple analysts raised price targets following strong recent quarterly results.
- Monolithic Power Systems (MPWR) climbed 16.60% despite a jury verdict favoring Reed Semiconductor in the patent dispute.
- Ubiquiti (UI) advanced 15.66% after a Barclays analyst increased the price target following a strong fiscal Q1 revenue beat.

Top Losers
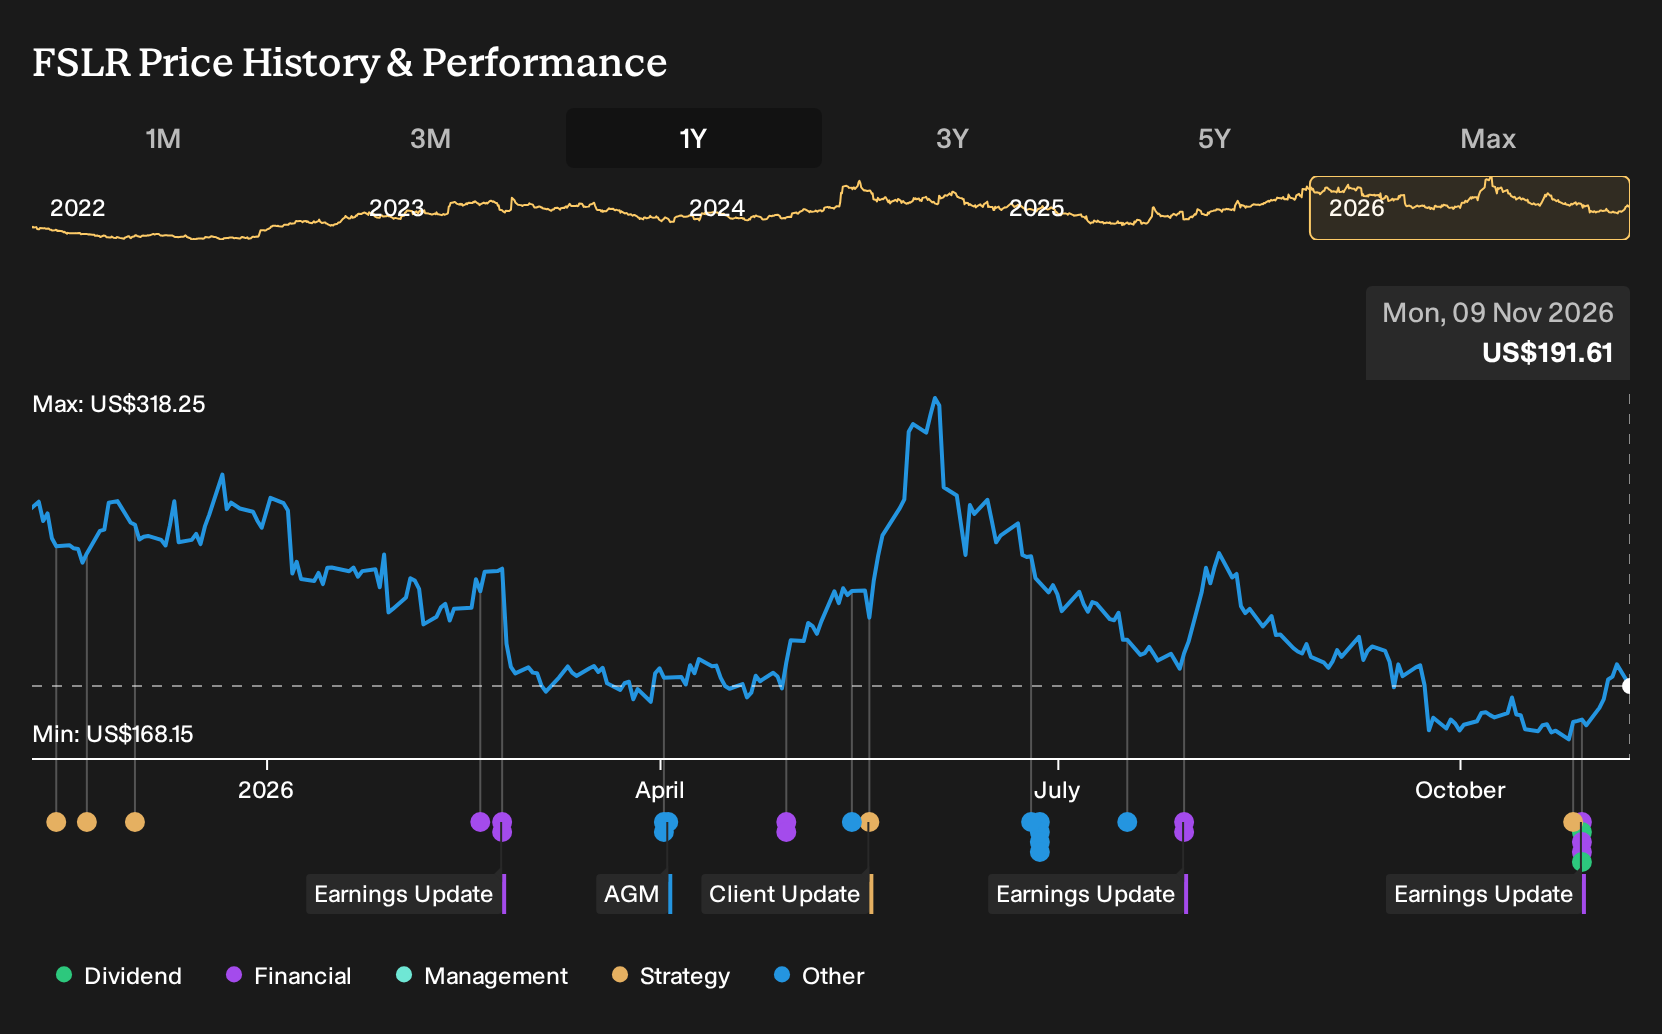
- First Solar (FSLR) declined 4.74%.
- Alibaba Group Holding (BABA) fell 3.72%.
- Take-Two Interactive Software (TTWO) slipped 3.48% following mixed Q2 results and cautious guidance around Grand Theft Auto VI.
On The Radar
US inflation and Fed communication sit at the center of the next few sessions, with a cluster of CPI, PPI and jobs data aligned with key earnings from bellwether companies.
- US CPI and Core CPI Tue 10 Nov. Headline CPI is forecast at 0.3% m/m and core at 0.2%. A reading above those marks would likely align with higher borrowing cost expectations and keep pressure on interest rate sensitive US sectors.
- Fed Waller, Logan, Bowman, Schmid Speeches Tue 10 Nov. With officials already highlighting a possible December hike, any emphasis on inflation risks or data dependence could influence US rate expectations and the path of Treasury yields into year end.
- US PPI and Core PPI Fri 13 Nov. Producer prices are expected at 0.4% m/m for headline and 0.3% for core. Outcomes above those levels would point to firmer corporate cost pressures and could contribute to tighter US financial conditions.
- US Retail Sales and Control Group Tue 17 Nov. October retail trends, including the control group after a 0.1% prior reading, will indicate how consumer demand compares with higher rates and what that means for US discretionary and staples stocks.
- Tyson Foods Mon 16 Nov. Q4 2026 results arrive pre market, with margins and forward commentary on input costs central to how investors assess pricing power across packaged food and broader US consumer staples.
Sector & Industry Watch
Semiconductors: AI chips meet policy and profit risks
Chip stocks have had a rough week, with Semiconductors falling over the last 7 days after an even weaker 30 day spell, despite a positive year to date and 1 year picture. Nvidia export probes, US bipartisan export bills and new AI hardware from Google, AMD and Cerebras keep attention on how sensitive this group is to Washington as well as data center demand.
For anyone holding chip ETFs or AI hardware stocks, today’s US CPI and the follow up Fed speeches are pivotal because a hotter print can keep yields high, which tends to pressure high multiple sectors and can affect how aggressively cloud giants fund new AI builds.
Energy & Oil and Gas: Strong 12 months, choppy recent oil tape
Energy and Oil and Gas both show very strong 1 year gains of a little over 32% but have retreated over the last week and month as crude softens and rate expectations stay hawkish. Deals at ExxonMobil, Summit Midstream, Tidewater and NRG’s planned plant sales show producers and midstream players still reshaping portfolios while they weigh debt costs and future demand.
If you own US producers, pipelines or LNG related stocks, the weekly EIA crude and gasoline inventory data plus today’s CPI are worth tracking because sharp swings in stockpiles or inflation can feed directly into pump prices, sector sentiment and how investors compare Energy with more rate sensitive parts of the market.
Real Estate: REITs enjoy yield pause but still rate exposed
Real Estate has quietly outperformed the US Market over the past 7 days and 30 days and is ahead year to date and over 12 months, helped by a small recent pull higher. Moves such as SmartStop Self Storage’s equity raise, Douglas Elliman’s buyback plan and National Health Investors’ property reshuffle underline how boards are trying to balance cash returns with leverage while borrowing costs stay elevated.
If your portfolio includes REITs or property heavy funds, this week’s US Existing Home Sales and the run of Fed speeches after CPI matter because housing turnover and rate expectations together influence lender appetite, cap rates and ultimately how comfortable management feels keeping current dividend levels.
Healthcare & Pharmaceuticals & Biotech: Drug pipelines support defensive earnings
Healthcare and Pharmaceuticals & Biotech have both risen over the last week, with 7 day gains ahead of the US Market and strong 1 year returns. Positive drug and device news from Johnson & Johnson, Eli Lilly, Merck and several smaller biotechs is keeping focus on trial data and approvals rather than day to day economic swings.
For holders of big pharma or biotech ETFs, today’s CPI print and any change in medical cost components are the items to watch because they can affect reimbursement debates, insurer margins and how investors weigh Healthcare against other defensives like Utilities and Staples.
Consumer Discretionary & Automobiles: Shoppers split between value and big ticket strain
Consumer Discretionary has edged higher over the last week and month but is still down a little over 4% across 12 months, while Automobiles show declines over every period provided, including a drop of more than 15% over the past year. Earnings news from Somnigroup, MasterCraft, Lucid, Goodyear and Coupang highlights how sensitive big ticket and optional spending remains to financing costs, promotions and regulatory pressure.
If you hold retailers, leisure or car makers, US CPI and Thursday’s jobless claims are key because any surprise on wages or shelter can influence household budgets, which often hits discretionary and auto spending before more essential categories.
How To Act On Today's Market
With Fed officials openly discussing another potential hike and rate sensitive areas still in focus, you can stress test your portfolio’s defense by starting with this list of 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com