


EN
How Core Banking Upgrade Will Impact CIBC Stock Investors
- Canadian Imperial Bank of Commerce recently issued several fixed rate senior unsecured notes maturing between 2028 and 2039 and also confirmed a partnership with Thought Machine that supports the launch of new digital products such as the Simplii Account.
- The mix of long dated callable funding and a cloud based core banking build suggests Canadian Imperial Bank of Commerce is aligning its balance sheet and technology stack around fee rich everyday banking and digital productivity gains.
- We will now see how Canadian Imperial Bank of Commerce long dated fixed income issuance and core banking overhaul might reshape its investment narrative.
Canadian Imperial Bank of Commerce Investment Narrative Recap
To own Canadian Imperial Bank of Commerce, you need to believe the bank can keep growing fee based wealth, everyday banking and capital markets while managing credit risk in Canadian mortgages and consumer lending. The analyst consensus narrative on Simply Wall St leans on earnings quality, with high quality profit, 32.2% margins and a strong capital position as key supports.
The recent run of 5.25% to 6.10% senior unsecured notes out to 2039 looks incremental rather than game changing. It slightly extends funding duration and adds callable flexibility, but the nearer term catalyst still sits in credit trends and consumer health. The main risk remains a deeper or longer soft patch in Canadian housing and borrower quality.
The 5.25% to 6.10% fixed coupon, callable senior unsecured issues, including the 6.00% notes due 2038 and 5.75% notes due 2033, feel most relevant right now. They add long dated funding that can support lending and everyday banking growth where CIBC is already leaning into higher margin cards and personal banking.
If that shift continues, the funding stack from these bonds could help underpin efforts to maintain a 3.04% net interest margin in Canadian Personal and Business Banking and to keep capital strong at a 13.4% CET1 level. Execution risk sits in credit quality. A broad weakening in borrower health would pressure both earnings and the flexibility that this funding is meant to support.
Canadian Imperial Bank of Commerce's narrative projects CA$36.9b revenue and CA$12.4b earnings by 2029. That profile assumes revenue growth of 7.2% per year and an earnings increase of about CA$2.7b from CA$9.7b today.
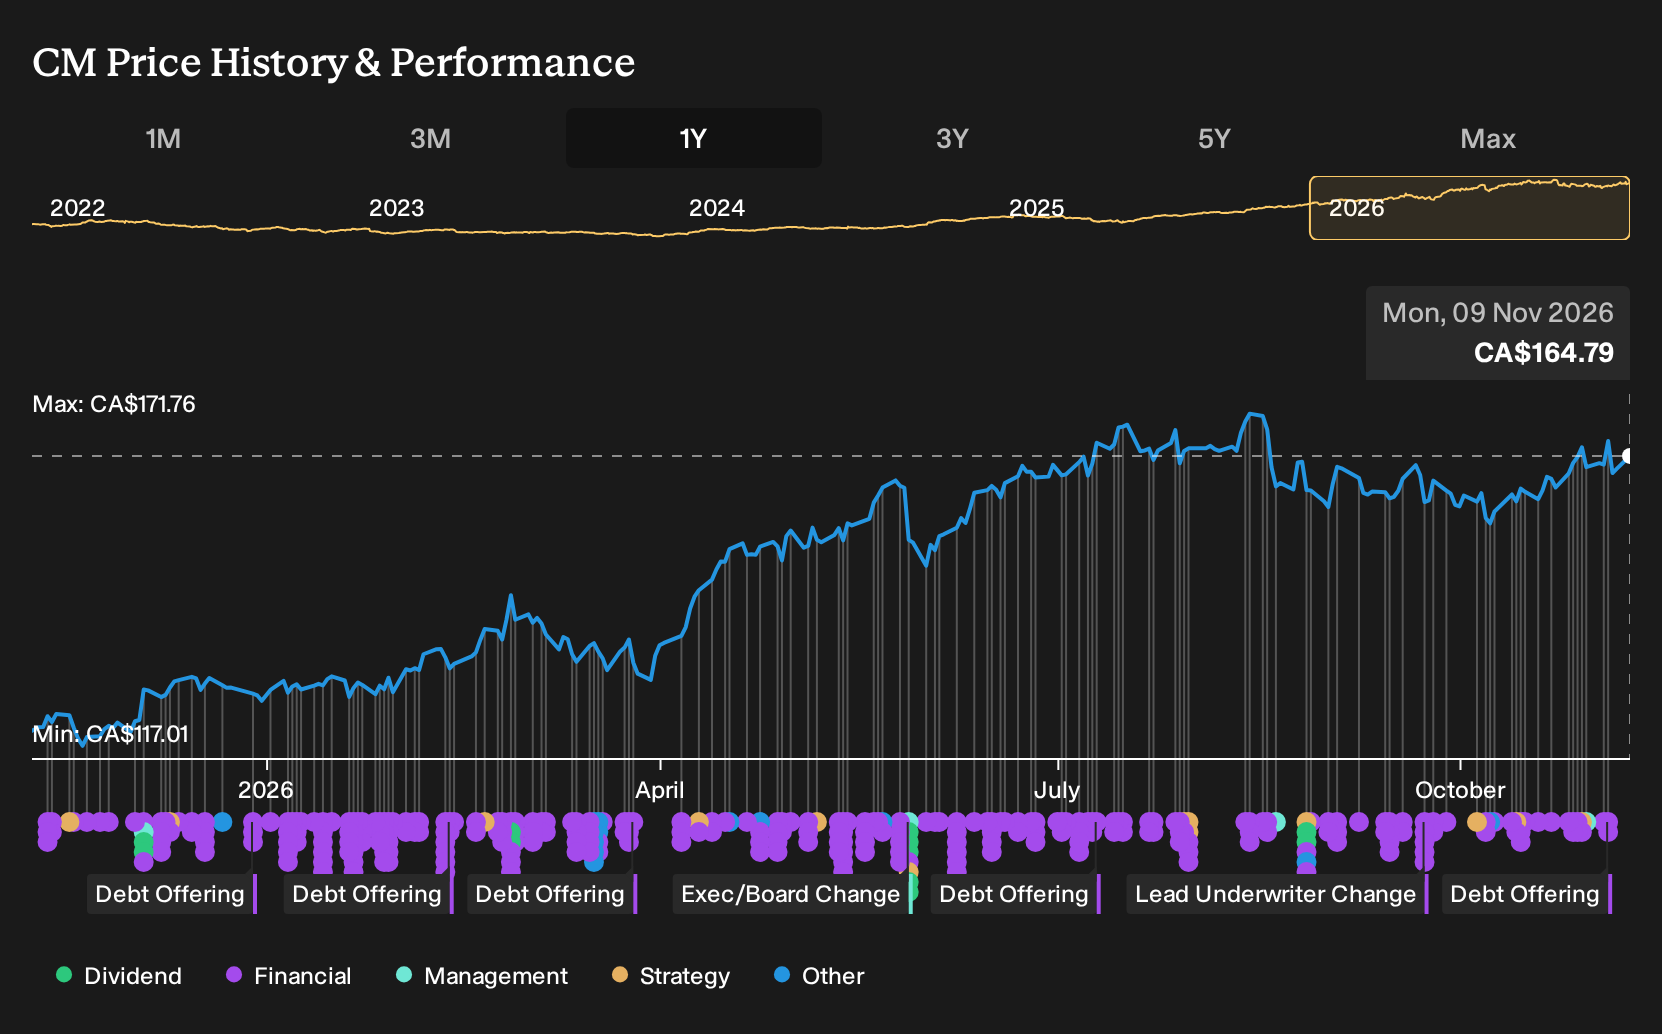
Discover how Canadian Imperial Bank of Commerce's fair value indicates a 3% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Across 2 fair value estimates from the Simply Wall St Community, Canadian Imperial Bank of Commerce sits in a wide band between CA$170.50 and CA$241.14, with some retail investors projecting very optimistic upside. Those views now meet fresh information on higher coupon callable bonds and a new chair incoming in 2027, so you may want to weigh how funding costs and governance could influence future earnings resilience. You may also want to compare several contrasting viewpoints before deciding how this story fits your portfolio.
Explore another Canadian Imperial Bank of Commerce fair value estimate, including one that indicates potential upside of up to 46% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Canadian Imperial Bank of Commerce research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Canadian Imperial Bank of Commerce. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Canadian Imperial Bank of Commerce's overall financial health at a glance.
Looking for more investment ideas beyond Canadian Imperial Bank of Commerce?
If you want to put what you have learned from Canadian Imperial Bank of Commerce into practice, it can help to scan a wider set of companies using the Simply Wall St Screener and look for similar balance sheet strength, earnings quality, or income potential.
- For investors who care most about downside protection, you could scan a 9 resilient stocks with low risk scores that prioritize resilient balance sheets and steadier risk profiles.
- If value is the priority, you might focus on a 6 high quality undervalued stocks that highlight financially solid businesses trading at what could be attractive prices.
- Income focused readers can look for consistent cash payouts through a 3 dividend fortresses that filters for companies offering stronger yield profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com