


EN
DAIHEN Stock After Raised Earnings Guidance And Dividend Outlook
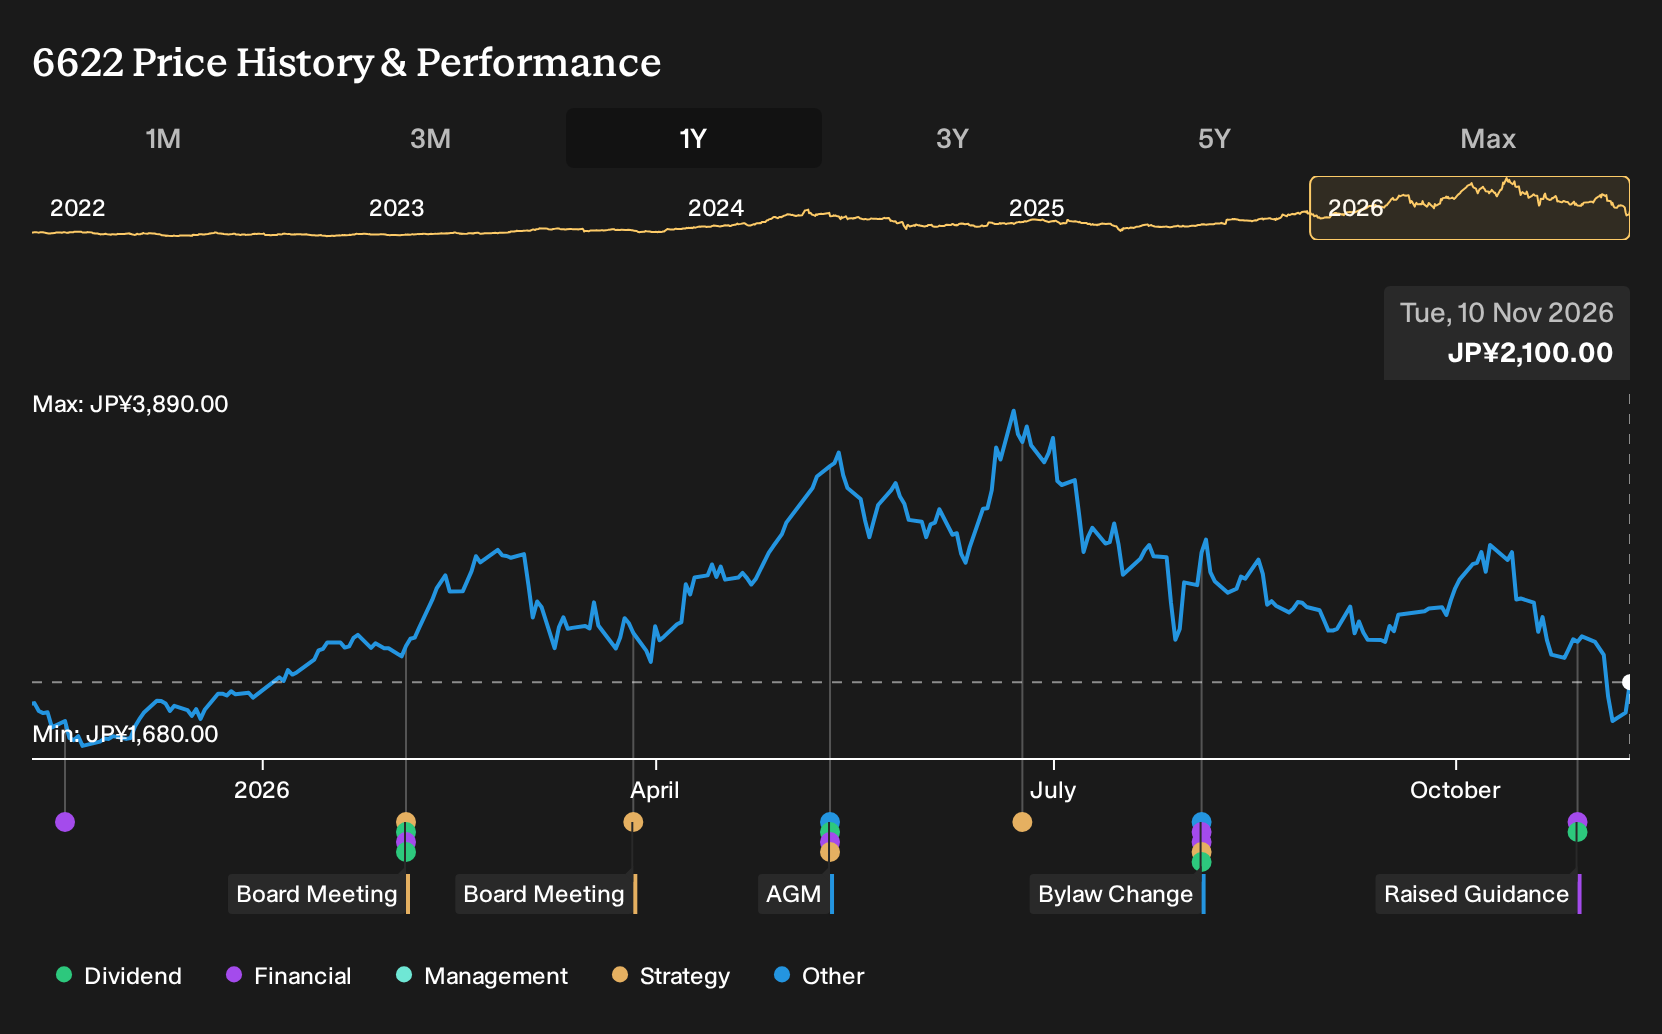
- DAIHEN Corporation revised past guidance on October 29, 2026, lifting forecasts for net sales, operating profit, earnings per share, and the year end dividend for the periods to September 30, 2026 and March 31, 2027, supported by stronger semiconductor capital spending and storage battery system orders.
- The company tied its higher year end dividend forecast of ¥30.00 per share to a policy of maintaining a payout ratio of at least 30%, which gives investors a clearer view of how rising earnings expectations may translate into future cash returns.
- We will now look at how DAIHEN's investment narrative is affected by its upgraded earnings outlook, particularly the stronger storage battery orders.
What Is DAIHEN's Investment Narrative?
To own DAIHEN, you have to buy into a fairly simple idea. This is an industrial business tied to real equipment demand in energy management, factory automation, and material processing, where execution and capital allocation matter more than story. The upgraded guidance on October 29, 2026 signals firmer order momentum in semiconductor related capex and storage battery systems. This directly feeds into utilization of its factories, pricing power on specialized products, and the cash available to support that higher dividend payout policy.
In the short term, the key swing factors are how steadily those semiconductor and renewable linked orders actually convert into shipped product and margin, and how much capital spending DAIHEN needs to commit to keep up. Raised full year targets and a guided year end dividend of ¥30.00 per share sharpen the focus on free cash flow, especially given prior flags around dividend coverage and share price volatility. The catalyst is clear and execution against this higher bar is now the test.
That said, there is a less comfortable piece of the DAIHEN story that sits right next to this upgraded guidance and ...
There's only one way to know the right time to buy, sell or hold DAIHEN. Head to Simply Wall St's company report for the latest analysis of DAIHEN's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so you may wish to rely on your own judgment.
- A great starting point for your DAIHEN research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DAIHEN. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easier to evaluate DAIHEN's overall financial health at a glance.
Looking For More Ideas Beyond DAIHEN?
If DAIHEN's updated guidance has sharpened your interest in power, automation, and resilient cash flows, it can help to widen the lens and compare it with other listed businesses that share some of those qualities but approach risk and income in different ways.
- If you want income to play a bigger role in your portfolio, consider stocks that have delivered reliable cash distributions by reviewing 27 dividend fortresses that meet your yield and stability preferences.
- If capital preservation matters just as much as upside, you may prefer companies with steadier profiles, so it can help to filter for 18 resilient stocks with low risk scores that align with your comfort level.
- If you are hunting for future compounders before the crowd catches on, it can be useful to start with 76 high quality undiscovered gems that already show solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com