


EN
Cisco Systems (CSCO) Faces A Big Earnings Test, Is It Still Undervalued?
Cisco Systems (CSCO) heads into a closely watched earnings release this Thursday, with traders already pricing in a wide potential swing, as options imply an almost 10% move in either direction.
Recent trading tells a mixed story. Cisco Systems has rallied strongly over the longer stretch, with a year to date share price return of 29.73% and a 1-year total shareholder return of 39.38%. However, momentum has cooled in recent weeks, as the 30-day share price return is down 16.67% and the 90-day move is down 18.09%, despite a 5.11% gain in the last session to US$98.65.
Scan how options-driven swings around Cisco Systems compare with other potential opportunities by focusing on our curated list of 53 AI infrastructure stocks.
After a near 40% 1-year total return followed by a sharp pullback into earnings, is most of Cisco Systems’ rerating already in the rear-view mirror, or does the current valuation still leave room for fresh upside to play for?
Most Popular Narrative: 10.8% Undervalued
Cisco Systems closed at $98.65, while the most followed Simply Wall St Community narrative pegs fair value at $110.56, implying scope for upside based on that framework. According to kapirey, an investor in the Simply Wall St Community who wrote the narrative, the key question is how Cisco fits into the AI build out without taking on the risk profile of pure-play chip or software names.
Cisco is not a pure AI growth play; that is precisely its appeal. It offers asymmetric positioning: exposure to one of the strongest secular trends (AI), combined with defensive financial characteristics.
See why 33 investors see Cisco Systems as 11% undervalued.
That fair value estimate, using an 8.68% discount rate to value future cash flows, positions Cisco Systems as an AI infrastructure and security provider that is still tied to more traditional networking and software revenue. The memo argues that this mix offers what kapirey calls "second order AI exposure", where AI related demand in data centers and networking feeds into Cisco’s cash flows without relying solely on a narrow set of high growth use cases.
The narrative also leans heavily on Cisco’s recent earnings profile. Reported net income for the latest year is $13.27b on revenue of $63.33b, which equates to a 21% net margin, and earnings growth over the past year of 30.4% compared with 15.3% for the wider US Communications industry. That combination of margin, earnings expansion and a high 26.4% return on equity feeds directly into the argument that the cash flow stream being discounted is both sizeable and currently improving.
There is another angle that matters for anyone weighing valuation against risk. Cisco Systems is described in the memo as a "defensive AI infrastructure" play, helped by a reliable 1.7% dividend and what the author views as income friendly cash generation, while still being tied to AI networking, optics and security demand. At the same time, the narrative flags trade offs. Revenue is forecast to grow 8.5% a year and earnings 12.9% a year, which the supplied data shows is slower than the broader US market, and the firm’s AI exposure still depends on a small group of hyperscale cloud customers.
Put together, the narrative fair value of $110.56 sits above both the SWS DCF estimate of $133.06 and the $135.56 analyst price target, but the key takeaway is how that fair value is anchored. It relies on Cisco consistently converting its AI infrastructure positioning, 21% margin and high return on equity into future cash flows that justify a higher price than today without matching the growth pace of higher multiple AI peers.
Result: Fair Value of $110.56 (UNDERVALUED)
Still, Cisco Systems’ AI pitch rests heavily on a small group of hyperscale buyers, and any stumble in that transition could quickly challenge the undervaluation story.
Find out about the key risks to this Cisco Systems narrative.
Another View: Cisco Systems Through The P/E Lens
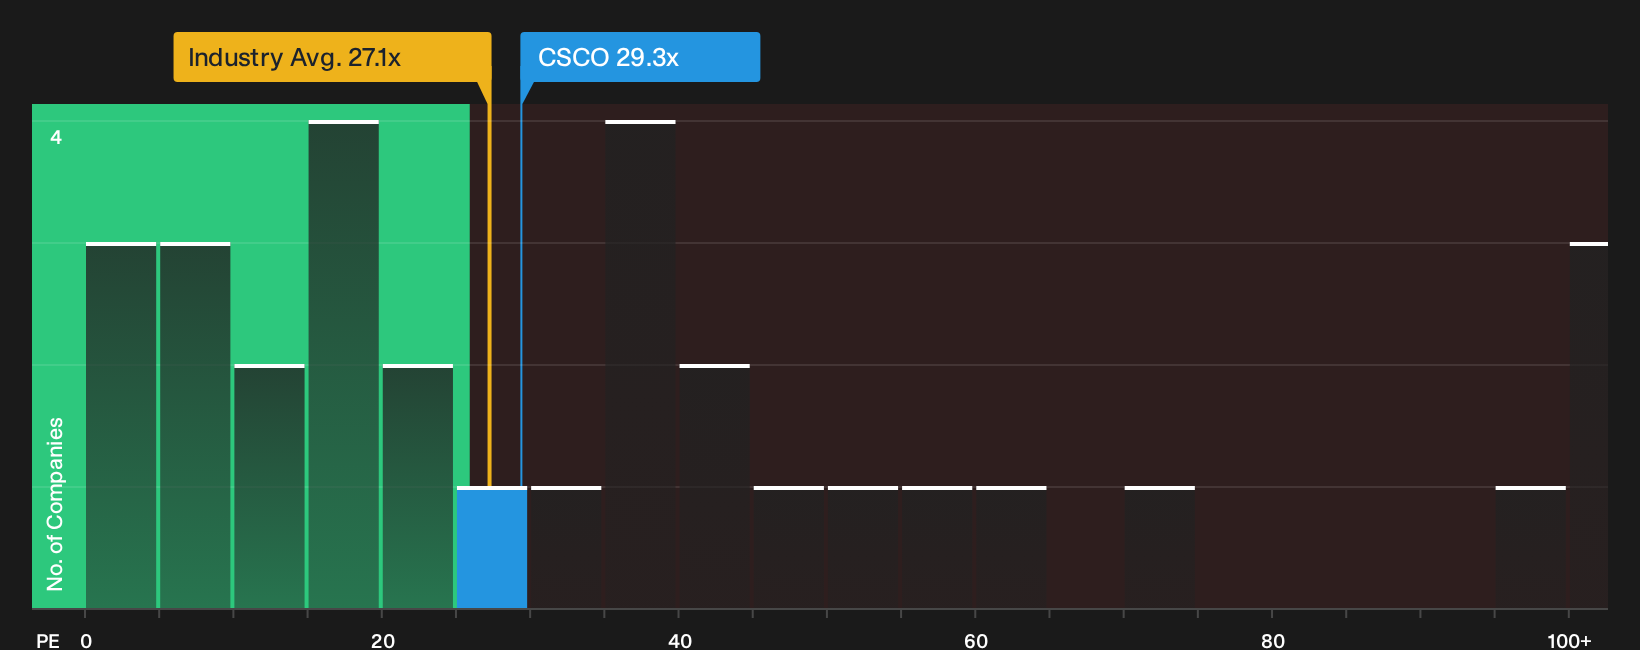
On price multiples, Cisco Systems tells a different story. The stock trades on a 29.3x P/E, which is richer than the 27.1x average for the wider US Communications group, yet below a 47.1x peer average and only slightly under the 31.1x fair ratio estimate. That mix points to less margin of safety than a cash flow model suggests, but also to less exuberance than some direct AI peers. Which signal should carry more weight when real money is on the line?
For a closer look at how that P/E profile compares with sector norms and the fair ratio Cisco could move toward over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Cisco Systems is clearly split, so consider that as a prompt to move quickly and test the numbers against your own expectations. To see what optimism in the data looks like in more detail, review the 5 key rewards.
Looking for more investment ideas beyond Cisco Systems?
If you want to stress test your Cisco view against other possibilities, use this as a cue to line up a few fresh ideas side by side.
- Target resilience by scanning a 30 resilient stocks with low risk scores that focuses on companies with sturdier risk profiles and potentially steadier return paths.
- Hunt for mispriced opportunities through a 19 high quality undiscovered gems that spotlights lesser known businesses with solid fundamentals.
- Anchor your watchlist in strength using a list of solid balance sheet and fundamentals (25 results) that highlights companies with healthier finances and room to handle shocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com