


EN
Broadcom And 2 More Undervalued Stocks To Improve Your Portfolio
With Federal Reserve governor Christopher Waller openly backing another interest rate hike and even floating a larger move if inflation stays sticky, investors are again paying for certainty and punishing anything that looks risky or unclear. That kind of rate anxiety can push solid cash machines into the bargain bin. This article walks through three stocks where current prices look low relative to their long term cash flow potential.
The three stocks highlighted below are just a starter pack, and the full screen on Simply Wall St surfaced 91 more companies with cash flow stories that look just as compelling but are not covered here. To go straight to the full Undervalued Stocks Based On Cash Flows list, analyze your options, and identify which ideas truly fit your style, head into the Undervalued Stocks Based On Cash Flows screener.
Broadcom (AVGO)
Overview: Broadcom is a digital infrastructure supplier that designs high performance data center chips and infrastructure software that keep modern networks running.
Operations: Broadcom generates about US$59.4b from Semiconductor Solutions and roughly US$29.7b from Infrastructure Software. These form two sizeable, cash-focused engines.
Market Cap: US$1.4t
For the Undervalued Stocks Based On Cash Flows theme, Broadcom matters because its data center networking silicon and cash rich software portfolio convert demand for cloud and AI infrastructure into substantial, recurring cash generation that screens as underpriced on a discounted cash flow basis according to niteco, an investor in the Simply Wall St Community.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
Future returns for Broadcom shareholders could hinge on how one still developing wave of AI infrastructure spending filters through into margins.
That margin story is still unfolding, and the full narrative for Broadcom lays out how accelerating AI infrastructure demand, integration progress, and risk points could reshape Broadcom’s cash engine.
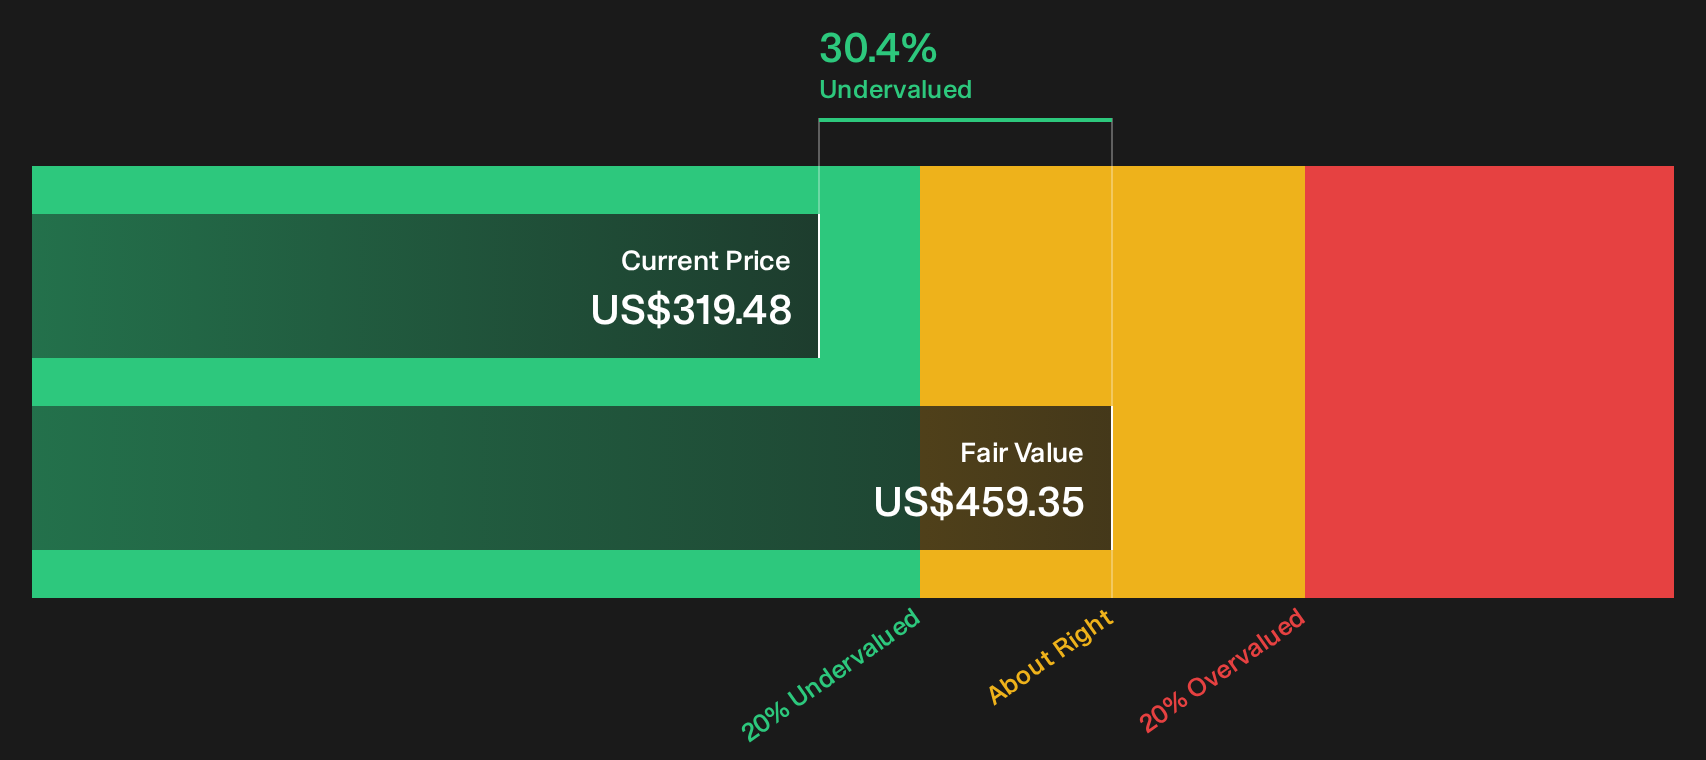
Alphabet (GOOGL)
Overview: Alphabet runs Google Search, YouTube, Android apps and devices, and the Google Cloud platform that sells AI driven enterprise services.
Operations: Alphabet generates about US$376.3b from Google Services, around US$93.2b from Google Cloud, and roughly US$1.5b from Other Bets.
Market Cap: US$3.5t
Alphabet matters for this cash flow focused screen because Google Cloud’s AI infrastructure and Vertex AI platform pair subscription style revenue with the kind of long duration contracts that can feed future free cash generation, according to oscargarcia, an investor in the Simply Wall St Community who wrote a detailed narrative on the stock.
"Google Cloud has gone from “meh” to money-maker, now #3 globally behind AWS and Azure, with over 11% market share."
What happens to Alphabet’s cash story if one unseen pressure quietly shifts how much of that AI infrastructure spend drops through to margins.
That pressure point is exactly what the full narrative for Alphabet unpacks, showing where AI cash generation could accelerate, stall, or quietly decouple from headline market share.
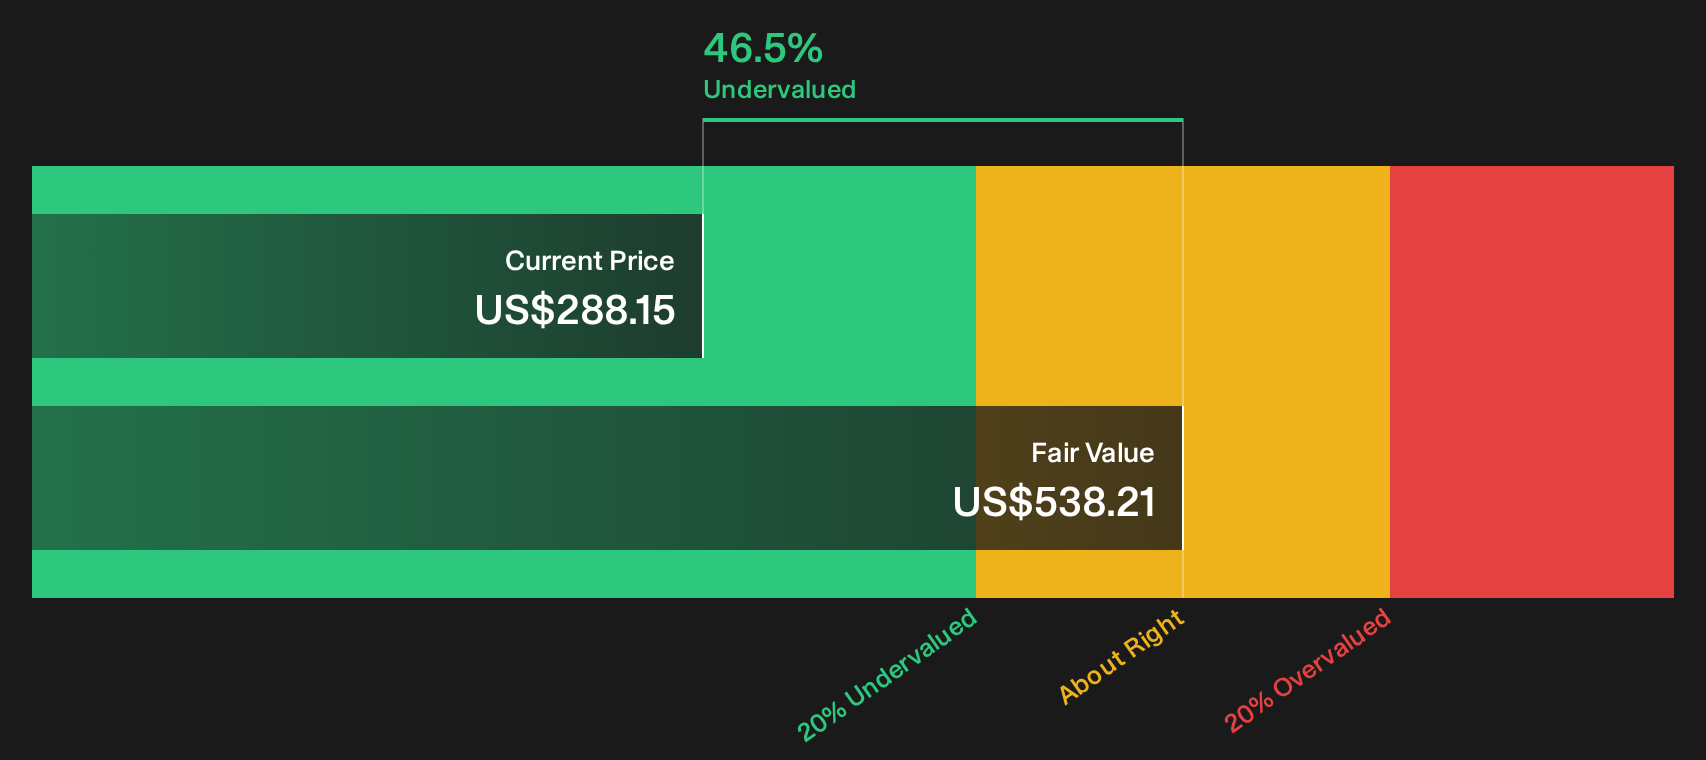
Netflix (NFLX)
Overview: Netflix runs a global streaming subscription service where recurring viewer fees, content production, and licensing drive the cash flows used in DCF valuations.
Operations: Netflix generates around US$49.7b from its Streaming Entertainment Service, delivered across regions including APAC, LATAM, and EMEA.
Market Cap: US$260.4b
Netflix matters for this cash-flow-focused screen because the subscription engine now feeds a mature, highly cash-generative model. Ivoed, an investor in the Simply Wall St Community who wrote the Narrative, argues the market may still be underpricing it relative to the durability of the underlying business.
"The bull case is still very real, but it needs more than a good quarter. It needs proof that ads become economically meaningful, that pricing remains sticky, and that margin expansion can continue without damaging engagement."
Everything comes down to how one unresolved test of Netflix’s monetisation model ultimately shapes free cash flow, margins, and long-term pricing power.
If that monetisation test is what matters most, the full narrative for Netflix maps how ads, pricing, and engagement could turn Netflix into an even stronger cash engine.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar for now. Consider researching earlier rather than waiting.
- Spot income workhorses that aim to keep paying while prices move around, then scan the 6 dividend fortresses that screens for consistency and balance sheet strength.
- Track early movers in automation that could quietly build momentum while it matters, and review the curated 91 robotics and automation stocks for focused exposure.
- Filter for resilient balance sheets before the crowd notices, using the list of solid balance sheet and fundamentals (25 results) to zero in on sturdier businesses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com