


EN
Smartgroup (ASX:SIQ) Pushes For Higher Margins, Is The Stock Fully Valued?
Why Smartgroup’s margin ambitions are back in focus
Fresh commentary on Smartgroup (ASX:SIQ) is centering on its heavier investment in operations and a plan to reach EBITDA margins in the mid 40% range by 2027.
Investors are weighing how digital and automation upgrades might support future cash flow, while also factoring in policy risk around tax settings that influence revenue from electric vehicle novated leasing.
Recent trading shows that momentum in Smartgroup’s share price has cooled in the past quarter, with a 90 day share price return that fell 13.13%. However, the year to date share price return is 28.19% and the 1 year total shareholder return is 49.09%.
Spot other companies where strong operational stories meet valuation questions by scanning our hand picked 2 high quality undervalued stocks.After a 49.09% 1 year total return and a softer 90 day patch, Smartgroup now asks a simple question of you: step in at A$11.64, or wait for the valuation to blink first?
Most Popular Narrative: 1% Overvalued
On the analyst consensus Narrative on Simply Wall St, Smartgroup’s fair value of A$11.48 sits just under the last close at A$11.64. The current quote is therefore framed as only slightly ahead of modelled worth using a 7.47% discount rate.
Substantial growth in novated leasing volumes supported by rising demand for battery electric vehicles, the reaffirmed Electric Car Discount policy through at least April 2027 and a higher BEV mix that reached 68% of new novated leasing orders in 1H26 provides a framework for Smartgroup to grow recurring novated leasing revenue and future earnings.
See why 42 investors see Smartgroup as 1% overvalued.
Result: Fair Value of A$11.48 (ABOUT RIGHT)
Still, Smartgroup’s story can wobble if novated leasing competition keeps pressuring yields, or if heavy technology spending fails to deliver the targeted margin lift.
Find out about the key risks to this Smartgroup narrative.
Another view on Smartgroup’s valuation
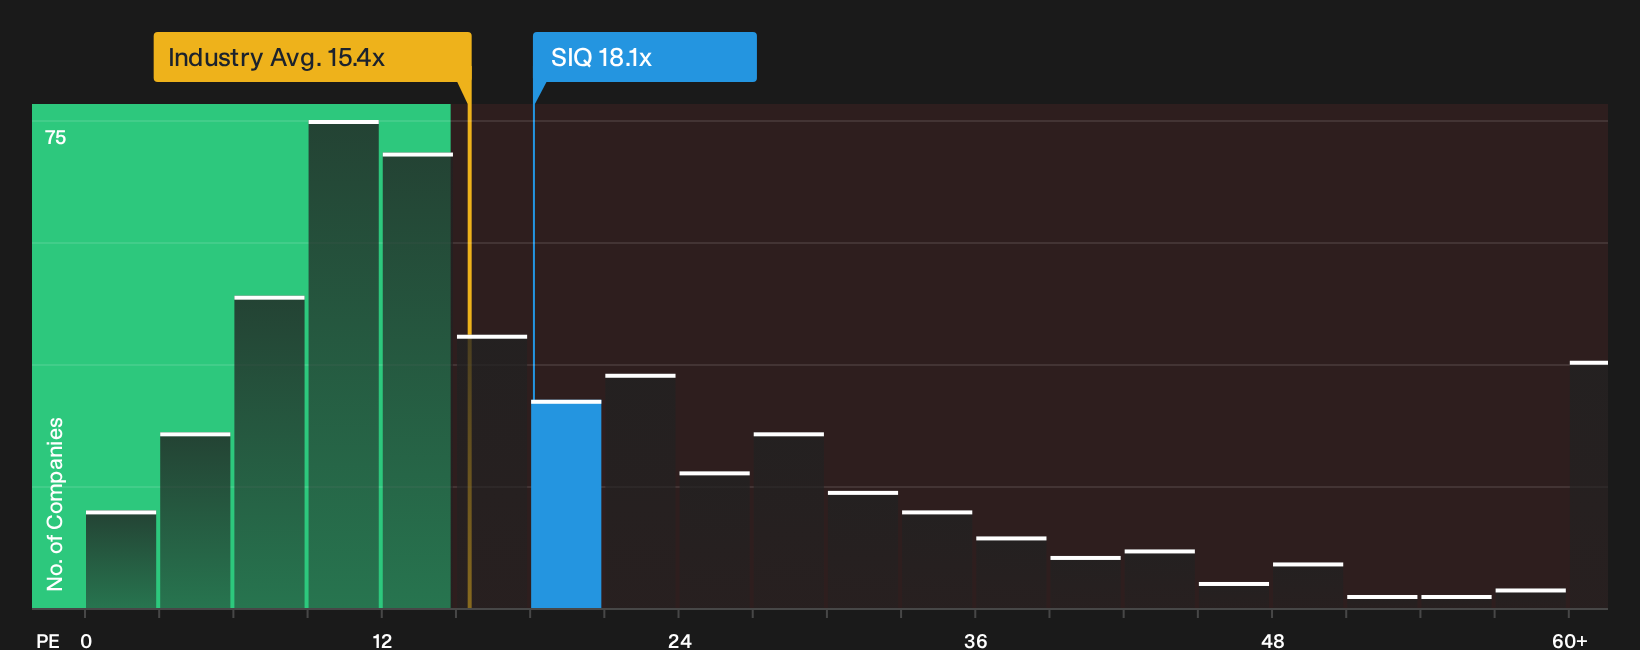
On simple P/E maths, Smartgroup screens as expensive against both global and local Professional Services peers, trading at 18.1x versus about 15.4x to 15.5x elsewhere, even though the fair ratio points closer to 19x. Is the premium a cushion or a crack if expectations slip?
To see how much faith the current multiple really demands from you, and how that compares with peers and the fair ratio the market could move towards, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Smartgroup’s pricing and margins can create noise, so move fast, test the numbers for yourself, then weigh up the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Smartgroup?
If Smartgroup has sharpened your focus on quality, you can use that momentum to hunt for other opportunities that line up with your risk tolerance and return goals.
- Target stability first by reviewing a list of solid balance sheet and fundamentals (12 results) and focus on businesses where balance sheets and fundamentals do more of the heavy lifting for you.
- Chase upside with discipline by scanning a 14 high quality undiscovered gems and spotting under-the-radar candidates before they attract broader attention.
- Dial down portfolio stress by checking a 6 resilient stocks with low risk scores that filters for resilience so sharp drawdowns are less likely to catch you off guard.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com