


EN
Earnings Beat Might Change The Case For Investing In Kennametal Stock
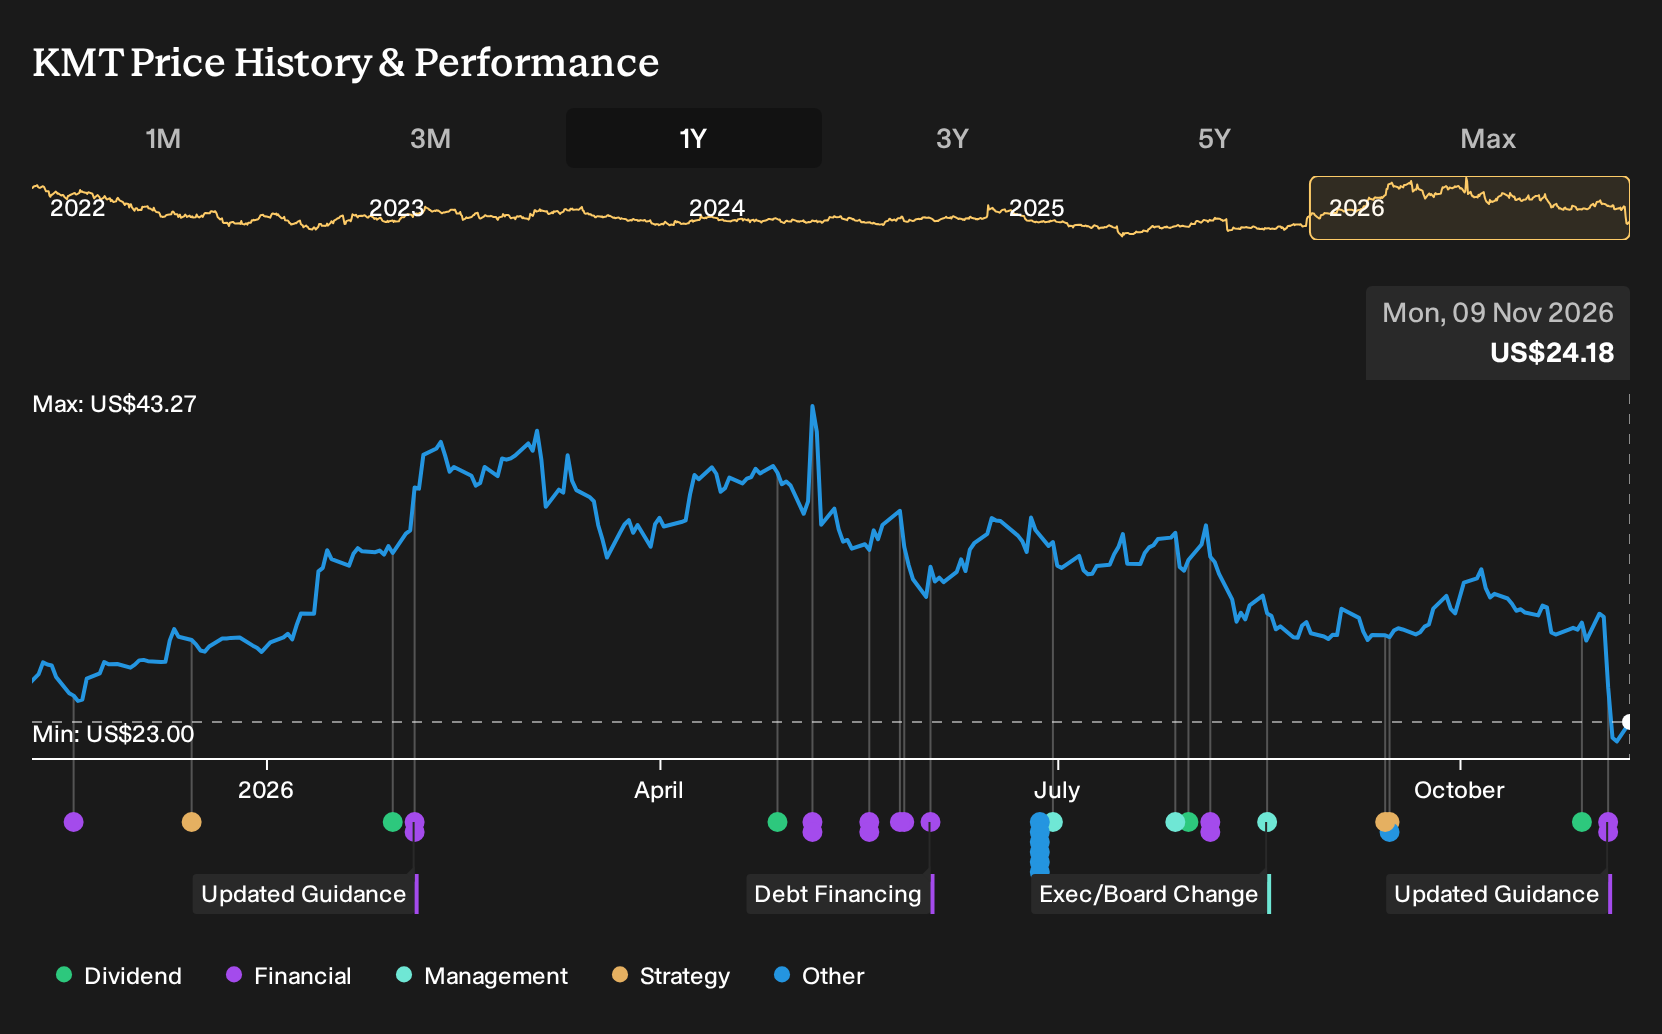
- Kennametal reported first quarter 2027 sales of US$768.19 million and net income of US$271.59 million, with basic EPS from continuing operations of US$3.55. The company also issued second quarter sales guidance of US$785 million to US$815 million, alongside a US$0.20 per share cash dividend declared on October 27, 2026.
- The sharp step up in earnings, together with fresh near term sales guidance, gives investors a clearer read on how Kennametal’s cost actions, product mix and demand across industrial end markets are feeding through to current profitability and near term revenue expectations.
- The focus now shifts to what this stronger Kennametal earnings print and tighter sales outlook could mean for the existing investment narrative.
Scan how Kennametal’s earnings shift compares with peers by reviewing a hand picked 19 high quality undiscovered gems that may be flying under most investors’ radar.
Kennametal Investment Narrative Recap
To own Kennametal, you need to believe the business can turn its cost cuts, tungsten integration and portfolio work into reasonably resilient margins even as raw material timing benefits fade. The analyst consensus Narrative on Simply Wall St leans on that idea. The latest quarterly jump in earnings gives fresh evidence of what the current cost structure and product mix can deliver while demand in core industrial end markets holds up.
The nearer term swing factor is whether that profitability level can be supported if tungsten pricing benefits ease or if end markets such as energy, aerospace and transportation soften. The biggest risk flagged in the existing narrative still applies. A reversal in those sectors or pressure on free cash flow and debt coverage would quickly test how durable this earnings step up really is.
The most relevant update for that debate is Kennametal’s second quarter fiscal 2027 sales guidance of US$785 million to US$815 million, with foreign exchange expected to be neutral. That range gives you a clearer yardstick for how management sees order patterns across metal cutting and infrastructure after the strong first quarter profit. It also ties directly into the volume side of the tungsten and cost saving story.
Guidance now sits against a backdrop where analysts already expect earnings to ease over time as tungsten timing benefits roll off. If actual second quarter sales land toward the upper half of the range and pricing or mix remains firm, it could support the view that cost actions and portfolio shifts are doing some heavy lifting. If results track the low end with softer margins, attention likely swings back to the risks around free cash flow, debt coverage and how quickly high current profitability might compress.
Kennametal's narrative projects US$3.6b revenue and US$273.0 million earnings by 2029. This assumes 15.0% yearly revenue growth and an earnings decrease of US$69.4 million from US$342.4 million today.
Uncover why Kennametal's fair value indicates a 34% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on free cash flow risk. The most bearish Kennametal analysts were working off 13.6% annual revenue growth but a reset to US$175.8 million of earnings by 2029, far below consensus. That pre earnings print stance presents a materially more cautious story that you can compare with other viewpoints.
Explore 2 other Kennametal fair value estimates, including one that suggests it could be worth just $29.98!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own judgment.
- A great starting point for your Kennametal research is our analysis highlighting 4 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Kennametal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kennametal's overall financial health at a glance.
Looking for more Kennametal sized investment ideas?
If Kennametal has sharpened your interest in industrials and beyond, it can be useful to line it up against other opportunities that share similar qualities or offer a different risk profile. The Simply Wall St Screener can help you quickly surface candidates that match the type of portfolio you want to build.
- For investors who care most about quality at a reasonable entry point, consider scanning a 33 high quality undervalued stocks that combine robust fundamentals with what may be discounted share prices.
- If resilience and balance sheet strength sit at the top of your checklist, filter for companies in the list of solid balance sheet and fundamentals (25 results) to see which ones might better handle tougher conditions.
- Those who want income alongside potential capital gains can review a 6 dividend fortresses that pair higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com