


EN
Record Quarter Might Change Sony Stock Narrative After Outlook Raise And Dividend Increase
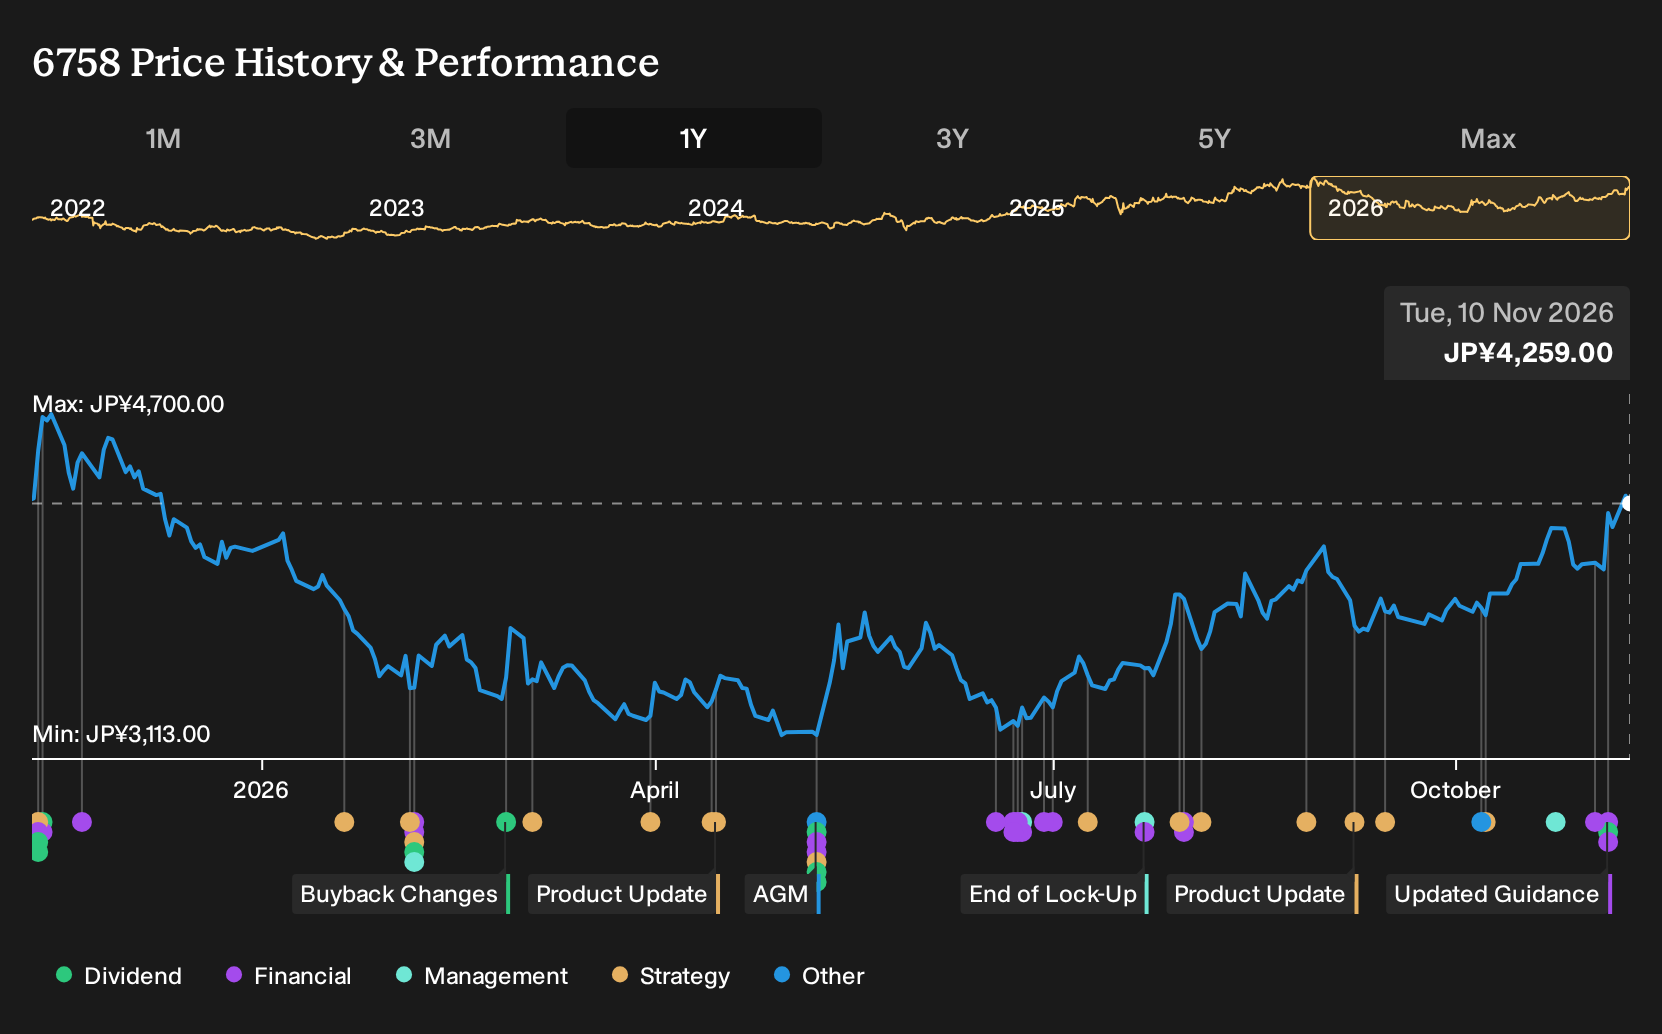
- Sony Group reported second quarter 2026 sales of ¥3,429,446 million and net income of ¥449,603 million, issued full year 2027 earnings guidance, announced a higher interim dividend of ¥17.50 per share, and filed a ¥403.2b ESOP related shelf registration for common stock.
- The combination of record earnings metrics, a dividend uplift versus the prior year, and equity issuance capacity for employee stock plans highlights how Sony Group is using both capital returns and ownership incentives to support its multisegment entertainment, gaming and technology model.
- We will now look at how Sony Group's raised earnings guidance shapes the existing investment narrative around digital services and content.
Scan other entertainment and technology stocks showing similar momentum in earnings, dividends and employee ownership by focusing on the curated 76 high quality undiscovered gems list.
Sony Group Investment Narrative Recap
For you to stay interested in Sony Group, you need to believe the shift toward digital PlayStation services, content IP and image sensors continues to carry more weight than weaker legacy electronics. The analyst consensus Narrative on Simply Wall St leans on that mix improving over time. The latest quarter shows that, at least right now, the operating engine behind that story is working.
The near term catalyst is execution in Game and Network Services, where higher digital engagement can keep supporting earnings. The biggest operational risk remains pressure on hardware heavy areas, especially Entertainment, Technology and Services, if TV and smartphone markets stay soft or component costs stay high.
The fresh full year 2027 guidance, with expected sales of ¥13,000,000 million and net income of ¥1,330,000 million, is the announcement that ties closest to this story. It connects directly to the idea that Sony Group can lean on gaming, music, pictures and image sensors to support profitability while it reshapes weaker lines.
For you as an investor, that outlook becomes a simple execution test. Management now has a public earnings yardstick, while headwinds such as geopolitical driven input costs and potential legal costs around digital ownership and AI related music cases sit in the background and could pressure those targets if they escalate.
Sony Group's narrative projects ¥13,805.5b in revenue and ¥1,454.9b in earnings by 2029, assuming 2.8% yearly revenue growth and an earnings increase of about ¥340.9b from ¥1,114.0b today.
Uncover why Sony Group's fair value indicates a 14% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
Some of the most optimistic analysts frame Sony Group’s dividend hike and higher guidance as early confirmation of a stronger long term content engine. Before this news, they were already pencilling in revenue of about ¥14,991.7b and earnings of roughly ¥1,698.4b by 2029. You can treat those upbeat forecasts as just one viewpoint and compare them with more cautious scenarios that might evolve as fresh information lands.
Explore 2 other Sony Group fair value estimates, including one that suggests as much as 17% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Sony Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Sony Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sony Group's overall financial health at a glance.
Looking for more investment ideas beyond Sony Group?
Once you have formed a view on Sony Group, it can help to set it alongside a wider watchlist of companies with different risk and income profiles.
- If you want steadier candidates that score well on financial resilience, start with the list of solid balance sheet and fundamentals (23 results) and see which businesses match that brief.
- For readers who care most about capital preservation and controlled volatility, filter through the 18 resilient stocks with low risk scores and compare those profiles to Sony Group's risk drivers.
- When you are ready to broaden the opportunity set beyond well known stocks, scan the 1 elite penny stocks with strong financials and see which smaller companies still meet your quality and fundamentals checklist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com