


EN
Is Avista (AVA) Undervalued On Stronger Third Quarter Earnings?
Why Avista’s latest earnings matter for shareholders
Avista (AVA) just released third quarter and nine month results that put profitability in sharper focus for investors, with net income and earnings per share both higher than the prior year period.
That profitability story is already feeding into the tape. Avista’s 12.88% 1 month share price return and 39.91% 3 year total shareholder return point to momentum that has been building rather than fading, even as the stock eased 0.42% over the last day.
Scan beyond Avista and compare this earnings momentum with a hand-picked set of utilities and infrastructure players that have been screened for resilient profitability using the 30 resilient stocks with low risk scores.
Avista has already rewarded patience with a 3 year total return near 40%, yet the latest earnings beat and recent 1 month jump of almost 13% raise a sharper question: Is most of the upside already in the rear view mirror, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 3% Undervalued
Avista closed at $40.06, while the analyst consensus Narrative on Simply Wall St points to a fair value near $41.33, which implies a modest discount when using a 7.24% discount rate and analyst earnings and revenue forecasts.
The multiyear capital investment plan for Avista Utilities has been updated from approaching US$3b in 2025 to 2029 to US$3.4b in 2026 to 2030, with additional potential US$350m of incremental investment tied to large-load connections and regional transmission needs, which can increase regulated rate base and support earnings growth if executed within allowed returns. The shift toward longer general rate plans in Washington and implementation of mechanisms such as deferrals for specific cost categories, combined with a higher long-term utility return on equity expectation of about 9%, points to a regulatory model that can reduce lag and support more stable net margins and earnings for Avista.
See why 7 investors see Avista as 3% undervalued.
Result: Fair Value of $41.33 (UNDERVALUED)
Still, Avista’s wildfire exposure and the funding needs of its US$3.4b capital plan could pressure returns if costs, financing or the timing of recovery disappoint.
Find out about the key risks to this Avista narrative.
Another View on Avista’s Valuation
There is a different signal coming from the SWS DCF model. On this approach, Avista at $40.06 trades above an estimated future cash flow value of $36.21, which frames the stock as overvalued rather than 3% undervalued. That gap raises a simple question: Which lens do you trust more, earnings multiples or cash flows?
For readers who want to see exactly how this cash flow view is built, walk through the full calculation with the Look into how the SWS DCF model arrives at its fair value..
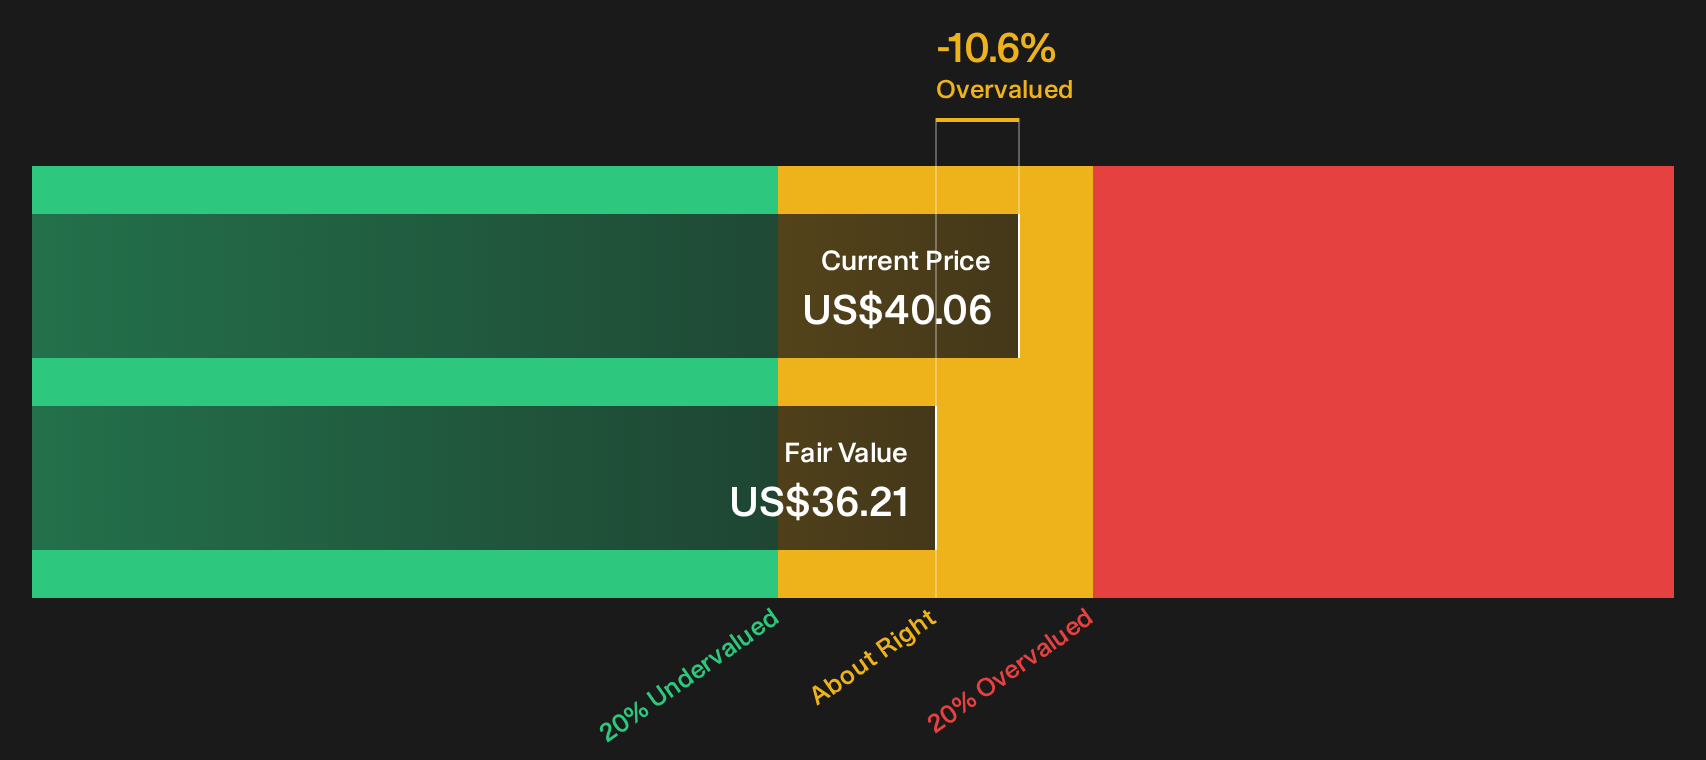
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Avista for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the data or a clear opportunity taking shape? Put the recent price swing and valuation gap in context by weighing both the upside potential and the flagged concerns through the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Avista?
You have already done the hard work by digging into Avista, so consider comparing it with additional ideas that could help inform your next move.
- Explore a 30 resilient stocks with low risk scores that filters for businesses with profiles designed to be more resilient when conditions become more challenging.
- Review a 33 high quality undervalued stocks that highlights companies combining stronger fundamentals with prices that may not fully reflect them.
- Assess a 6 dividend fortresses focused on higher yields and balance sheets that may support those payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com