


EN
AAR Stock Gains Airbus Repair Role Across Asia Pacific
- AAR CORP. recently agreed a multi year radome repair contract with Airbus Avionics that makes AAR an Airbus approved radome repair station for commercial aircraft across Asia Pacific, excluding China. This complements its existing work on Airbus structures like sharklets, elevators, rudders and slats.
- This Airbus Avionics deal gives AAR CORP. recurring repair work tied directly to Airbus fleets in a wide region. It can support higher utilization of existing repair infrastructure and deepen integration with airline maintenance programs that rely on consistent turnaround times for critical components.
- The focus now shifts to how this expanded Airbus radome repair role might influence AAR CORP.'s broader investment narrative.
AAR Investment Narrative Recap
To own AAR, you need to believe the integrated parts, repair, and software platform can continue pulling more high value work across commercial and government customers, while margins in Repair, Engineering and Software recover from recent pressure. The Airbus radome agreement fits that view by tying AAR more closely to large installed fleets, without changing the overall thesis.
The key near term swing factor still appears to be execution on MRO integration and cash conversion, as highlighted in the analyst consensus Narrative on Simply Wall St. The biggest risk remains taking on more leverage and then seeing margins or free cash flow conversion stall, rather than this incremental Airbus work materially shifting near term outcomes.
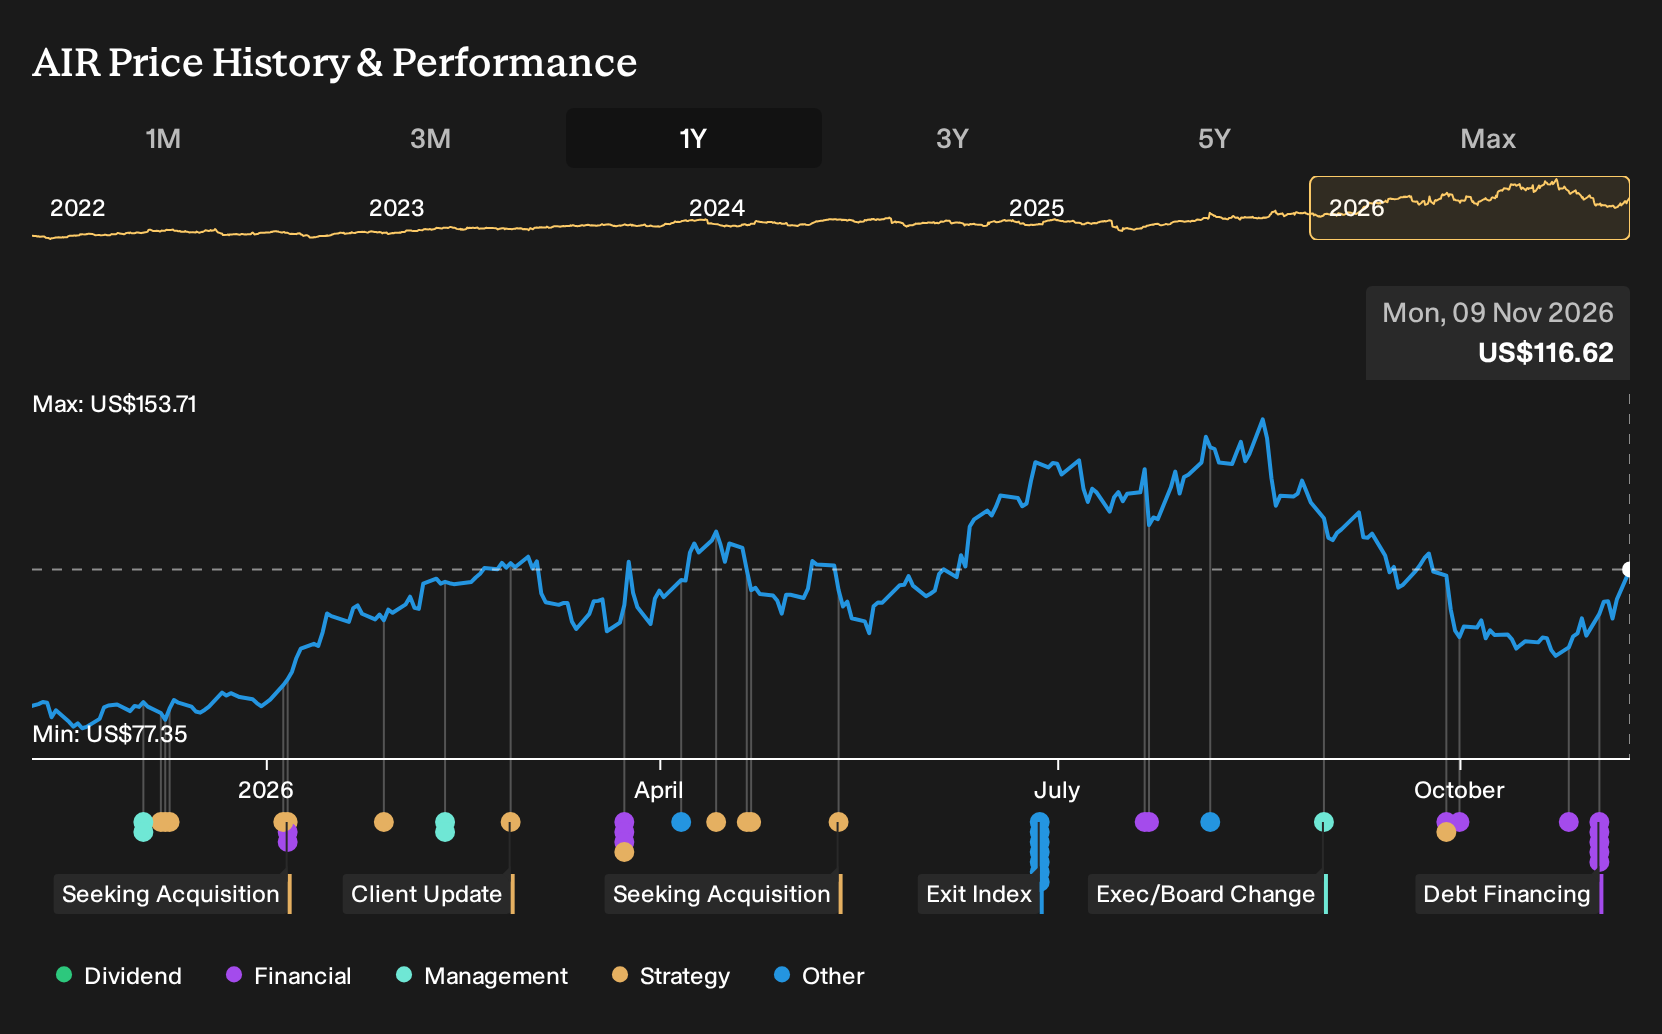
The fixed income offerings announced on 2 November 2026 matter more for the immediate AAR story than the Airbus contract alone. AAR completed US$955 million of 7.125% senior notes due 2031 and US$960 million of 7.375% senior notes due 2034, both issued at 100% of principal with guarantees attached.
That debt package ties directly into the planned 65% acquisition of MRO Holdings, alongside roughly US$1.0 billion of equity and an agreed US$780.8 million equity component. For investors, the key points to monitor are leverage, interest cost, and whether the additional MRO capacity and the stated US$285 million of EBITDA and US$200 million of operating cash flow materialize in line with the catalysts outlined for the wider platform.
AAR's outlook indicates projected revenue of US$4.3b and earnings of US$305.7 million by 2029. This reflects analysts' expectations for revenue growth of 7.2% per year and an increase in earnings of about US$112 million from US$193.4 million today.
Uncover why AAR's fair value indicates a 32% potential upside to its current price as investors reassess AAR's expanded MRO and Airbus repair story.
Exploring Other Perspectives
The Simply Wall St Community currently shows 2 fair value estimates for AAR CORP. that span a wide band from about US$77.62 to US$154.50 per share. Those private investors clearly do not agree, which matters when you weigh acquisition related leverage, integration risk at MRO Holdings, and how that could influence future valuation.
Explore another AAR fair value estimate, including one that suggests there could be up to 32% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your AAR research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AAR. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AAR's overall financial health at a glance.
Looking For More Investment Ideas Beyond AAR?
Once you have formed a view on AAR, it can help to compare that thesis against other opportunities using the Simply Wall St Screener. That way you can see how AAR stacks up against businesses with different balance sheets, income profiles, and risk levels.
- If capital preservation sits high on your list, you may want to scan a set of resilient companies with lower risk profiles through the 30 resilient stocks with low risk scores.
- If you prefer strong finances and cleaner balance sheets, you could compare AAR against a list of solid balance sheet and fundamentals (25 results) so you can focus on companies with fewer financial weak spots.
- If you are hunting for underfollowed ideas with solid fundamentals, you might widen your research with a 19 high quality undiscovered gems that are not yet widely tracked.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com