


EN
TG Therapeutics (TGTX) Stock May Still Look Reasonable On Earnings
TG Therapeutics has delivered a very strong share-price run in recent years, which puts fresh attention on whether the current valuation is supported by its earnings power. With the stock now in a very different place to where it was a few years ago, the key issue for you is what those earnings actually justify.
- Over the past 3 years, the share price has produced a gain of more than 7x, so any view on TG Therapeutics now rests heavily on how sustainable its profit engine can be.
- The business model is heavily tied to commercialising a focused portfolio of therapies, which can shape future earnings through pricing power, market share and the cost of ongoing research spending.
- Your read on TG Therapeutics is one view; the desks covering it have another. See what analysts think TG Therapeutics's shares could be worth.
The stock's next move may depend on whether TG Therapeutics' current price can be squared with the earnings it is generating today and is realistically positioned to produce in the future.
If you want a second reference point while you assess whether TG Therapeutics' earnings back up its recent run, compare it with the stocks in 33 high quality undervalued stocks as another starting universe for research.
Is TG Therapeutics Still Cheap on Earnings?
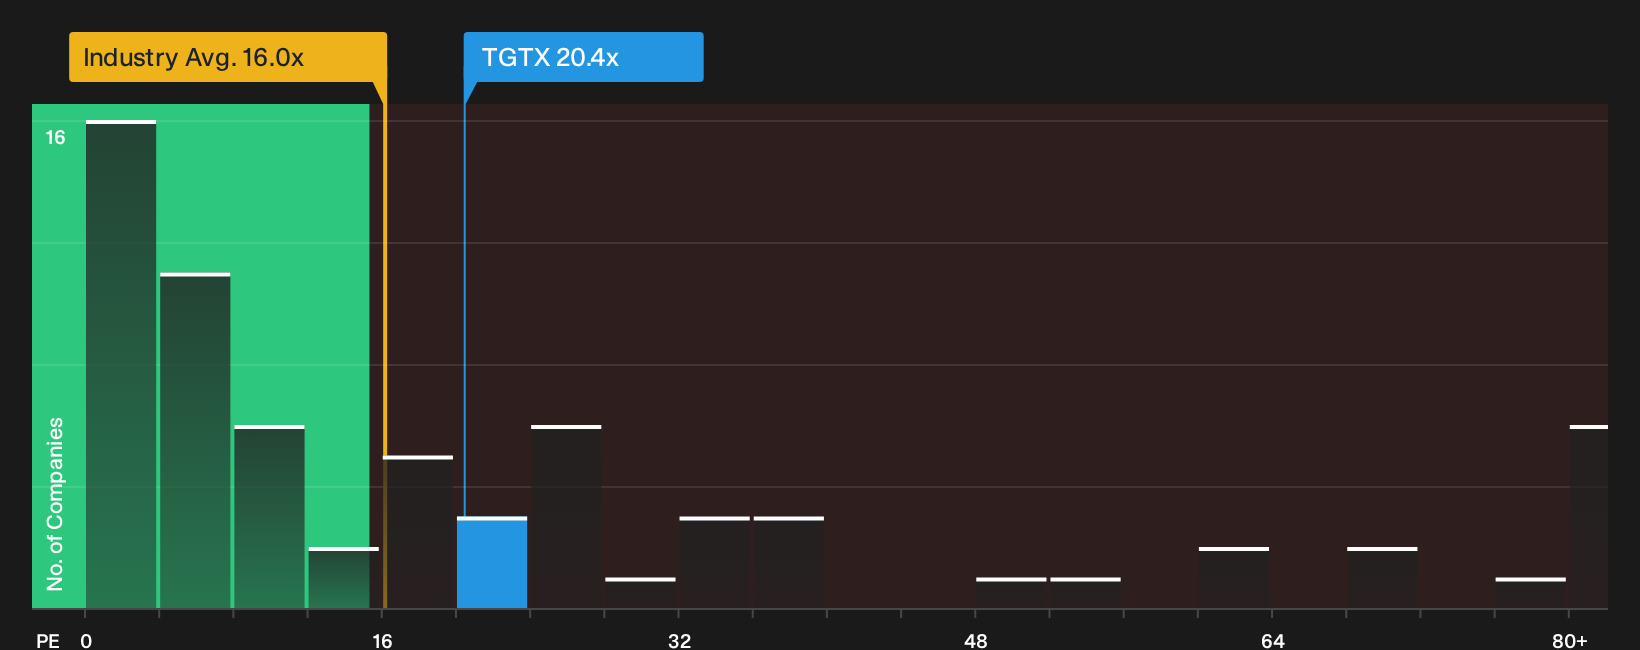
The P/E ratio is a useful way to look at TG Therapeutics because earnings are now a key driver of how investors view the company. The stock trades at a P/E of roughly 20.4x, which is above the broader biotech sector average of about 16.0x but well below the peer group, which is closer to 51.9x. That positioning suggests that the market is giving the business some credit for its current profit profile without valuing it in line with the higher-multiple companies in the space.
The fair multiple implied by the valuation work is higher than where TG Therapeutics trades now, so the current P/E sits at a discount to what the model would expect once growth prospects, margins, size and risk are all considered. For you as a shareholder or potential buyer, the key issue is whether those fundamentals are strong enough to support the gap between the current P/E and that tailored yardstick. Explore the numbers behind TG Therapeutics's P/E valuation.
The TG Therapeutics Narrative: What Would Justify Today's Price?
Narratives on TG Therapeutics pick up where the valuation question leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the current share price to look meaningfully higher or lower over time. They are housed on Simply Wall St's Community page. Each one is framed as a thesis about TG Therapeutics' fair value that can be tracked as new information arrives, rather than a one off snapshot.
Views on TG Therapeutics split between BRIUMVI turning into a broader autoimmune franchise and worries that costs and governance risks cap what shareholders get paid.
Bull case: 9% undervalued
The analyst consensus Narrative on Simply Wall St frames the optimistic view on TG Therapeutics.
"The shift of BRIUMVI from a single intravenous multiple sclerosis treatment to a broader autoimmune franchise, including new indications such as myasthenia gravis and treatment resistant schizophrenia..."
Discover why this Narrative puts TG Therapeutics at 9% undervalued.
Bear case: 120% overvalued
The bearish analyst Narrative on Simply Wall St highlights the more cautious take.
"Although TG Therapeutics reports high gross margins on BRIUMVI and growing operating income, the recent earnings miss where diluted EPS of $0.05 fell well short of expectations..."
Explore why this Narrative puts TG Therapeutics at 120% overvalued.
One more angle on TG Therapeutics that earnings alone will not show you
Price and current profits tell only part of the story for TG Therapeutics, since professional models already sketch where they think this business lands a few years from now and that extra reference point is worth checking. Explore where analysts expect TG Therapeutics to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com