


EN
Earnings Beat Might Change The Case For Monolithic Power Systems Stock
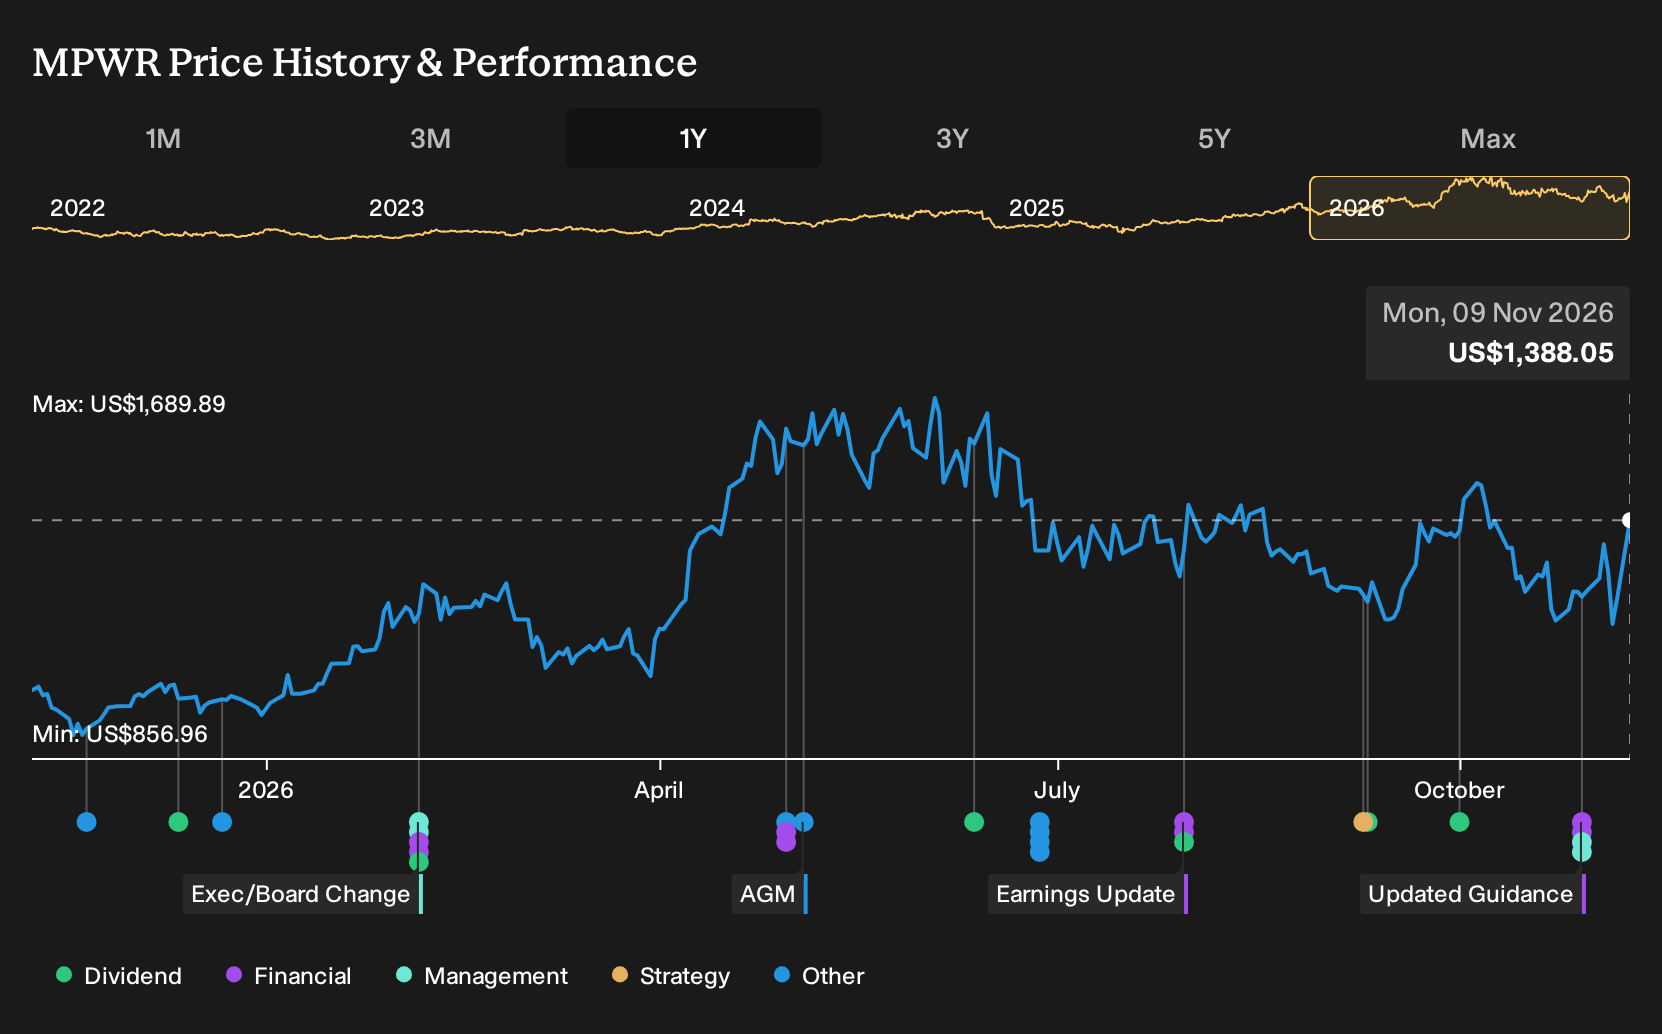
- Monolithic Power Systems reported third quarter 2026 sales of US$1,202.41 million and net income of US$271.07 million, issued fourth quarter revenue guidance of US$1,315 million to US$1,385 million, completed a US$464.52 million buyback tranche, and confirmed new finance leadership appointments.
- The combination of strong reported earnings, fresh revenue guidance and ongoing capital returns through buybacks gives investors a clearer picture of how Monolithic Power Systems is funding capacity, rewarding shareholders and reshaping its finance bench at the same time.
- We will now look at how Monolithic Power Systems' reported earnings and revenue guidance interact with its existing investment narrative.
Scan how Monolithic Power Systems stacks up against other power and AI infrastructure plays by reviewing our curated list of 53 AI infrastructure stocks in one place.
Monolithic Power Systems Investment Narrative Recap
To stay on board with Monolithic Power Systems, you need to believe the heavy investment in power solutions for AI data centers and autos can be supported by real demand that keeps new capacity busy. The analyst consensus Narrative on Simply Wall St centers on that execution question. The latest Q3 results and Q4 revenue guide provide more current data on how that capacity is being used in the near term.
The main short term swing factor is how quickly AI related and automotive orders absorb the extended manufacturing footprint, given free cash flow is already feeling that build out. Key risks remain the outstanding investigations about quality and customer order disclosures, which could weigh on future design wins and margins if outcomes or customer relationships move against Monolithic Power Systems.
The clearest actionable update here is the Q4 2026 revenue outlook of US$1,315 million to US$1,385 million. That range helps you benchmark whether the capacity plan that extends beyond US$6b in annual revenue equivalents is tracking in line with the growth expectations described in the analyst consensus Narrative on Simply Wall St, or whether utilisation might lag those assumptions.
The same guidance also feeds directly into the current catalyst list around AI data center exposure, automotive socket ramps and the Singapore manufacturing partnership that is scheduled to target volume in early 2027. If reported revenue stays within or close to the guided band while free cash flow remains under pressure from expansion, execution risk around filling that larger footprint remains a central issue for anyone considering Monolithic Power Systems.
Monolithic Power Systems' current earnings sit at US$801.9 million, with analyst forecasts pointing to US$2.1b of earnings and US$6.9b of revenue by 2029. That outlook implies revenue growth of 28.3% per year and an earnings increase of about US$1.3b from earnings today to the 2029 consensus figure.
Uncover why Monolithic Power Systems' fair value signals a 30% potential upside to its current price that could narrow quickly as expectations reset.
Exploring Other Perspectives
One alternate view leans heavily on Monolithic Power Systems’ capacity plan itself as the big upside catalyst. The most optimistic analysts were pencilling in about US$10.4b of revenue and US$2.4b of earnings by 2029 before this Q3 print and new Q4 guide. That camp sees the buyback and fresh leadership hires as fuel for a much bigger AI and data center business. You can treat today’s guidance and CFO change as a live test of whether that upbeat story still holds or needs a reset, and it is worth comparing several narratives before you decide where you land.
Explore 4 other Monolithic Power Systems fair value estimates, including one that suggests as much as 51% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Monolithic Power Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Monolithic Power Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monolithic Power Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Monolithic Power Systems?
If you want to stress test your view on Monolithic Power Systems, the simplest move is to line it up against other listed businesses that fit different risk and return profiles. The Simply Wall St Screener can help you scan across sectors and capital structures so you can see where this stock sits in the broader opportunity set.
- If capital preservation is your priority, consider stocks that show resilient fundamentals and historically lower risk profiles by screening for 30 resilient stocks with low risk scores.
- If you are hunting for mispriced quality, compare Monolithic Power Systems against companies that appear attractively valued on both cash flows and balance sheet strength through a focused set of 33 high quality undervalued stocks.
- If you want to widen the field beyond well known tickers, broaden your watchlist with a curated pool of 19 high quality undiscovered gems that combine solid financial traits with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com