


EN
Agree Realty (ADC) Stock Looks About Right After A 42% Run
Agree Realty has delivered a 3 year share price gain that many income focused investors would be happy to pocket. The real question now is whether that move still lines up with what its earnings can support. With the stock recently closing at US$70.20 and investors focused on its payout profile, the issue is how much of its earnings story is already reflected in that price.
- The 42.5% share price return over the past 3 years puts real weight behind the question of how fully Agree Realty's earnings power is being valued today.
- Recent commentary that Agree Realty is prioritising balance sheet liquidity while selectively adding retail properties, supported by an investment grade tenant mix, can shape how dependable and repeatable its future earnings stream may look.
- Your read on Agree Realty is one view; the desks covering it have another. See what analysts think Agree Realty's shares could be worth.
The stock's next move may depend on whether Agree Realty's current valuation can be explained by its earnings profile alone.
If you want to pressure test Agree Realty's valuation debate against a wider group of income ideas, compare it to 6 dividend fortresses.
Where Does Agree Realty Sit on Earnings?
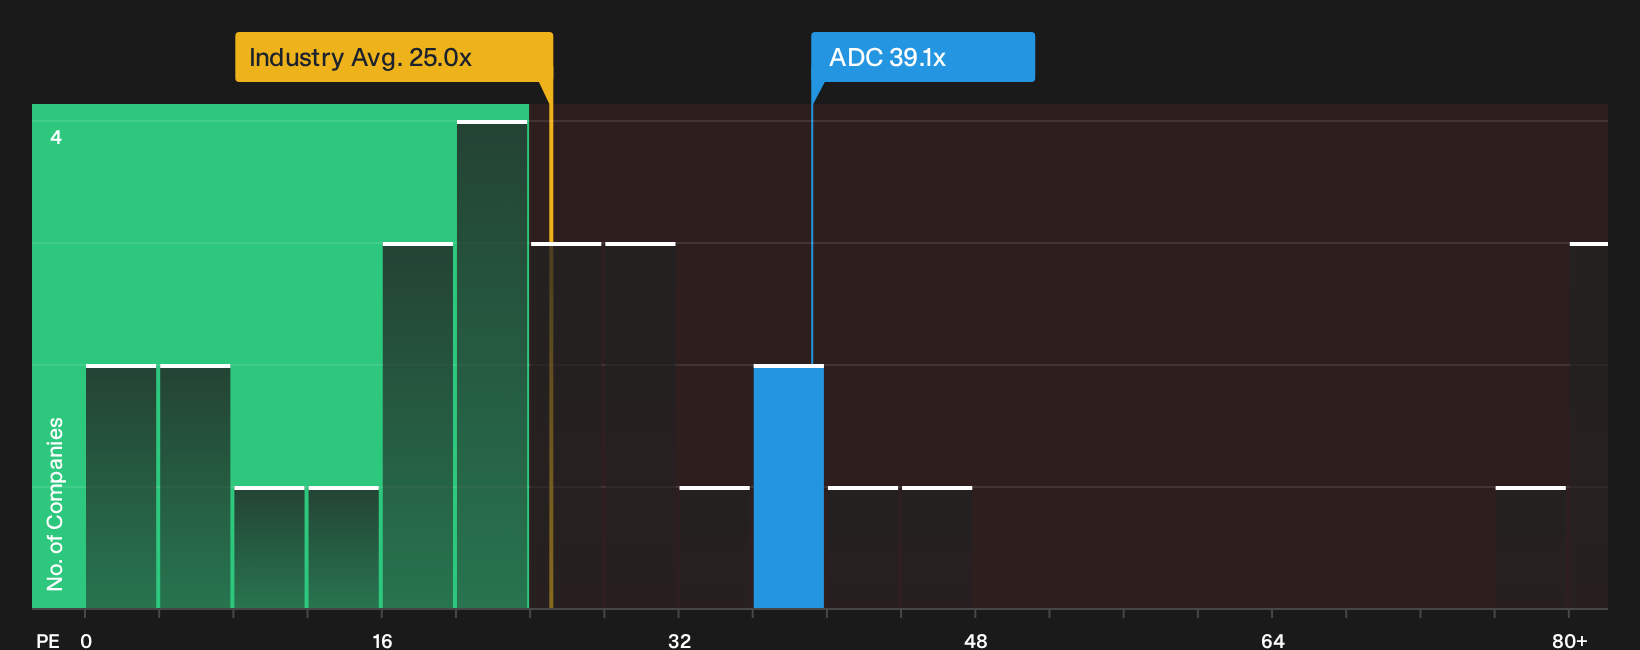
The P/E ratio makes sense for Agree Realty because income focused investors often anchor decisions on what they are paying for each dollar of earnings. At roughly 39.1x earnings, the stock trades at a premium to both the Retail REITs industry average of about 25.0x and the peer group near 23.0x. That points to investors placing a higher value on this REIT's earnings stream than on many similar landlords.
Based on a tailored fair P/E estimate that factors in Agree Realty's economics, the current multiple sits slightly above where the model would expect it to trade, which leans toward the stock being about right rather than clearly overvalued or undervalued. Because management recently raised guidance for future AFFO, the richer P/E can also reflect confidence that the current earnings base has support from the existing property and tenant mix. If you want to see how that model derived its fair P/E and how big the gap is, compare Agree Realty to a wider set of income stocks using. Explore the numbers behind Agree Realty's P/E valuation.
The Agree Realty Narrative: What Would Justify Today's Price?
Narratives pick up where Agree Realty's valuation puzzle leaves off. They spell out which assumptions on growth, profitability and earnings power would need to hold for the stock to look meaningfully higher or lower than today. Each one treats fair value as a hypothesis about Agree Realty's business that you can revisit over time, rather than a single frozen snapshot. They are available on Simply Wall St's Community page for you to track.
One of the top narratives on Agree Realty: 10% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation implies that Agree Realty’s share price does not fully reflect the company’s raised investment and AFFO per share guidance, its recurring dividend growth and the free cash flow remaining after dividends..."
Discover why this Narrative puts Agree Realty at 10% undervalued.
Agree Realty’s valuation still leaves one crucial thread hanging
The next thing to weigh is who is actually steering Agree Realty and how their pay packets line up with your interests, because that relationship can shape how every future decision gets made. See who runs Agree Realty and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com