


EN
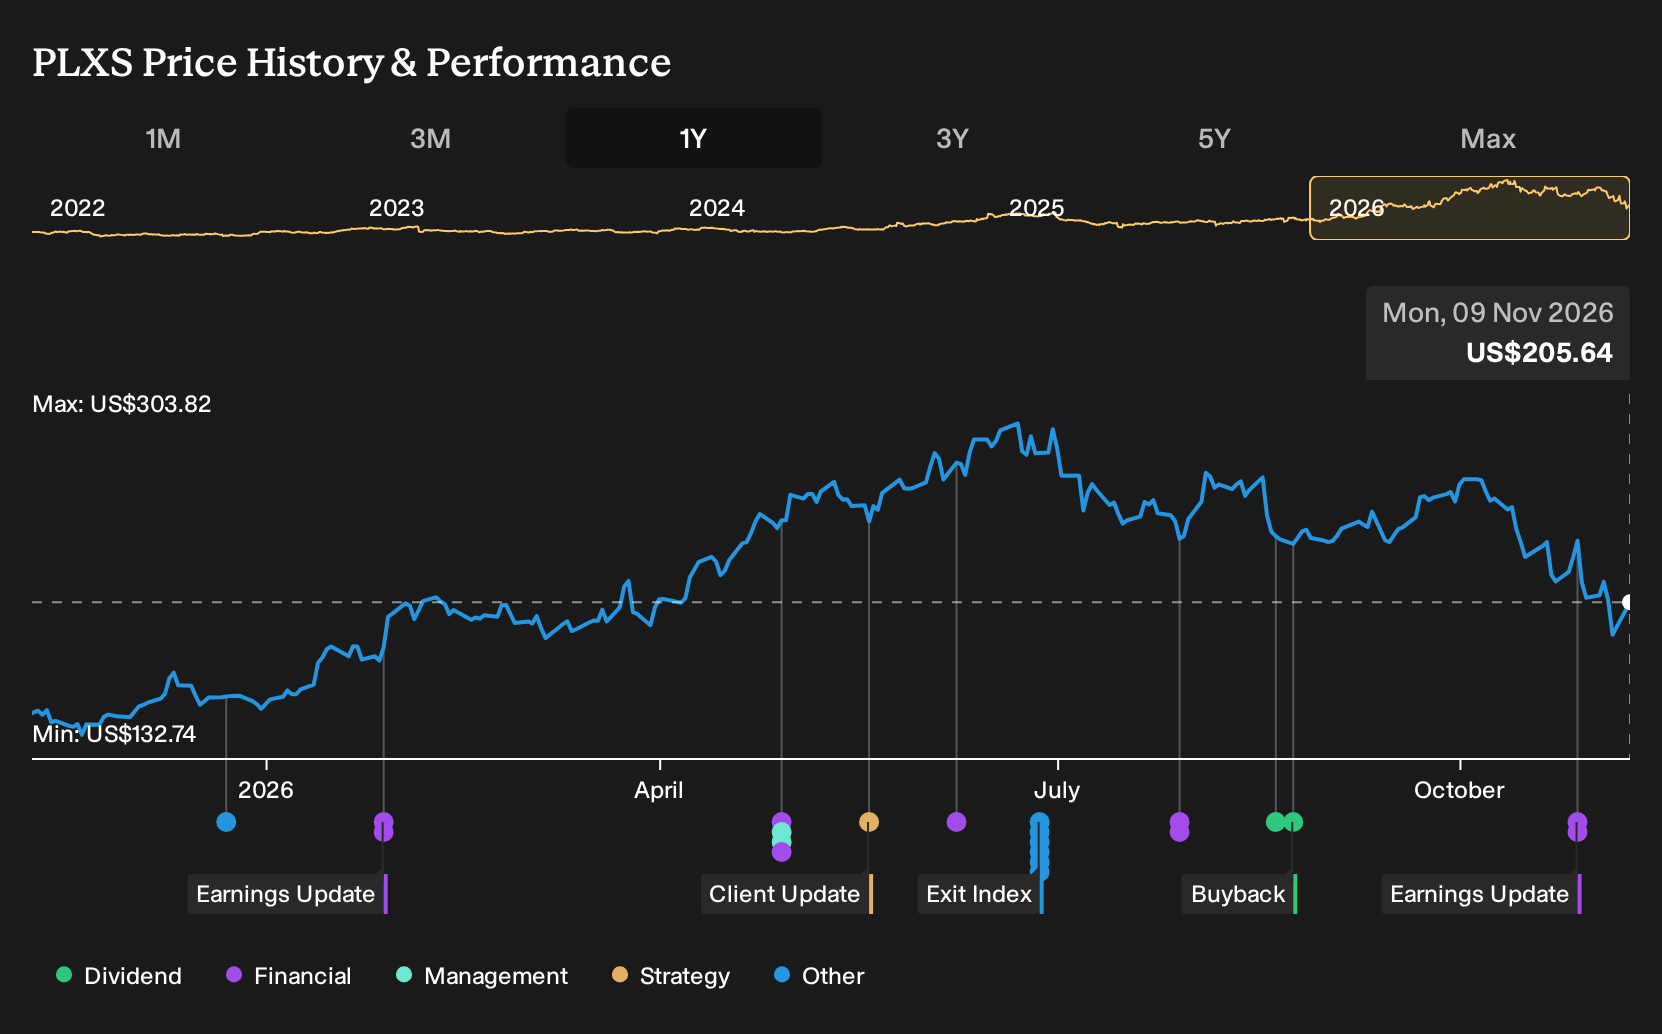
Why Plexus Stock Is Up 7.0% And What's Next After Strong Earnings
- Plexus reported fourth quarter 2026 sales of US$1,426.57m and net income of US$68.51m, with full year revenue of US$4,964.96m and net income of US$202.49m, alongside detailed guidance for early fiscal 2027.
- The electronics manufacturer also completed a US$100m buyback from a May 2025 program, retiring 2.01% of shares while maintaining its focus on high complexity and regulated end markets.
- The following section examines how Plexus's investment narrative is influenced by these reported earnings and updated forward guidance.
Plexus Investment Narrative Recap
Plexus appeals to shareholders who buy into a long run story of complex, regulated electronics work that can support consistent earnings and solid cash conversion. The analyst consensus Narrative on Simply Wall St assumes that converting the qualified manufacturing funnel into programs, while holding margins and the cash cycle, is the key pillar. The latest quarter shows that Plexus is still operating at a scale where that thesis matters.
In the near term, the main catalyst is execution against the early fiscal 2027 guidance on revenue, operating margin and diluted EPS. Over the short term, the biggest risk is any demand softening or shift in customer mix that pressures that 5.5% to 5.9% operating margin range or stretches working capital, especially with expectations already framed around record activity levels.
The most relevant fresh data point for that catalyst is Plexus' own guidance for the first quarter of 2027, with revenue projected between US$1.410b and US$1.460b and operating margin again guided at 5.5% to 5.9%. Diluted EPS is guided to US$2.16 to US$2.32, which keeps attention squarely on how efficiently the business can run its existing footprint.
For you as an investor, that forecast sets a concrete execution bar. Delivery in line with those ranges would support the view that Plexus can keep converting its US$4.5b qualified funnel while maintaining disciplined profitability and cash cycle performance. Any shortfall tied to project timing, sector demand or mix would quickly test confidence in the stronger earnings growth profile that analysts currently expect.
Plexus' narrative projects US$6.8b revenue and US$335.8m earnings by 2029. This assumes 14.0% yearly revenue growth and an earnings increase of about US$150m from current earnings of US$185.4m.
Uncover why Plexus' fair value points to a 48% potential upside to its current price that could narrow quickly if execution stays on track.
Exploring Other Perspectives
Some of the lowest Plexus forecasts tell a very different story, with revenue modeled at roughly US$6.5b and earnings of US$315.2m by 2029. Those analysts worry more about potential slowdowns in semicap, as well as in aerospace and defense. You can use this cautious view as a counterweight and consider how this fresh earnings news might influence it.
Explore another Plexus fair value estimate, including one that suggests as much as 25% downside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Plexus research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Plexus. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Plexus' overall financial health at a glance.
Looking for more investment ideas beyond Plexus?
Once you have a view on Plexus, it can help to compare that thesis with other opportunities that share similar quality traits or risk profiles. The Simply Wall St Screener lets you filter for exactly the type of businesses you want to research next.
- If capital protection is your priority, start with resilient candidates by scanning 30 resilient stocks with low risk scores that aim to keep downside risk in check.
- If you care most about financial strength, widen your watchlist using a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without stretching the balance sheet.
- If you are hunting for mispriced quality, focus your next round of research on a 33 high quality undervalued stocks that combine strong fundamentals with potentially appealing valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com