


EN
Did Subsea 7's 79% Run Pass You By? What The Bulls Got Right
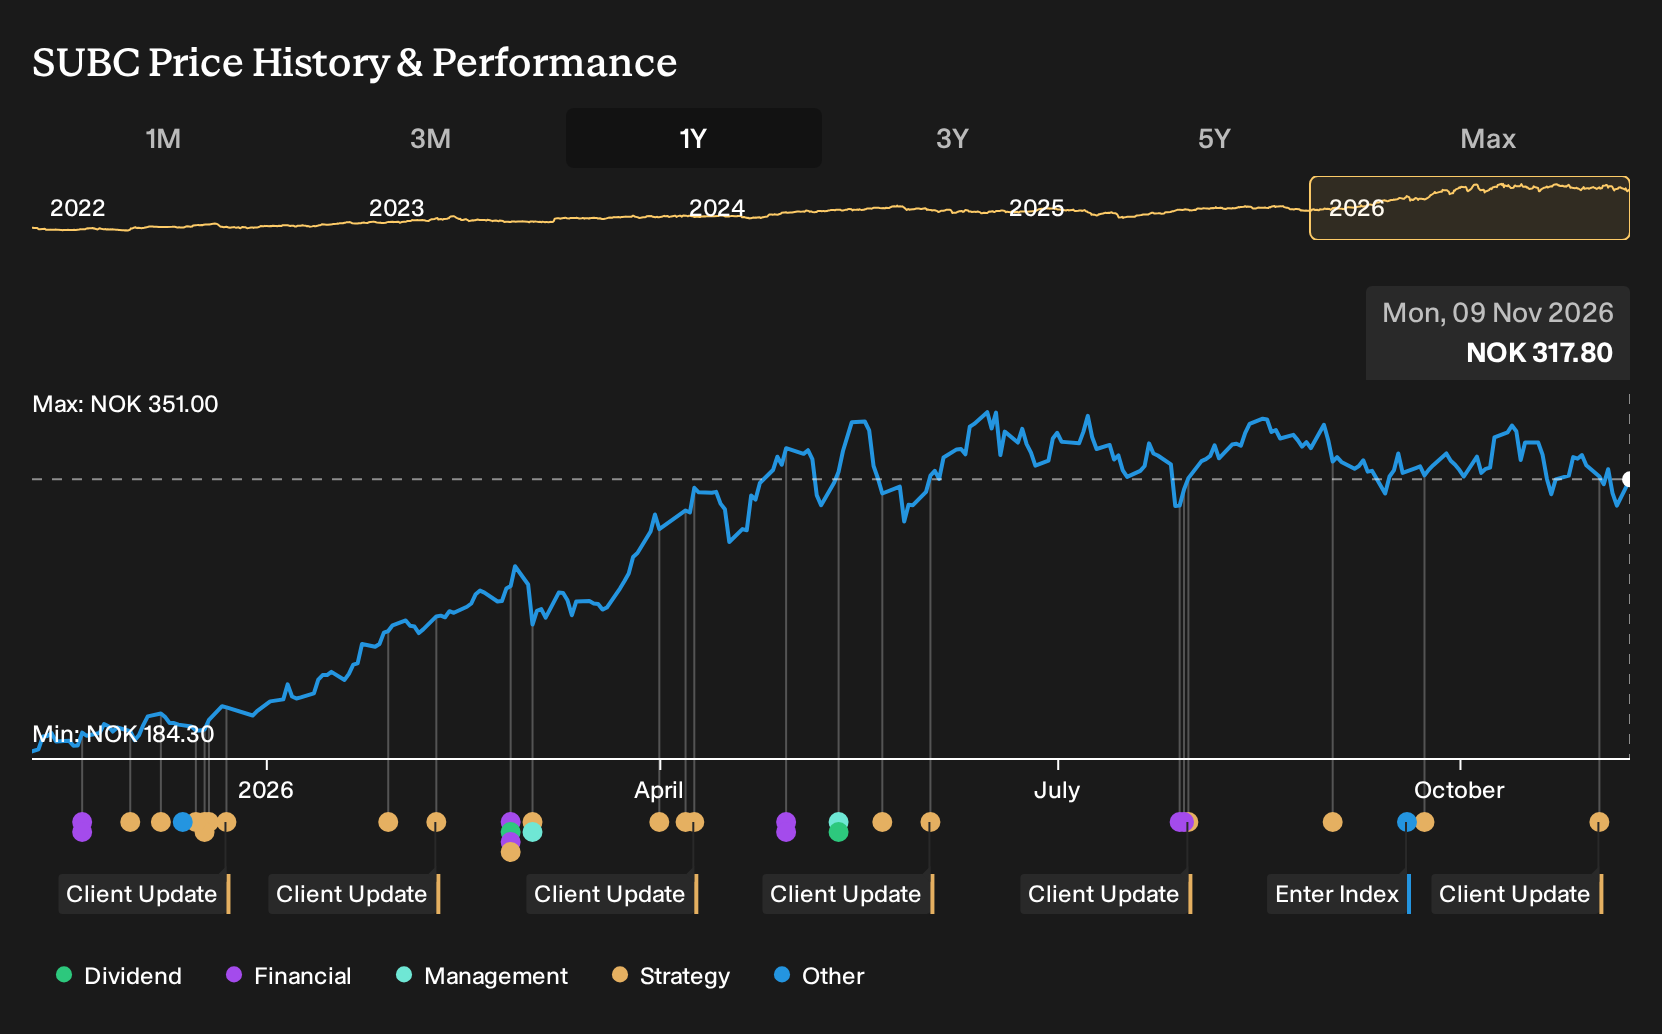
If you only skimmed the headlines about decarbonization pressure on offshore oil and gas, Subsea 7 might have looked like a stock to avoid. Holding Subsea 7 over the past year would have returned 79.2%, including dividends. If you had bought on 9 November 2025, you would have done so with analysts split between a bullish fair value well above the screen price and a bearish view below it. What did that standoff miss about the business drivers investors were actually paying for?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond Subsea 7. See which of 42 power grid technology and infrastructure stocks may still merit a closer look.
The Two Subsea 7 Stories Investors Were Weighing
The shares cost NOK182 at the start of the period, and anyone looking at Subsea 7 then had to decide which of two very different stories felt more convincing.
The bullish narrative in July 2025 put Fair Value at NOK268, 47% above the start price. It leaned on deep revenue visibility, an expanding backlog and the idea that integrated engineering on alliances such as the BP partnership could support higher and more resilient margins.
The bearish view from the same month set Fair Value at NOK159, 13% below the start price. That case focused on accelerating decarbonization, rising ESG pressure, and the risk that long term capital for offshore oil and gas projects could shrink, leaving Subsea 7 with overcapacity and thinner margins.
What The Evidence Around Subsea 7 Actually Tested
Subsea 7’s Q2 2026 update showed revenue rising to US$1,927.4 million and net income climbing to US$253.9 million, with net margin moving from 7.6% to 13.2%. That shift, plus news of strong Q1 and H1 2026 EBITDA and a US$13.6b backlog, leaned toward the optimistic backlog and margin story. The merger scrutiny in Europe and required Brazilian divestment kept the cautious case alive, so the evidence cut both ways.
The key lesson is to test any backlog driven thesis against three numbers. Track future guidance, actual net margin, and the size and quality of contracted work reported after the decision date.
What Today's Subsea 7 Price Already Assumes
Subsea 7 now trades at NOK318, after a 79.2% gain over the past year from NOK182. The bearish analyst Narrative on Simply Wall St places its Fair Value below that level, so it views the recent climb as baking in demanding terms on future work and cash generation.
A buyer today is effectively assuming Subsea 7 will keep converting its tendering pipeline and alliances into profitable backlog on similar terms. The question is how that stacks up against the Narrative’s focus on tender conversion risk, offshore wind lulls and working capital drag.
"The main thing that has to go right is that Subsea 7 converts its large subsea tendering pipeline, long term alliances and current high margin backlog into future work at similar terms, despite offshore wind sanctioning lulls, working capital unwinds and ongoing merger scrutiny."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 22% below our estimate - focuses on secured mortgages, gold and agri loans while improving productivity.
- Company 2 - 39% below our estimate - uses AI tools and tighter carrier vetting to reduce fraud and claims expenses.
- Company 3 - 28% below our estimate - extends digital finance and inclusion services across lending, payments, insurance and savings offerings.
Three companies from the same screener. Open all 204 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com