


EN
Exzeo Group (XZO) Just Raised A Bigger Question
Exzeo Group (XZO) just released a busy Q3 update, reporting steady earnings alongside a completed share buyback that retired 513,211 shares for US$8.34 million between mid August and early November.
That Q3 update landed after a choppy stretch for Exzeo Group, with a 1-day share price return of 1.29% to US$16.50, a 7-day share price return that declined 9.69%, and a year to date share price return down 27.5%. The 1-year total shareholder return fell 14.82%, suggesting recent earnings stability and the completed buyback are being weighed against a longer period of fading momentum.
Scan the insurance tech space for other Exzeo Group style stories by reviewing 19 high quality undiscovered gems that pair solid fundamentals with under the radar share price moves.Exzeo Group is trading well below analyst targets after a weak share price run, even as earnings and the buyback hold steady. Is that enough reason to step in now instead of waiting for a cheaper entry?
Price-to-Earnings of 17.3x: Is it justified?
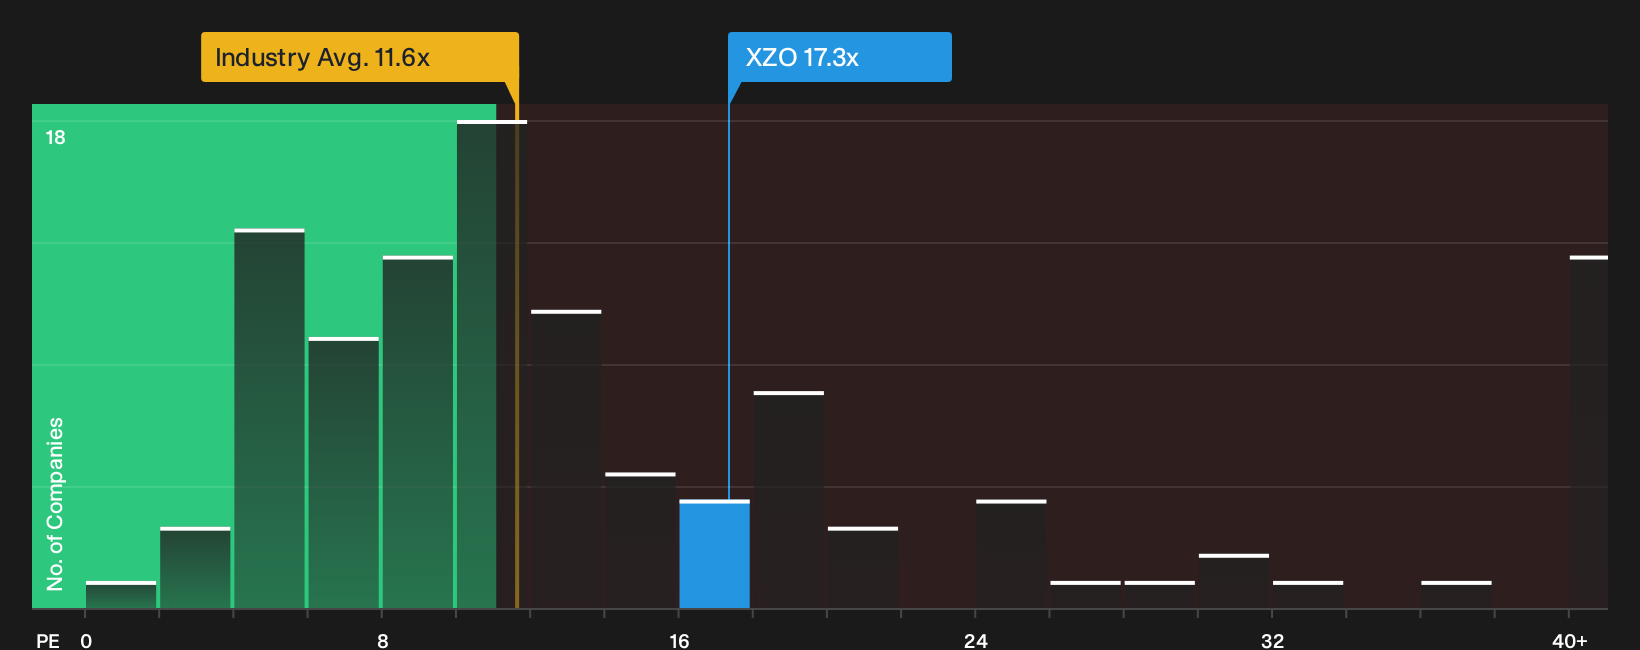
On simple earnings terms, Exzeo Group trades on a P/E of 17.3x, which sits above both its insurance peers and the wider industry despite the recent share price slide to $16.50.
The P/E ratio compares what investors are currently paying for each dollar of profit. It is a common yardstick for insurance and financial technology stocks where profitability and return on equity carry a lot of weight.
Exzeo Group shows high quality earnings and a strong Return on Equity of 29.5%, along with current net profit margins of 36.7% compared with 33.2% last year. This helps explain why the market is prepared to ascribe a higher multiple than many insurers.
Even so, the stock is described as expensive versus the US Insurance industry average P/E of 11.4x and also above a 15.9x peer average. It is still close to an estimated fair P/E of 18.8x that the market could plausibly migrate toward over time.
Explore the SWS fair ratio for Exzeo Group.
Result: Price-to-Earnings of 17.3x (OVERVALUED)
Still, Exzeo Group relies heavily on the US property and casualty market, and any pressure on policy volumes or pricing could quickly challenge those premium valuation multiples.
Find out about the key risks to this Exzeo Group narrative.
Another view on Exzeo Group’s value
On the earnings multiple, Exzeo Group screens as expensive next to insurers, but close to an 18.8x fair ratio that our model suggests the market could move toward. The extra premium versus the 11.4x industry and 15.9x peer averages raises the risk that sentiment, not just profits, ends up driving the next move.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Exzeo Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the cautious tone here matches your own read on Exzeo Group? Take a closer look at what the market is optimistic about through the 3 key rewards.
Looking for more investment ideas beyond Exzeo Group?
If Exzeo Group has sharpened your focus on quality and valuation, you can use that same mindset to uncover other opportunities that fit your risk and return preferences.
- Target resilient balance sheets that can handle rough patches by scanning our list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities where quality and value line up by reviewing the 33 high quality undervalued stocks.
- Prioritise steadier rides over sharp swings by filtering for 30 resilient stocks with low risk scores before the crowd catches up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com