


EN
What Investors Got Wrong About ZoomInfo Technologies Before A 67% Slide
If you bought into ZoomInfo Technologies on the upbeat AI and upmarket thesis in late 2025, the past year has been bruising. Investors who held ZoomInfo Technologies over the past year are down 66.8%, including dividends. If that holding period matched your own decision window, the sharper question now is not whether the share price fell, but which original assumptions about steady revenue growth, margin expansion, and a 2028 P/E reset proved too optimistic or too fragile.
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
This theme extends beyond ZoomInfo Technologies. See which of 40 AI small caps may still merit a closer look.
The Case For ZoomInfo Technologies, And The Case Against
The shares cost US$10.57 at the start of the period. Anyone looking at ZoomInfo Technologies then had to choose between two grounded stories about what came next.
The bullish Narrative saw Fair Value at US$11.65, about 10% above the start price. It leaned on assumptions of 2.8% annual revenue growth, profit margins reaching 15.1%, and a future P/E of 19.3x within roughly three years.
The cautious view put Fair Value nearer US$6.79, or 36% below the start price. That side focused on risks from shrinking SME demand and heavy spending on sales and product. Those factors could pressure margins even if Copilot and the upmarket shift gained traction.
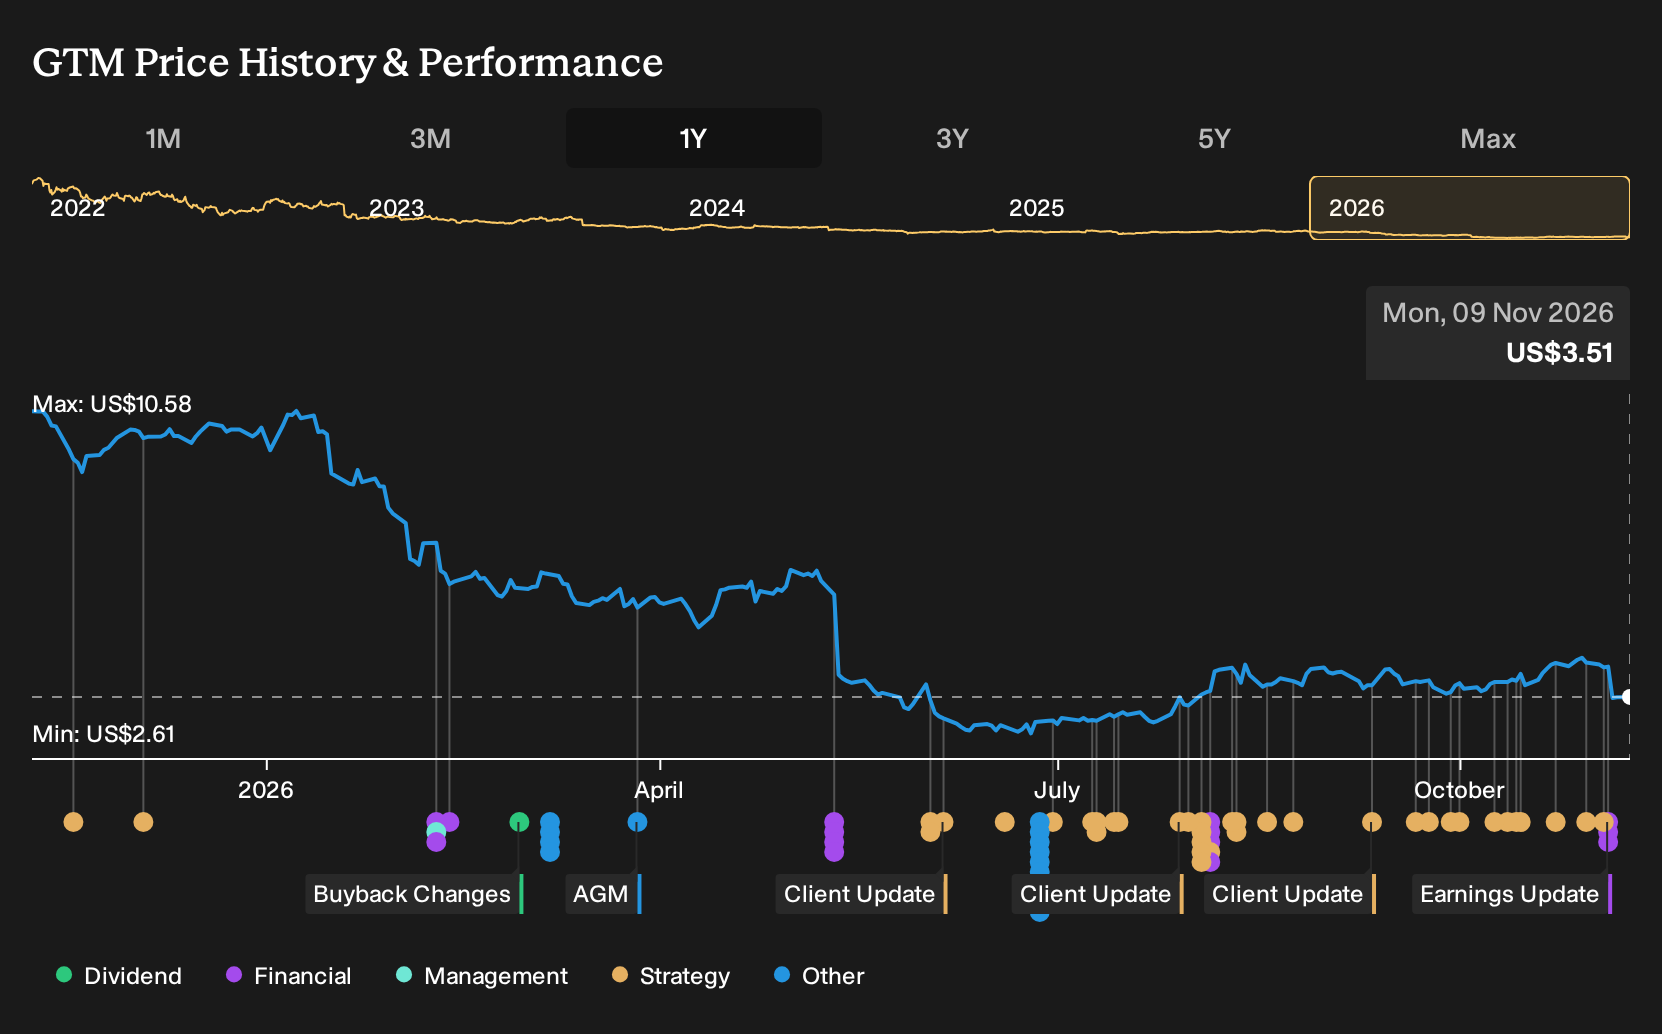
What The Evidence Did To The ZoomInfo Technologies Argument
ZoomInfo Technologies cut 2026 revenue guidance, reworked its pricing model, and reduced headcount by about 20%, which directly challenged the bullish assumption of smooth margin expansion. Later Q3 2026 figures showed revenue at US$308.8m versus US$318m a year earlier, and net margin moving from 12.2% to 0.7%. Taken together, this backed the cautious case.
The hinge assumption was that AI driven products and an upmarket shift would quickly lift profitability. When you assess another software stock with a similar pitch, track whether net margin and guidance both move in the same direction as the AI story, not just whether new features ship.
What You Would Be Paying For In ZoomInfo Technologies Today
At today’s price of US$3.51, the bullish analyst Narrative on Simply Wall St sees Fair Value above the market and ties that view to ZoomInfo Technologies leaning hard into AI agents, workflow automation, and a leaner cost base.
For the fall to look like a potential opportunity rather than a warning, you would need to believe that enterprise adoption of GTM.AI workflows and non seat usage can support those margin and cash flow ambitions despite recent revenue pressure.
"ZoomInfo Technologies is repositioning itself as a headless go to market context layer through GTM.AI, API access, and integrations into tools such as Replit, Slack AI, and Superhuman Go. This could widen its addressable usage beyond human sellers and support new data consumption revenue streams over time, with potential implications for revenue and gross margins."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where ZoomInfo’s AI Story Echoes
ZoomInfo talks about AI agents and richer data workflows. You could also look at who builds the heavyweight tools many AI builders rely on.
Another tech giant sells cloud platforms that bundle AI models, data tools, and collaboration software. That toolkit helps businesses design, deploy, and run AI applications at scale.
The same buyers comparing ZoomInfo’s go to market software often review these broader AI infrastructure choices too. They are deciding where core workflows and data actually live.
If that wider platform keeps attracting more AI spend and experimentation, your ZoomInfo thesis might sit inside a much larger decision tree.
One Narrative has already put a figure on it. → Uncover the company trading 33% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com