


EN
How Investors May Respond To BAE Systems (LSE:BA.) Combat Air Partnership
- BAE Systems reported a series of defence wins including a successful live fire trial of its Adaptable Deck Launcher, an expanded Horizon Solutions aftermarket offering for commercial aviation and a new Memorandum of Understanding with Bombardier on future combat air capabilities, alongside upcoming board changes and director retirements.
- The cluster of defence electronics, unmanned systems and air combat initiatives, together with a deep order book, highlights how BAE Systems is tying long term programmes to concrete products and services that address demand for resilient air and maritime capabilities.
- We will now look at how BAE Systems' investment narrative could be influenced by the Bombardier combat air collaboration news.
BAE Systems Investment Narrative Recap
To own BAE Systems, you need to be comfortable with a long pipeline of defence contracts and a business that depends heavily on flawless execution and capacity build out. The analyst consensus Narrative on Simply Wall St leans on an £84b order backlog and around £260b of total positions, with earnings and revenue forecasts tied to converting that into cash.
In the short term, the key swing factor remains whether those large programs, especially in Maritime and munitions, move through early phases without margin drag. The board changes, including Shobie Ramakrishnan joining and two non executive retirements, look incremental for now rather than a direct catalyst or new risk.
The Bombardier Memorandum of Understanding is the clearest link to the combat air story investors already focus on. It connects directly with Global Combat Air Programme expectations that multi decade aircraft and systems contracts could keep feeding the backlog and support a mix shift toward more complex electronics and integration work.
For you, the interest is less the headline partnership and more what it indicates about execution on those long dated catalysts. If BAE Systems can turn this type of collaboration into concrete roles across research, systems integration and lifecycle support, it could help address that open question about capacity and digital delivery raised in the analyst consensus Narrative on Simply Wall St.
BAE Systems' current analyst narrative points to revenues of £40.6b and earnings of £3.1b by 2029, based on an assumed 11.4% yearly revenue growth rate and an earnings increase of about £1b from current earnings of £2.1b.
Discover why BAE Systems' fair value signals a 21% potential upside to its current price, an opportunity that may narrow quickly.
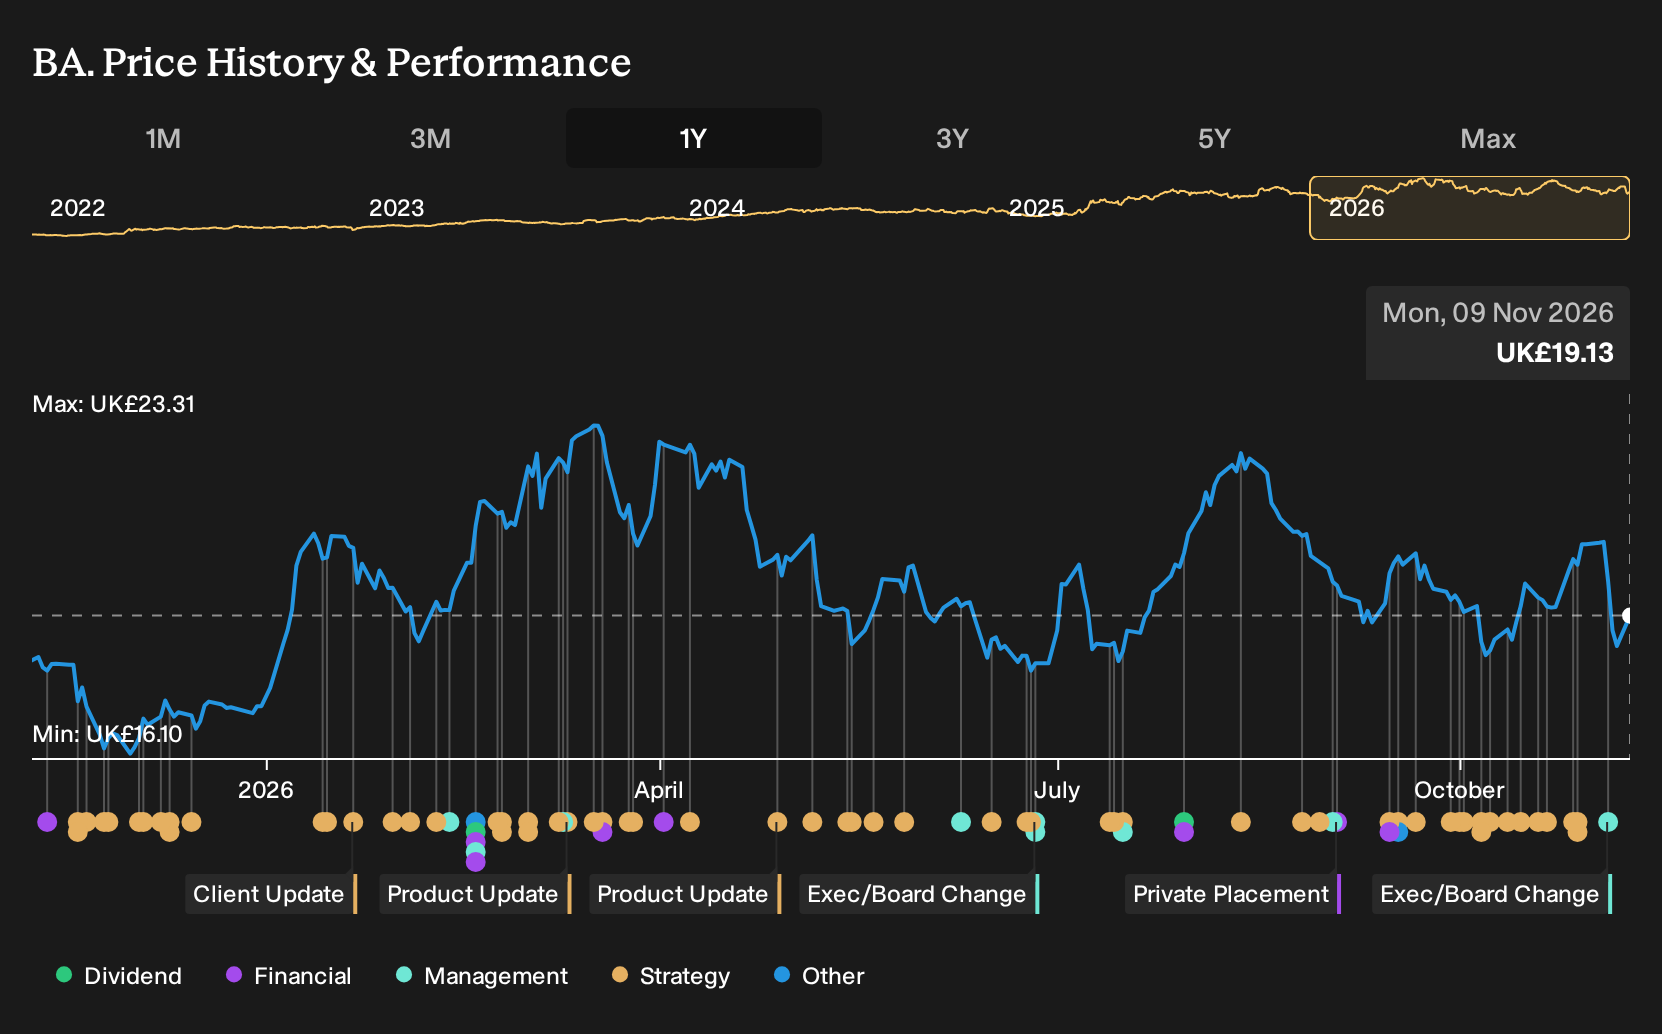
Exploring Other Perspectives
For a very different lens on BAE Systems, focus on the bearish view that questions how much of the long term backlog really turns into dependable revenue. The lowest analysts were pencilling in around £39.2b of sales and £3.0b of earnings by 2029 before this Bombardier combat air news. That cohort sees far less upside than consensus. You can treat the new collaboration and leadership changes as fresh information that might eventually shift either narrative. It is therefore worth comparing both sets of expectations before considering your own stance.
Explore 4 other BAE Systems fair value estimates, including one that suggests it could be worth just £23.14!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your BAE Systems research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for BAE Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate BAE Systems' overall financial health at a glance.
Looking for more BAE Systems style investment ideas?
If you want to broaden your watchlist beyond BAE Systems, the Simply Wall St Screener can help you sort the wider market into focused, research ready shortlists that fit your own approach.
- If you care most about quality at a reasonable entry point, shortlist companies with stronger fundamentals and potentially appealing entry prices using the 16 high quality undervalued stocks.
- If balance sheet strength is non negotiable for you, filter for companies with cleaner debt profiles and sturdier finances through the list of solid balance sheet and fundamentals (9 results).
- If you prefer to keep risk tightly controlled, refine your universe to more resilient businesses by running the 4 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com