


EN
i-80 Gold (TSX:IAU) Jumped, What Is Behind The Move?
i-80 Gold (TSX:IAU) has released its third-quarter and nine-month results to September 30, 2026, reporting US$32.73 million in quarterly sales and a net loss of US$48.35 million from continuing operations.
The latest earnings update has landed in the middle of a volatile year for i-80 Gold, with the share price at CA$2.10 after a 1-day share price return of 5% and a 7-day share price return of 8.81%, even though the 90-day share price return is down 9.09% and the 30-day share price return is down 7.08%. That mix of short-term strength and recent weakness sits against a much stronger picture on a longer view, where the 1-year total shareholder return of 52.17% contrasts with a 5-year total shareholder return that is down 37.13%. This hints that sentiment has improved more recently as investors weigh higher sales against the wider losses highlighted in the third quarter and nine month results.
Spot potential momentum shifts beyond i-80 Gold by scanning a curated group of 34 elite gold producer stocks that are also reacting to fresh production and earnings updates.With i-80 Gold up strongly over the past year but still carrying sizeable losses, the real puzzle now is whether the current price still compensates you for that risk as valuation comes into focus next.
Most Popular Narrative: 55% Undervalued
At a last close of CA$2.10 versus a fair value estimate of CA$4.63, the analyst consensus Narrative on Simply Wall St frames i-80 Gold as heavily discounted, using a 9.1% discount rate and detailed production, margin and funding assumptions to get there.
The planned transition by i-80 Gold from third party toll milling to owner operated processing at the Lone Tree autoclave and CIL plant from 2028, with management expecting a US$1,000 to US$1,500 per ounce uplift in cash margins, is presented as pointing to a step change in net margins and operating cash flow once the hub is fully ramped.
See why 14 investors see i-80 Gold as 55% undervalued.
Result: Fair Value of CA$4.63 (UNDERVALUED)
Still, the narrative around i-80 Gold can crack if large net losses persist or if Lone Tree timelines and capital needs slip further and strain cash.
Find out about the key risks to this i-80 Gold narrative.
Another View on i-80 Gold’s Valuation
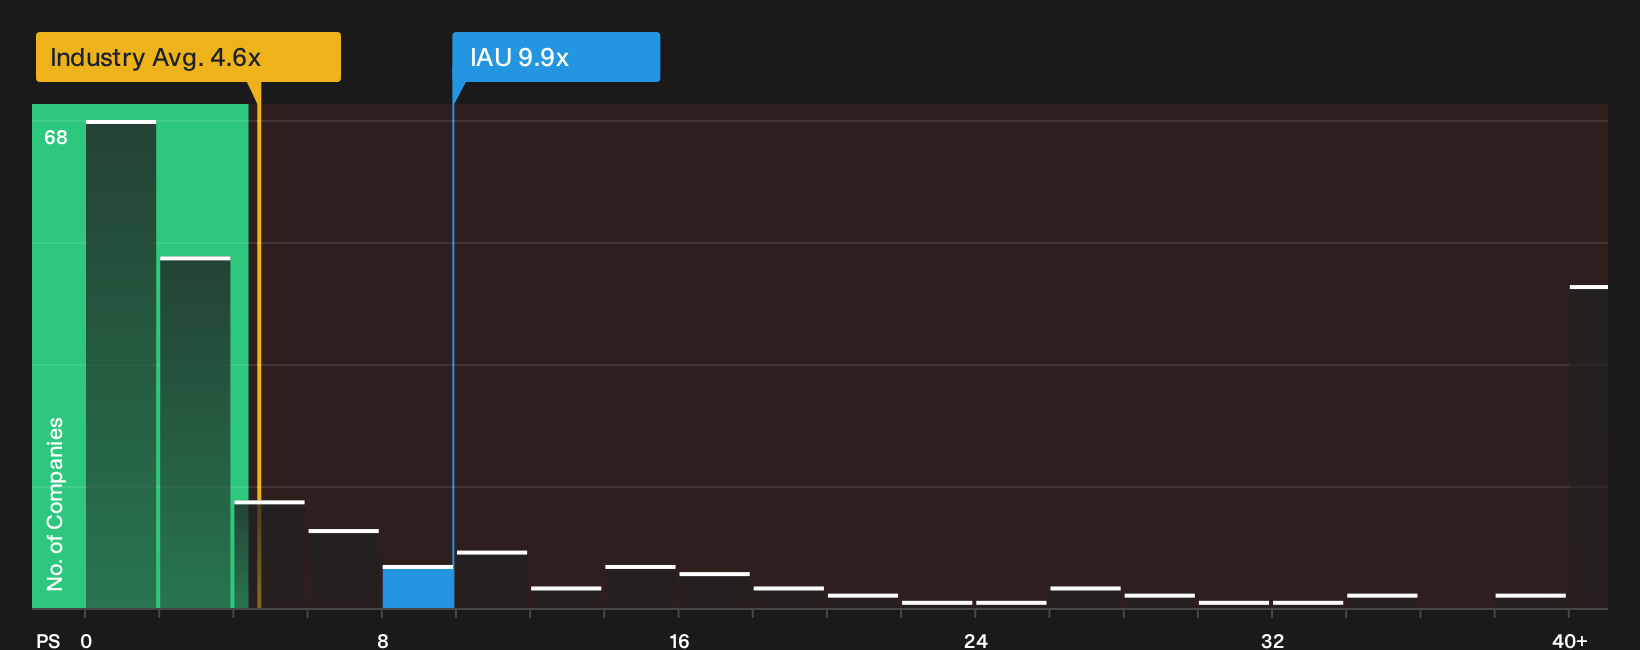
The analyst narrative presents i-80 Gold as heavily undervalued around CA$2.10 based on future earnings power, yet the current P/S of 9.9x suggests a tougher picture. That is more than double the Canadian Metals and Mining average of 4.4x and well above the 4.4x fair ratio, which points to meaningful valuation risk if sentiment cools.
For investors weighing that gap between narrative and sticker price, it can help to see what the numbers imply at different multiples before forming a view on i-80 Gold's potential next move. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around i-80 Gold can feel confusing, so it may help to act promptly and examine the story against the raw data yourself. To see why some investors still flag potential upside, review the 2 key rewards
Looking for more investment ideas beyond i-80 Gold?
If you stop with i-80 Gold, you risk missing other setups that better fit your goals. Use the screener to pressure test fresh ideas fast.
- Target higher potential returns by scanning for quality opportunities that still look mispriced using the 6 high quality undervalued stocks.
- Protect your downside first by filtering for companies with strong finances through the list of solid balance sheet and fundamentals (5 results).
- Pinpoint resilient opportunities by focusing on businesses with steadier profiles via the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com