


EN
LGI Homes (LGIH) Could Be 50% Undervalued As Third Quarter Earnings Lift Sentiment
LGI Homes (LGIH) is back in focus after its latest earnings release, with third quarter figures showing higher revenue and net income compared with the same period a year earlier.
Investors have reacted quickly to the earnings release, with LGI Homes’ latest share price at $46.60 after a 1-day share price return of 2.26%. However, the 90-day share price return is down 19.38%, and the 5-year total shareholder return has fallen 67.41%. This indicates that recent momentum is rebuilding only tentatively against a weak longer-term record.
See how LGI Homes compares with other residential builders by reviewing a curated list of list of solid balance sheet and fundamentals (25 results).
LGI Homes has just posted solid quarterly progress, yet the share price is still well below past levels. Is that brief rebound an early opening to build a position, or a signal to wait for a cheaper entry as the valuation picture comes into focus?
Most Popular Narrative: 49.9% Undervalued
Against LGI Homes' last close at $46.60, the analyst consensus Narrative on Simply Wall St anchors fair value at $93. This frames the current debate around how much the market is crediting its land position and future earnings power.
The main thing that has to go right is that LGI Homes maintains margin resilience through its self-developed land, owned lot base and controlled construction costs, despite pressure on entry-level buyers and potential cost inflation.
See why 7 investors see LGI Homes as 50% undervalued.
Result: Fair Value of $93 (UNDERVALUED)
Still, LGI Homes faces real pressure from a 49.4% cancellation rate and higher building material costs that could squeeze homebuilding margins and challenge that undervalued thesis.
Find out about the key risks to this LGI Homes narrative.
Another View: LGI Homes And The SWS DCF Check
Analysts on Simply Wall St frame LGI Homes as 49.9% undervalued against a $93 fair value, yet the SWS DCF model tells a very different story. On that cash flow view, an estimated value of $15.57 per share points to the stock trading well above modelled future cash generation. Which lens do you trust for your own work?
For a closer look at how those cash flow assumptions are built and stress tested, run through the full SWS DCF model explanation here Look into how the SWS DCF model arrives at its fair value..
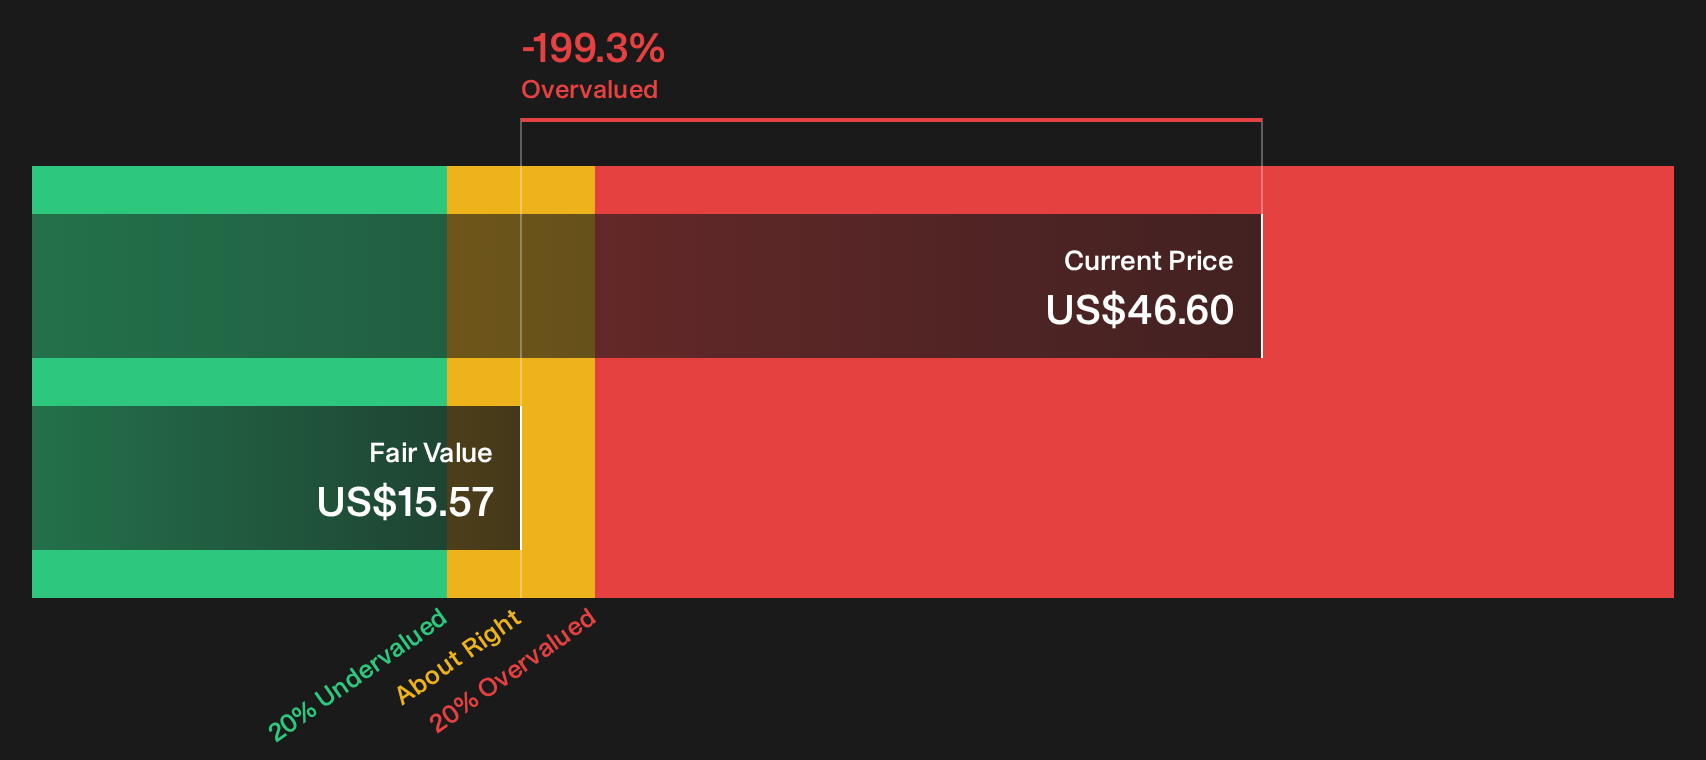
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out LGI Homes for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around LGI Homes is split, with risks and rewards both pulling at the story. Move fast, review the underlying data, and then weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond LGI Homes?
If LGI Homes has sharpened your focus, do not stop here. Broaden your watchlist now or you risk missing opportunities that better fit your approach.
- Target potential upside in mispriced businesses by scanning a focused set of 33 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
- Build a steadier income stream by reviewing 6 dividend fortresses that aim to pair higher yields with more resilient balance sheets.
- Dial down portfolio stress by concentrating on 30 resilient stocks with low risk scores that score well on financial strength and earnings stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com