


EN
Here's Why We're Watching Stillwater Critical Minerals' (CVE:PGE) Cash Burn Situation
Just because a business does not make any money, does not mean that the stock will go down. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. But while the successes are well known, investors should not ignore the very many unprofitable companies that simply burn through all their cash and collapse.
So should Stillwater Critical Minerals (CVE:PGE) shareholders be worried about its cash burn? In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. First, we'll determine its cash runway by comparing its cash burn with its cash reserves.
How Long Is Stillwater Critical Minerals' Cash Runway?
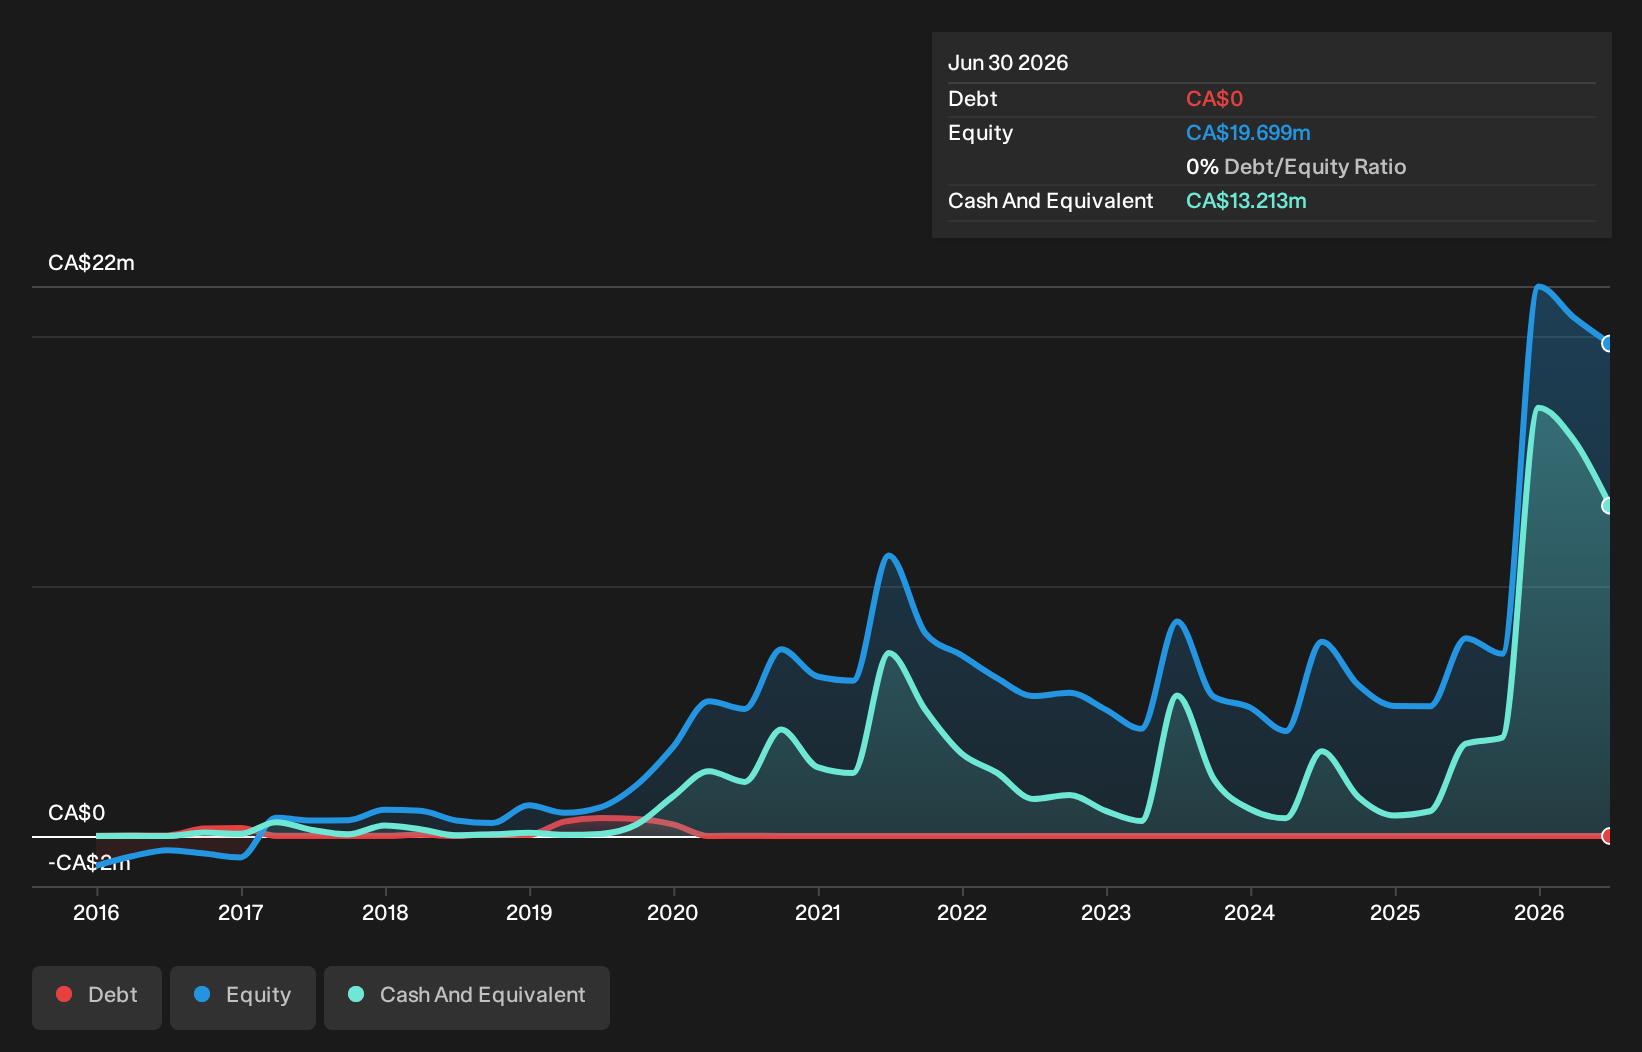
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. When Stillwater Critical Minerals last reported its June 2026 balance sheet in August 2026, it had zero debt and cash worth CA$13m. Importantly, its cash burn was CA$11m over the trailing twelve months. That means it had a cash runway of around 14 months as of June 2026. While that cash runway isn't too concerning, sensible holders would be peering into the distance, and considering what happens if the company runs out of cash. Depicted below, you can see how its cash holdings have changed over time.
View our latest analysis for Stillwater Critical Minerals
How Is Stillwater Critical Minerals' Cash Burn Changing Over Time?
Because Stillwater Critical Minerals isn't currently generating revenue, we consider it an early-stage business. So while we can't look to sales to understand growth, we can look at how the cash burn is changing to understand how expenditure is trending over time. In fact, it ramped its spending strongly over the last year, increasing cash burn by 193%. It's fair to say that sort of rate of increase cannot be maintained for very long, without putting pressure on the balance sheet. Stillwater Critical Minerals makes us a little nervous due to its lack of substantial operating revenue. We prefer most of the stocks on this list of stocks that analysts expect to grow.
How Hard Would It Be For Stillwater Critical Minerals To Raise More Cash For Growth?
Given its cash burn trajectory, Stillwater Critical Minerals shareholders may wish to consider how easily it could raise more cash, despite its solid cash runway. Companies can raise capital through either debt or equity. Commonly, a business will sell new shares in itself to raise cash and drive growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Stillwater Critical Minerals' cash burn of CA$11m is about 12% of its CA$95m market capitalisation. As a result, we'd venture that the company could raise more cash for growth without much trouble, albeit at the cost of some dilution.
How Risky Is Stillwater Critical Minerals' Cash Burn Situation?
Even though its increasing cash burn makes us a little nervous, we are compelled to mention that we thought Stillwater Critical Minerals' cash burn relative to its market cap was relatively promising. We don't think its cash burn is particularly problematic, but after considering the range of factors in this article, we do think shareholders should be monitoring how it changes over time. On another note, we conducted an in-depth investigation of the company, and identified 5 warning signs for Stillwater Critical Minerals (3 are a bit unpleasant!) that you should be aware of before investing here.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.