


EN
Strathcona Resources (TSX:SCR) Just Gave The Market Something To Think About
Strathcona Resources (TSX:SCR) has given investors fresh numbers to parse after reporting third quarter 2026 results, combining higher revenue, lower net income, and a richer dividend along with a sizeable Greenfire Resources acquisition agreement.
Despite the fresh earnings and the Greenfire deal, Strathcona Resources’ share price has drifted. The 7 day share price return is down 6.35% and the 90 day move is down 15.87%, even though the year to date share price return is up 24.74% and the 3 year total shareholder return is up 123.31%. This points to long term holders still sitting on strong gains, while shorter term momentum has cooled as investors reassess both growth prospects and risk around the larger, more complex business.
Position your portfolio alongside Strathcona Resources by scanning a hand picked set of Canadian energy producers with strong fundamentals through the list of solid balance sheet and fundamentals (5 results).Strathcona Resources now trades well below its recent highs even after the Greenfire deal and richer dividend, which leaves a simple tension. Is most of the re rating already done, or is the discount still meaningful?
Most Popular Narrative: 32% Undervalued
On the analyst consensus Narrative on Simply Wall St, Strathcona Resources screens as undervalued, with a fair value of CA$53.10 against a last close of CA$36.00. This highlights a clear gap between the current share price and that narrative estimate while anchoring everything to a 6.44% discount rate.
The reaffirmed plan to grow total production to 300,000 bbl/d by 2035, supported by a maintained capital budget of C$1.0b and tightened 2026 production guidance, points to a long project backlog that could sustain future revenue and scale driven margin efficiency.
See why 9 investors see Strathcona Resources as 32% undervalued.
Result: Fair Value of CA$53.10 (UNDERVALUED)
Still, this hinges on oil prices and heavy crude differentials not eroding free cash flow, and on balance sheet trends supporting the current dividend framework.
Find out about the key risks to this Strathcona Resources narrative.
Another View: What The Market Multiple Says About Strathcona Resources
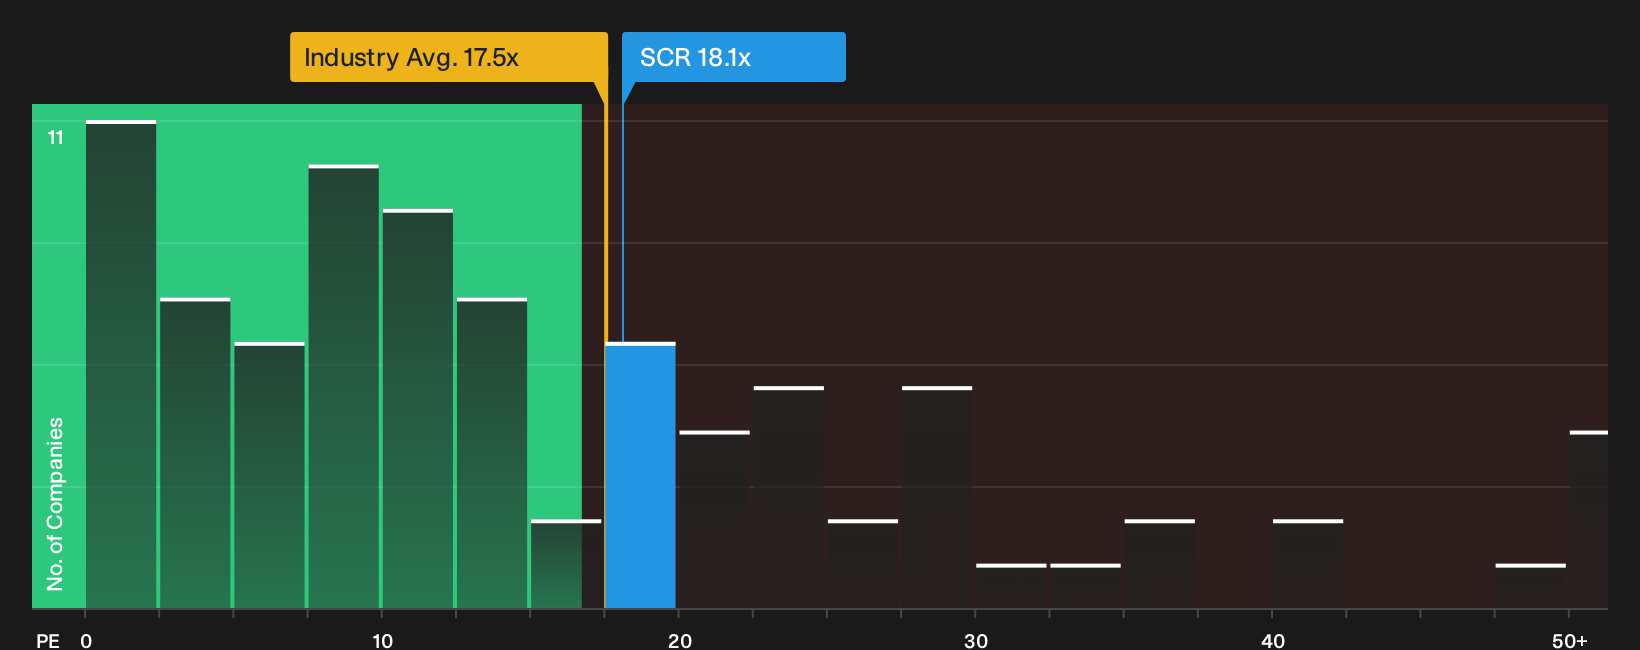
On simple ratios, Strathcona Resources looks less generous than the narrative fair value. The stock trades on a P/E of 18.1x, compared with a fair ratio of 12.6x and a Canadian oil and gas average of 17.7x. That gap points to valuation risk if sentiment cools again.
For investors who prefer to anchor on simple ratios, the question is whether Strathcona Resources has enough quality and duration in its assets to justify paying above that fair ratio, or whether patience for a cheaper entry makes more sense at this stage.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Strathcona Resources can be confusing, so move quickly, review the full data set, and weigh both sides of the story yourself. To see the key pressure points as well as the upside arguments side by side, start with these 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Strathcona Resources?
If Strathcona Resources has sharpened your focus, do not stop here. Fresh ideas often come from widening your search just when others narrow theirs.
- Target potential mispricings by reviewing a curated set of currently overlooked candidates through the 7 high quality undiscovered gems.
- Strengthen your income stream by assessing companies that combine higher yields with resilient fundamentals using the 3 dividend fortresses.
- Dial back risk without stepping out of the market by reviewing a hand picked pool of defensively positioned stocks through the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com