


EN
Impinj (PI) Shares Just Moved, So What Is Behind The Attention?
Why the latest Impinj earnings matter for investors
Impinj (PI) kicked off the latest conversation around its stock with third quarter numbers and fresh guidance, as the RFID platform provider moved from a prior net loss to a quarterly profit.
The headline figures draw attention because they combine two things investors usually look for: there is a clear shift to positive net income for the quarter, and there is management commentary in the form of revenue and earnings expectations for the final stretch of 2026.
Recent trading tells a mixed story for Impinj. The share price is at US$174.73 after a 2.16% 1 day share price return, yet the 30 day share price return is down 7.86% and year to date is down 2.8%. At the same time, the 1 year total shareholder return sits at 8.86% and the 3 year total shareholder return is up around 14x, which suggests that investors may be reassessing shorter term expectations following a strong multi year run while reacting to the fresh earnings report and guidance.
Spot opportunities around Impinj’s earnings shift by scanning a hand picked group of 53 AI infrastructure stocks.Bulls point to Impinj’s swing into profit and fresh guidance, while bears focus on the pullback and past losses. Which story do the current valuation signals support?
Most Popular Narrative: 12% Undervalued
On the analyst consensus Narrative on Simply Wall St, Impinj screens as modestly undervalued, with a fair value of $199 against the last close at $174.73. That view leans heavily on how the RAIN RFID rollout and margin story are expected to play out over time.
Expanding deployment of RFID solutions for food traceability and freshness, especially at the item level with three of the five largest U.S. grocers now running pilots or deployments in bakery, deli and meats, supports the view that Impinj can extend endpoint IC demand beyond apparel into a much larger addressable market and drive future revenue growth.
See why 19 investors see Impinj as 12% undervalued.
Result: Fair Value of $199 (UNDERVALUED)
Still, Impinj’s story can break if retailer demand weakens again or if high implied P/E expectations coincide with any renewed execution slip with key logistics customers.
Find out about the key risks to this Impinj narrative.
Another View: What Impinj’s P/S Ratio Is Signalling
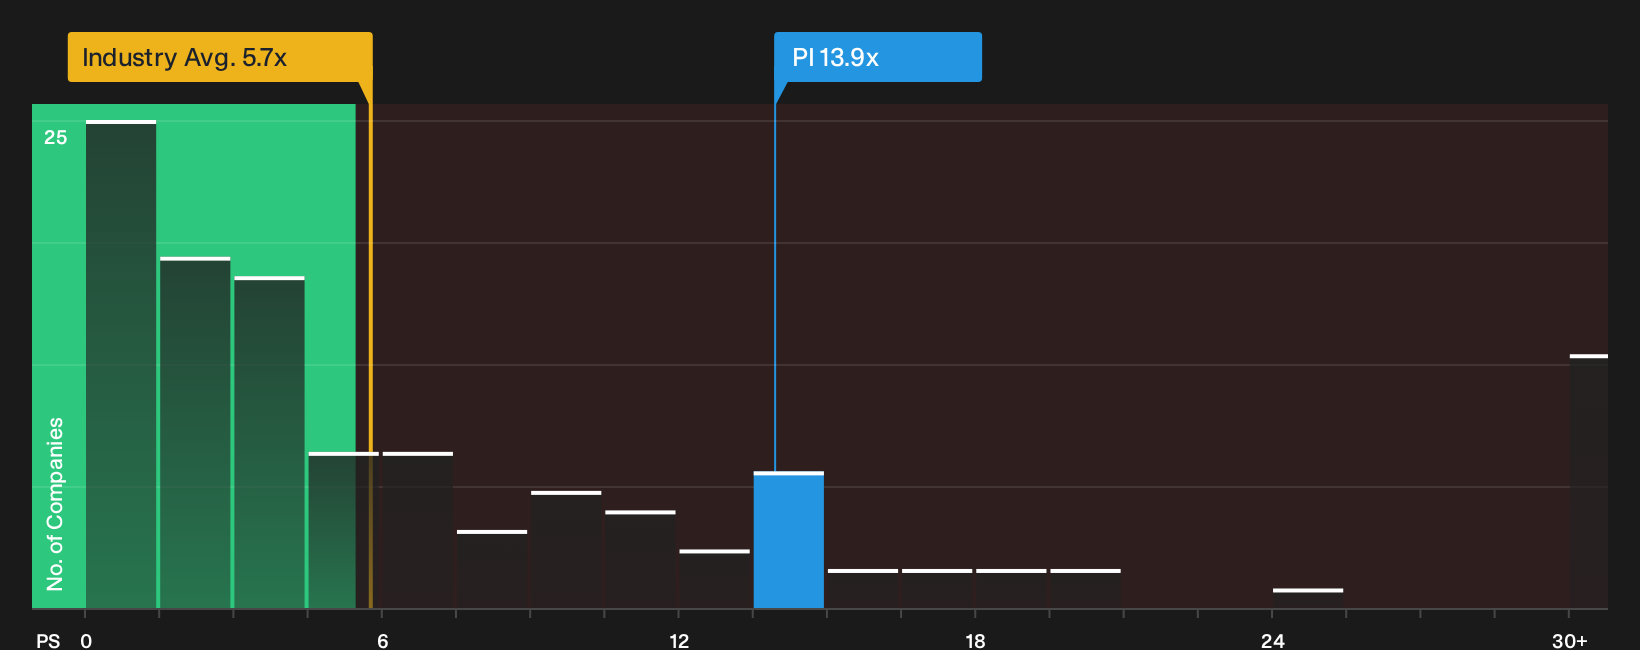
Impinj screens as undervalued on the analyst fair value of $199, yet the current P/S ratio of 13.9x tells a different story. That multiple is far above the US Semiconductor industry at 5.2x, the peer average at 4.7x, and a fair ratio of 5.2x, which points to meaningful valuation risk if expectations slip.
For a closer look at what the numbers are implying about this pricing gap, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this Impinj debate feels finely balanced, move quickly from reading opinions to weighing the numbers yourself, and then consider the potential upside in 2 key rewards.
Looking for more investment ideas beyond Impinj?
If Impinj has sharpened your view on pricing power and expectations, you may want to extend that momentum. Fresh opportunities rarely wait around for investors who only watch from the sidelines.
- Target resilient compounding by scanning a 30 resilient stocks with low risk scores that focuses on businesses with more stable profiles and lower risk scores.
- Hunt for potential mispricing by reviewing a 33 high quality undervalued stocks that blends solid cash flows with balance sheets that can support future plans.
- Spot potential future leaders early by checking a 19 high quality undiscovered gems that highlights lesser known companies with strong underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com