


EN
BioNTech (BNTX) Stock Looks Above Fair Value On Current Sales
BioNTech has seen its share price come under pressure over the past few years, while its business shifts from pandemic vaccines toward a broader oncology pipeline. That mix of weaker recent returns and a changing revenue base puts a simple question front and center for investors who follow BioNTech stock, namely whether today's valuation is justified by what the company is generating in sales.
- Over the past 5 years, the share price has fallen 64.7%, which puts a lot of weight on whether the current market value still lines up with the revenue story.
- Recent news around lower demand for its COVID-19 vaccine, alongside higher expectations for partnership income and oncology products, can reshape how much sales investors expect and when they expect those cash flows to arrive.
- The analysts covering BioNTech have run their own numbers. See what analysts think BioNTech's shares could be worth.
The issue now is whether BioNTech's current share price of US$87.51 is adequately supported by its sales base, given both the recent share performance and the shift in where its revenue is coming from.
If you want to put BioNTech's sales-based valuation question in context, compare it with 33 high quality undervalued stocks.
Has BioNTech Run Too Far on Sales?
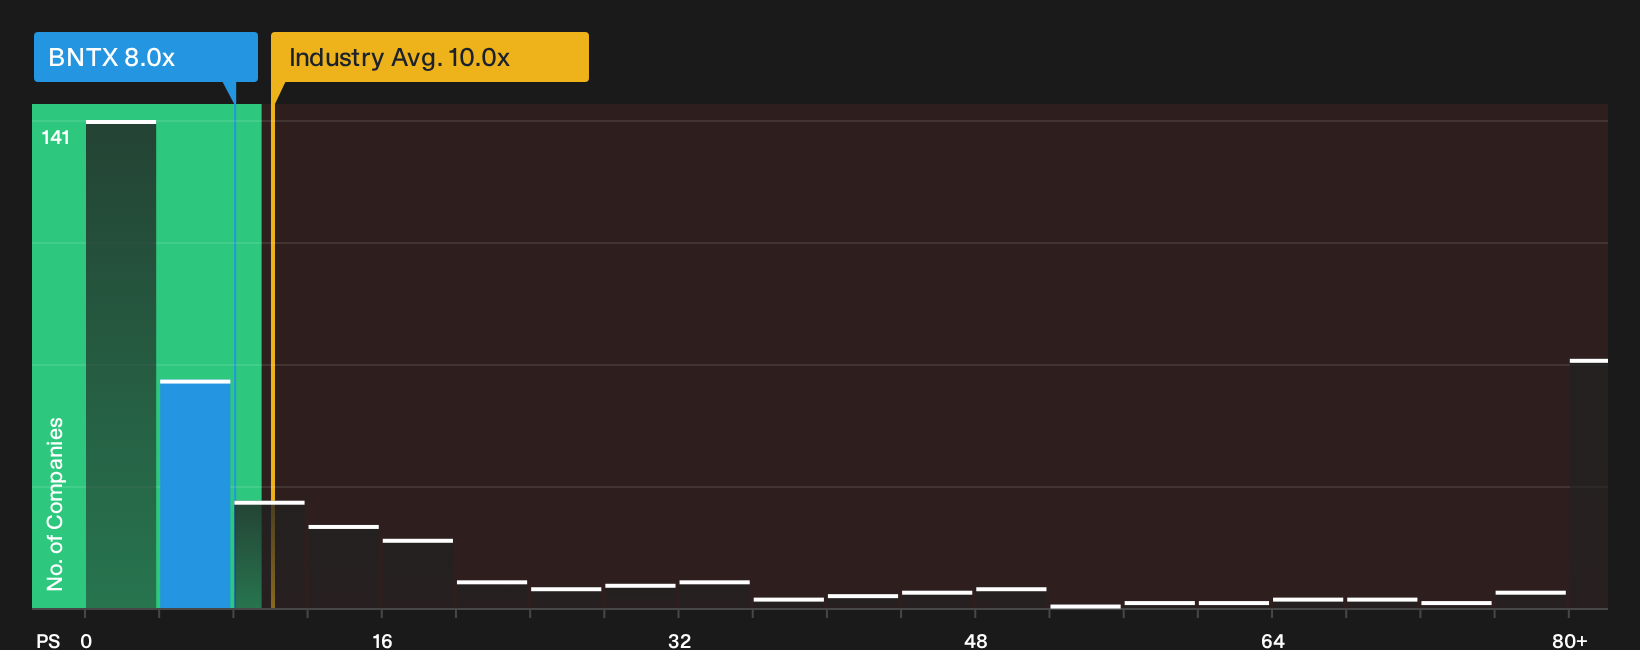
P/S is a useful lens for BioNTech because investors are weighing a pipeline-heavy oncology story against a shrinking COVID line, which makes earnings choppy and less reliable. On this metric, the stock trades on a P/S of 8.0x, which is below the biotech industry average of 10.0x but above the peer group at 5.6x. That places BioNTech between a premium and a discount bucket, with the market pricing its revenue stream more highly than closer peers but not as highly as the sector overall.
The tailored fair multiple, which blends factors such as BioNTech's margins, size and risk profile, is below the current P/S, so the shares screen as overvalued on this framework. Because management recently raised 2026 revenue guidance despite a reported Q3 revenue decline, the current P/S indicates that investors are still paying for the quality and durability of potential future oncology income, rather than treating the stock as a cheap COVID vaccine play. To decide whether that premium is justified, you would need to weigh the probability and timing of that pipeline turning into recurring product sales. Explore the numbers behind BioNTech's P/S valuation.
The BioNTech Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where BioNTech's valuation puzzle leaves off by spelling out what path for future growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today. Instead of giving a single output like a ratio or model result, Narratives lay out the chain of expectations behind that figure so you can monitor over time whether BioNTech's actual progress still matches the story on its Community page.
Bulls and bears on BioNTech are looking at the same oncology toolkit and coming away with very different read throughs for the stock.
Bull case: 82% undervalued
According to Hansimglueck, an investor in the Simply Wall St Community, BioNTech’s edge sits in how it designs and advances its cancer molecules.
"All of the recently developed molecules were not identified by trial and error after a long series of experiments but were designed in advance by the acquired AI forge..."
Discover why this Narrative puts BioNTech at 82% undervalued.
Bear case: 15% overvalued
The bearish analyst Narrative on Simply Wall St focuses on how execution risk in oncology and shrinking COVID demand could weigh on the numbers.
"Although BioNTech is reallocating capital from COVID-19 towards oncology, the termination of the autogene cevumeran adjuvant colorectal cancer Phase II study after a numerical imbalance in deaths shows that clinical risk in mRNA cancer vaccines could still lead to further trial cancellations..."
Explore why this Narrative puts BioNTech at 15% overvalued.
One more BioNTech angle that could change the story
Numbers only tell part of the BioNTech story, because the people who allocate capital and the way their pay packets are structured can pull decisions in very specific directions. See who runs BioNTech and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com