


EN
Brown & Brown (BRO) Survey Puts Growth In Focus As Valuation Questions Linger
Brown & Brown (BRO) is back in focus after releasing its 2027 Employer Health and Benefits Strategy Survey, which spotlights how rising medical and pharmacy costs are reshaping employer plans and benefits priorities.
Despite the survey putting Brown & Brown back in the headlines, recent trading has been more muted. The share price is about US$71.00 after a 30 day share price return of 12.91%, set against a year to date share price decline of 8.53% and a 1 year total shareholder return that is down 8.65%. This points to improving short term momentum but a still underwhelming longer term experience for holders.
Scan how other insurance and benefits specialists are positioned on rising healthcare costs by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) alongside Brown & Brown.
Brown & Brown looks like a solid insurance broker with steady demand drivers, and the recent rebound to about US$71.00 reinforces that perception. The real issue now is whether the valuation already reflects that strength.
Most Popular Narrative: 5% Undervalued
Brown & Brown is trading at about $71.00 compared with the analyst consensus Narrative fair value of $74.75, with that analyst consensus Narrative on Simply Wall St anchoring on detailed revenue, earnings and discount rate assumptions.
Brown & Brown is rolling out AI enabled submission, policy checking and billing tools that are already saving tens of thousands of hours a year and automating more than 25% of the submission process in many programs. This can free producers and underwriters to handle more volume and support future organic revenue growth and operating margin resilience.
See why 34 investors see Brown & Brown as 5% undervalued.
Result: Fair Value of $74.75 (UNDERVALUED)
Still, pressure from producer departures and softer catastrophe property pricing could limit the extent to which Brown & Brown’s AI gains and Accession synergies reshape the story.
Find out about the key risks to this Brown & Brown narrative.
Another View: What Brown & Brown’s P/E Is Telling You
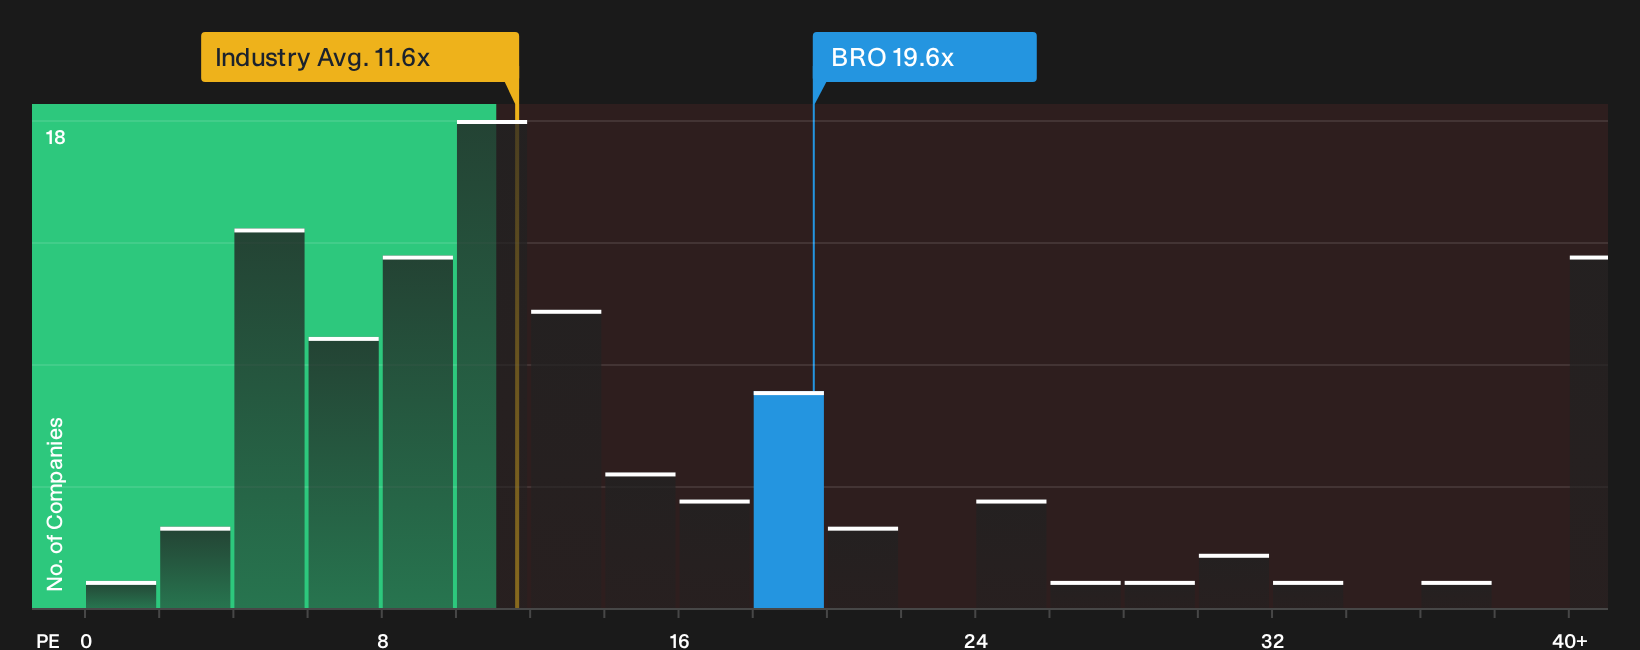
There is a different read on Brown & Brown when you look at simple valuation ratios. The shares trade on a P/E of 19.6x compared with a fair ratio of 13.2x, while the wider US Insurance industry sits near 11.4x and close peers average a much higher 33.4x. That mix of premium to the sector, discount to similar businesses and gap versus the fair ratio points to valuation risk if sentiment cools. It also suggests some investors already see room for quality. Which side of that trade you focus on will depend on your own timeframe.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals in Brown & Brown’s story can actually work to your advantage if you are willing to get into the detail and move quickly to shape your own view. To weigh up both the concerns and the potential upside, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Brown & Brown?
If Brown & Brown has sharpened your thinking, do not stop there. The real edge comes from lining up a few more high quality candidates.
- Target potential mispricing by reviewing the 33 high quality undervalued stocks to find opportunities that pair solid fundamentals with more appealing entry points.
- Build a steadier income stream by checking out the 6 dividend fortresses to explore companies that combine higher yields with resilient business models.
- Dial down portfolio stress by focusing on the 30 resilient stocks with low risk scores to identify investments designed to weather tougher conditions without wild swings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com