


EN
Are Wall Street Analysts Bullish on Fidelity National Stock?
With a market cap of $14.8 billion, Fidelity National Information Services, Inc. (FIS) provides banking, payment, risk management, and capital market solutions to financial institutions, businesses, and developers worldwide. It operates through its Banking Solutions and Capital Market Solutions segments, offering innovative digital and financial services.
Shares of the Jacksonville, Florida-based company have lagged behind the broader market over the past 52 weeks. FIS stock has dropped 56.3% over this time frame, while the broader S&P 500 Index ($SPX) has returned 12.2%. Moreover, shares of the company are down 57.4% on a YTD basis, compared to SPX’s 10.3% gain.
Focusing more closely, shares of the bank have underperformed the State Street Financial Select Sector SPDR ETF’s (XLF) 9.9% rise over the past 52 weeks.
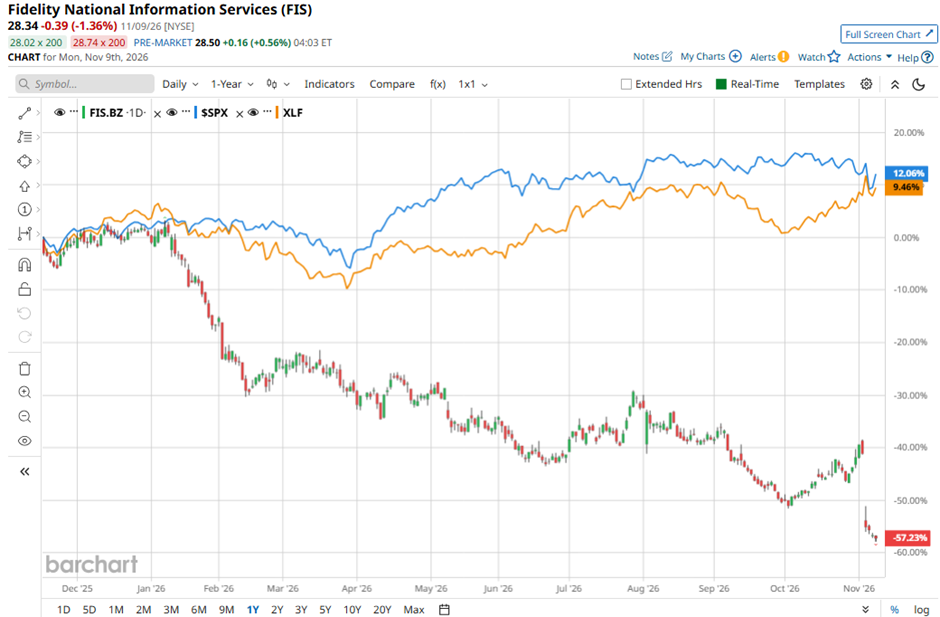
Fidelity National shares tumbled 23.7% on Nov. 4 as its sharply reduced 2026 guidance overshadowed Q3 2026 results, with adjusted EPS of $1.61 matching estimates and revenue rising 27.1% to $3.45 billion, slightly above the consensus. The company cut its 2026 revenue forecast to $13.45 - $13.51 billion, adjusted EBITDA guidance to $5.57 billion - $5.61 billion, and adjusted EPS outlook to $5.82 - $5.89, citing delayed banking conversions, consolidation impacts, lower non-recurring revenue and higher technology and security spending.
The weak 2027 outlook added to pressure, with pro forma revenue expected to range from a 0.5% decline to 1% growth, adjusted earnings projected to fall by a high-single-digit to low-double-digit percentage, and free cash flow expected to remain flat.
For the fiscal year ending in December 2026, analysts expect Fidelity National Information Services’ EPS to grow 1.7% year-over-year to $5.85. The company’s earnings surprise history is mixed. It beat or met the consensus estimates in three of the last four quarters while missing on another occasion.
Among the 31 analysts covering the stock, the consensus rating is a “Hold.” That’s based on five “Strong Buy” ratings, two “Moderate Buys,” 22 “Holds,” and two “Strong Sells.”
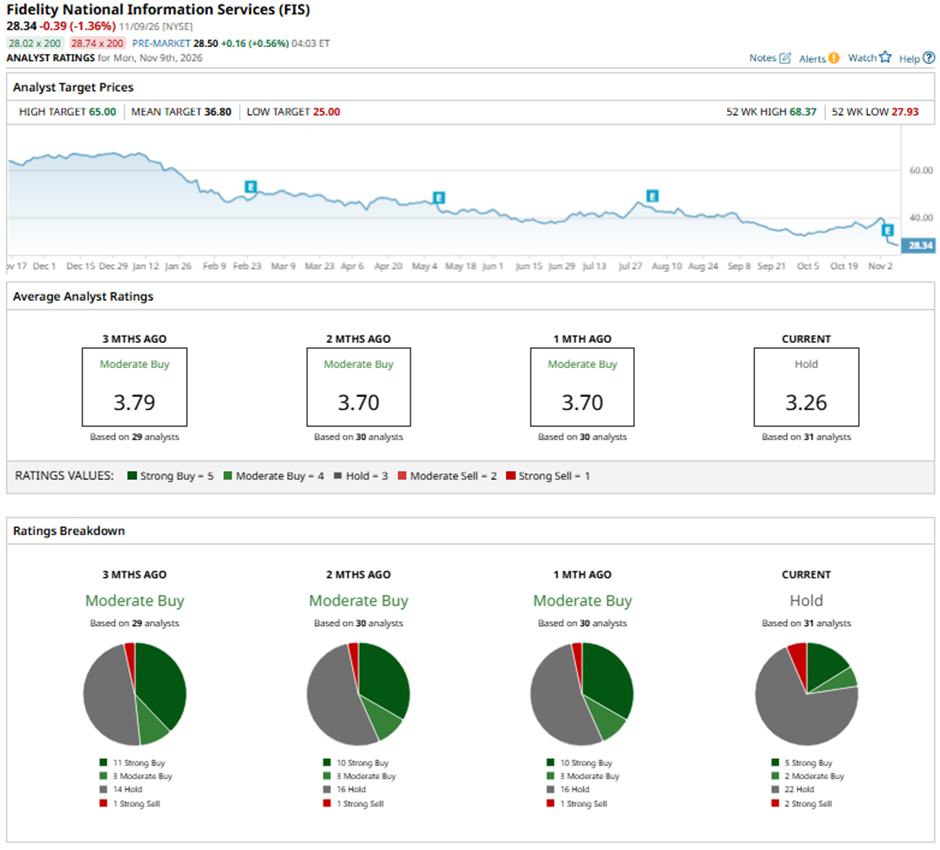
This configuration is less bullish than three months ago, with 11 analysts suggesting a "Strong Buy."
On Nov. 5, Raymond James cut its price target on Fidelity National to $35 while maintaining an "Outperform" rating.
The mean price target of $36.80 represents a 29.9% premium to FIS’ current price levels. The Street-high price target of $65 suggests a 129.4% potential upside.
On the date of publication, Sohini Mondal did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.