


EN
Missed Salzgitter's Run? Here Is What Holders Saw
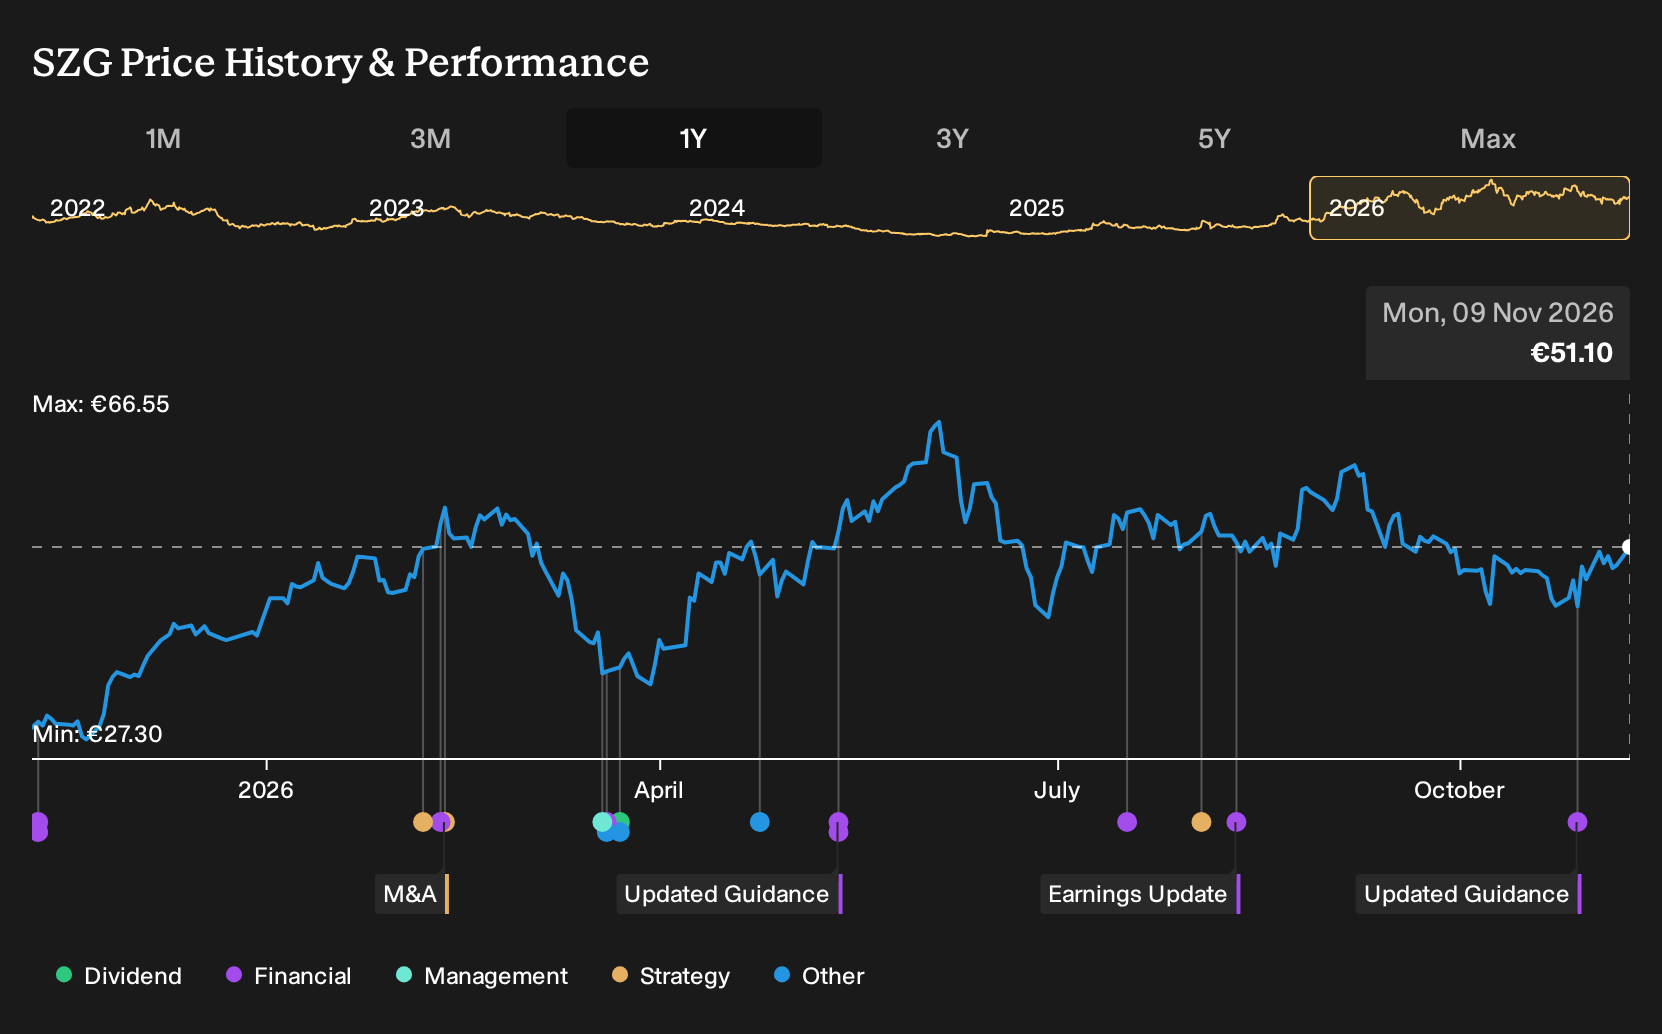
If Salzgitter was sitting on your watchlist instead of in your portfolio, this move may feel like a missed shot. Investors who held Salzgitter over the past year are up 73.7%, including dividends. That result arrived during a stretch when analysts were split between a bullish green steel expansion story and a more cautious view tied to European flat rolled price trends. So back on 9 November 2025, what confidence could you reasonably have had in the assumed 3.5% revenue growth and 4.6% margin target?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Salzgitter is not the only name tied to this theme. Zero in on 16 top copper producer stocks and compare how each one is priced.
The Two Salzgitter Stories Investors Had To Weigh
The shares cost €27.98 at the start of the period, and the live debate around Salzgitter was whether green steel momentum or flat rolled pricing would anchor the story.
The bullish narrative pointed to a Fair Value of €40.03, assuming revenue growth of 3.5% and profit margins rising from a loss position to 4.6% within three years.
The more cautious view set Fair Value at €23.24 and focused on the risk that European flat rolled prices and import pressure could keep profitability subdued.
What The Salzgitter Evidence Actually Tested
The clearest development came from Salzgitter’s Q2 2026 report, where revenue moved from €2,335.2m in Q2 2025 to €2,242.8m while the loss narrowed and net margin improved from -2.4% to -1.8%. That combination supported the cautious case on volume but gave the optimistic camp some support on profitability, so the period cut both ways and left the 4.6% margin target unproven.
The lesson is simple. When a narrative leans on a margin rebound, as Salzgitter’s bull case did, track net margin and absolute profit side by side in each set of results and test whether both are actually moving toward the stated target.
What Salzgitter's Price Is Asking You To Believe Now
Salzgitter trades at €51.1, and the analyst consensus Narrative on Simply Wall St describes a Fair Value that sits above that level based on its current model. The argument leans heavily on decarbonization projects, cost programs and a more supportive EU trade backdrop.
A buyer today would need to judge whether SALCOS, HKM and the P28 savings plan can keep translating into structurally stronger profit without stretching the balance sheet.
"The main requirement is that the large SALCOS and HKM decarbonization projects, together with the P28 cost program and portfolio reshaping, continue to deliver structural cost savings and more resilient profits without putting too much strain on the balance sheet."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Looking One Step Beyond Salzgitter
Salzgitter is about steel, but your theme here is bigger. Low carbon projects and machinery still rely on very specific materials.
Turbines, motors and industrial systems need powerful permanent magnets to work efficiently. Supplying the metals and magnets behind them is a different task entirely.
One specialist producer is pushing deeper into processing and magnet making. It is shifting from basic material output toward higher margin finished products.
Government backing, long contracts and new facilities frame that strategic move. The unresolved issue is how that added complexity might reshape long term earnings power.
One Narrative has already put a figure on it. → Uncover the company trading 47% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com