


EN
How Bigger Infrastructure Bets Will Impact Centrica (LSE:CNA) Investors
- Centrica has been highlighted for expanding investment in regulated and contracted assets, including Sizewell C, Grain LNG and its Meter Asset Provider business, to increase the share of earnings from long term infrastructure alongside its retail and services operations.
- The unresolved credit and funding pressure linked to these nuclear and infrastructure commitments introduces a financing constraint that could meaningfully shape cash generation and capital allocation choices for Centrica.
- We will now look at how Centrica's heavier tilt toward regulated infrastructure shapes the existing investment narrative around earnings mix.
Scan how other regulated energy plays balance big infrastructure builds with funding risk by zeroing in on 4 resilient stocks with low risk scores alongside Centrica’s nuclear and LNG commitments.
Centrica Investment Narrative Recap
To own Centrica, you need to believe the pivot toward regulated infrastructure and contracted assets will steadily raise the share of more predictable earnings, while the retail arm and trading activities remain under control. The analyst consensus Narrative on Simply Wall St leans on that mix shift plus tight cost discipline as the core driver for the story.
Right now, the key short term swing factor is how Centrica handles credit and funding pressure around its nuclear and LNG commitments, on top of rising retail bad debt and working capital strain. If funding terms stay manageable and bad debt is contained, the infrastructure tilt looks additive. If not, the impact on cash generation could be material.
The clearest linked announcement is management’s decision to recycle capital out of North Sea upstream assets into projects such as Sizewell C, Grain LNG, the Meter Asset Provider and CCGTs like Severn. That move concentrates Centrica more in regulated and contracted earnings, including nuclear, right where today’s funding questions are focused.
For you, the question is whether that reallocation improves the balance between stability and financial pressure. These projects contributed about £80m of EBITDA in H1 2026 and are guided to reach roughly £175m in 2026, so execution, cost control and funding terms around this build out sit directly against current credit concerns and remain important catalysts to watch.
Centrica's narrative projects £20.6b revenue and £739.1m earnings by 2029. This assumes 1.7% yearly revenue growth and an earnings increase of about £28.1m from £711.0m today.
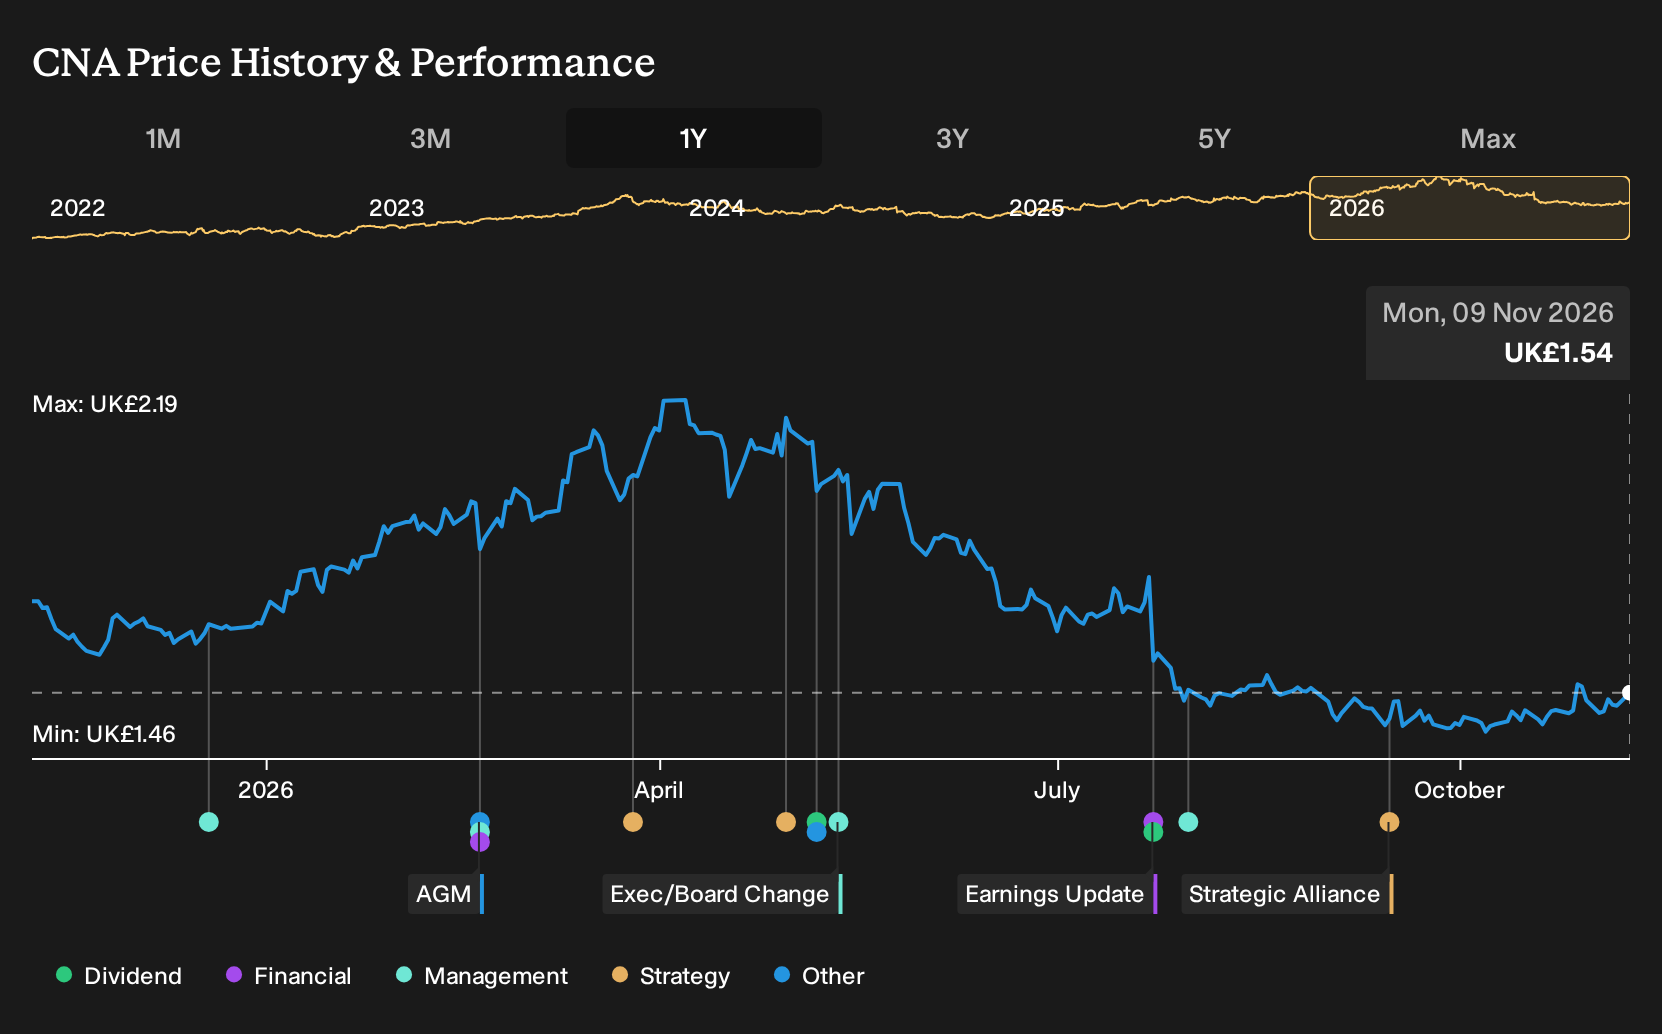
Uncover why Centrica's fair value indicates a 34% potential upside to its current price before that discount to Centrica's story closes.
Exploring Other Perspectives
The three fair value views from the Simply Wall St Community cluster tightly between about 2.06 and 2.14, so retail investors here are working off a narrow price range despite very different narratives. You face rising retail bad debt risk and a heavier Centrica infrastructure spend, both of which can reshape cash generation. Explore the alternative viewpoints.
Explore 2 other Centrica fair value estimates, including one that suggests as much as 39% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Centrica research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Centrica. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Centrica's overall financial health at a glance.
Looking For More Investment Ideas Beyond Centrica?
If you want to stress test your Centrica thesis, compare it with other businesses that have different risk profiles and cash flow patterns. The Simply Wall St Screener can help you quickly filter for stocks that fit the type of balance sheet strength, income profile or valuation setup you care about most.
- For investors who prize resilient balance sheets and steady fundamentals, scan our list of solid balance sheet and fundamentals (9 results) to see which businesses line up with that preference.
- If your focus is on finding quality at a reasonable price, weigh Centrica against a broader opportunity set using the 16 high quality undervalued stocks and see how other companies stack up on fundamentals.
- For readers building an income focused portfolio, compare Centrica's cash return profile with the 6 dividend fortresses and spot which payouts look most compelling for further research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com