


EN
Is Narrowed Earnings Guidance Altering The Investment Case For Otter Tail (OTTR)?
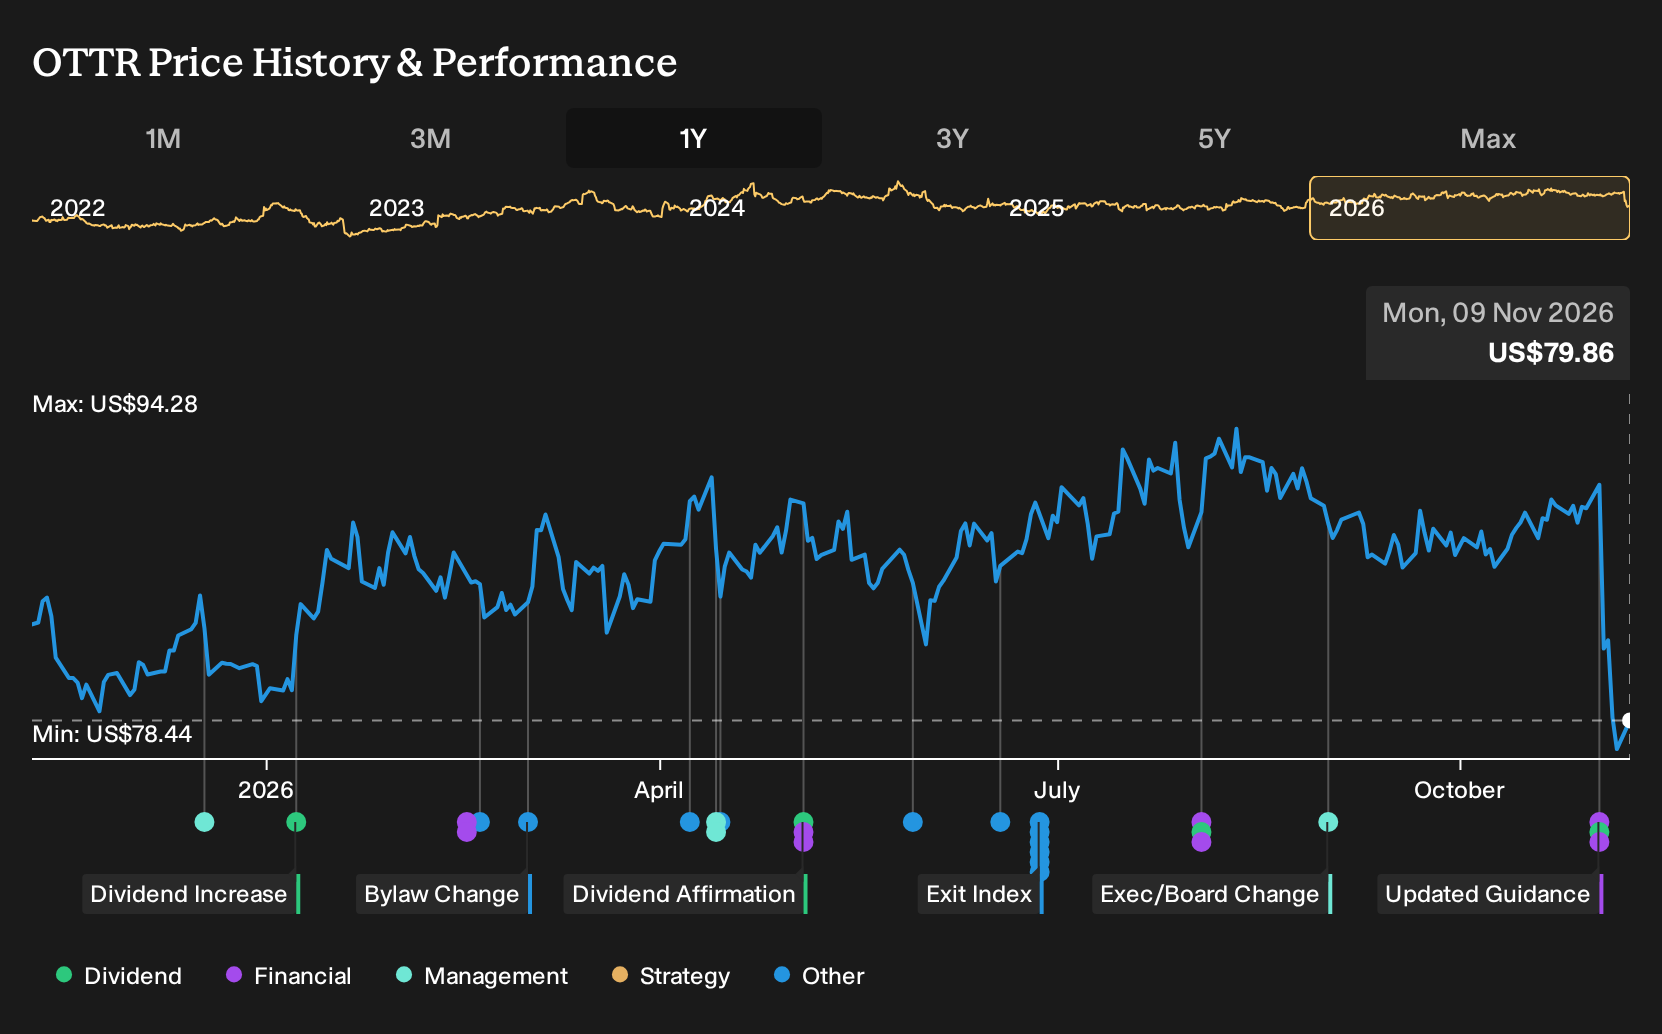
- Otter Tail reported third quarter 2026 revenue of US$320.51 million and net income of US$59.46 million, and reaffirmed but narrowed full year diluted EPS guidance to a midpoint within the US$3.89 to US$4.19 range.
- The firm’s nine month 2026 results show revenue of US$1,001.92 million and a lower earnings base compared with the prior year, which places greater emphasis on cost control, capital spending choices and the affirmed dividend of US$0.5775 per share declared for December 2026.
- The focus now shifts to how Otter Tail’s tightened 2026 earnings guidance shapes the existing utility led investment narrative already in place.
Compare Otter Tail’s reaffirmed earnings outlook and dividend stance with a curated group of utilities by scanning the 42 power grid technology and infrastructure stocks aligned with similar grid and infrastructure themes.
Otter Tail Investment Narrative Recap
To own Otter Tail, you need to be comfortable with a utility led story in which regulated electric returns, a long resource plan and a multi segment model offset more volatile Plastics earnings. The analyst consensus narrative on Simply Wall St focuses on execution of a US$1.9b electric capital program and large load growth, which remain operational priorities.
The narrowed 2026 EPS guidance range indicates that management still expects the plan to hold, even with a lower earnings base year to date. That matters because the key near term catalyst is consistent delivery from the Electric segment, while the biggest risk remains pressure on cash flows and margins if Plastics pricing or legal related cash uses worsen.
The most relevant update for that story is the reaffirmed 2026 diluted EPS guidance midpoint within US$3.89 to US$4.19. Holding that outlook after third quarter results, where earnings were lower than a year ago, indicates that Otter Tail is still planning around its current capex, large load and renewables agenda rather than resetting expectations.
For investors, the practical question is whether this guidance and the December 2026 dividend of US$0.5775 per share appear achievable given weaker year to date profitability, the PVC related settlements and debt levels highlighted in recent assessments. Execution against the rate base plan, combined with discipline on Plastics volumes and pricing, will be important in determining how that guidance holds up.
What The Long Range Otter Tail Forecast Implies
Otter Tail's long range analyst scenario points to US$1.4b in revenue and US$202.6 million in earnings by 2029, built on an assumed 2.6% yearly revenue growth rate and an earnings increase of about US$7.5 million from the US$195.1 million earned today.
Uncover how Otter Tail's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community bracket Otter Tail between about US$72 and US$91 per share, which already shows how far apart individual views can sit. When you set that beside unresolved PVC legal cash uses, rising short interest and the large capex and renewables plan, you are looking at a spread of opinions worth exploring in detail.
Explore another Otter Tail fair value estimate, including one that suggests up to 9% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Otter Tail research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Otter Tail. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Otter Tail's overall financial health at a glance.
Looking for more investment ideas beyond Otter Tail?
If Otter Tail has you rethinking how you balance income, value and resilience, it can help to widen the lens and compare it with other companies that share some of the same strengths you might be looking for.
- For investors who want income to feel more predictable, consider scanning a curated list of higher yielding payers with resilient cash flows using the 6 dividend fortresses.
- If value and balance sheet strength sit at the top of your checklist, line up Otter Tail against a list of solid balance sheet and fundamentals (25 results) to see which businesses pair financial resilience with solid fundamentals.
- When you want to hunt for potential mispriced opportunities off the beaten path, broaden your watchlist with a 19 high quality undiscovered gems that screens for quality metrics many investors may be overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com