


EN
Will Earnings And ESOP Filing Change United Fire Group (UFCS) Stock Narrative
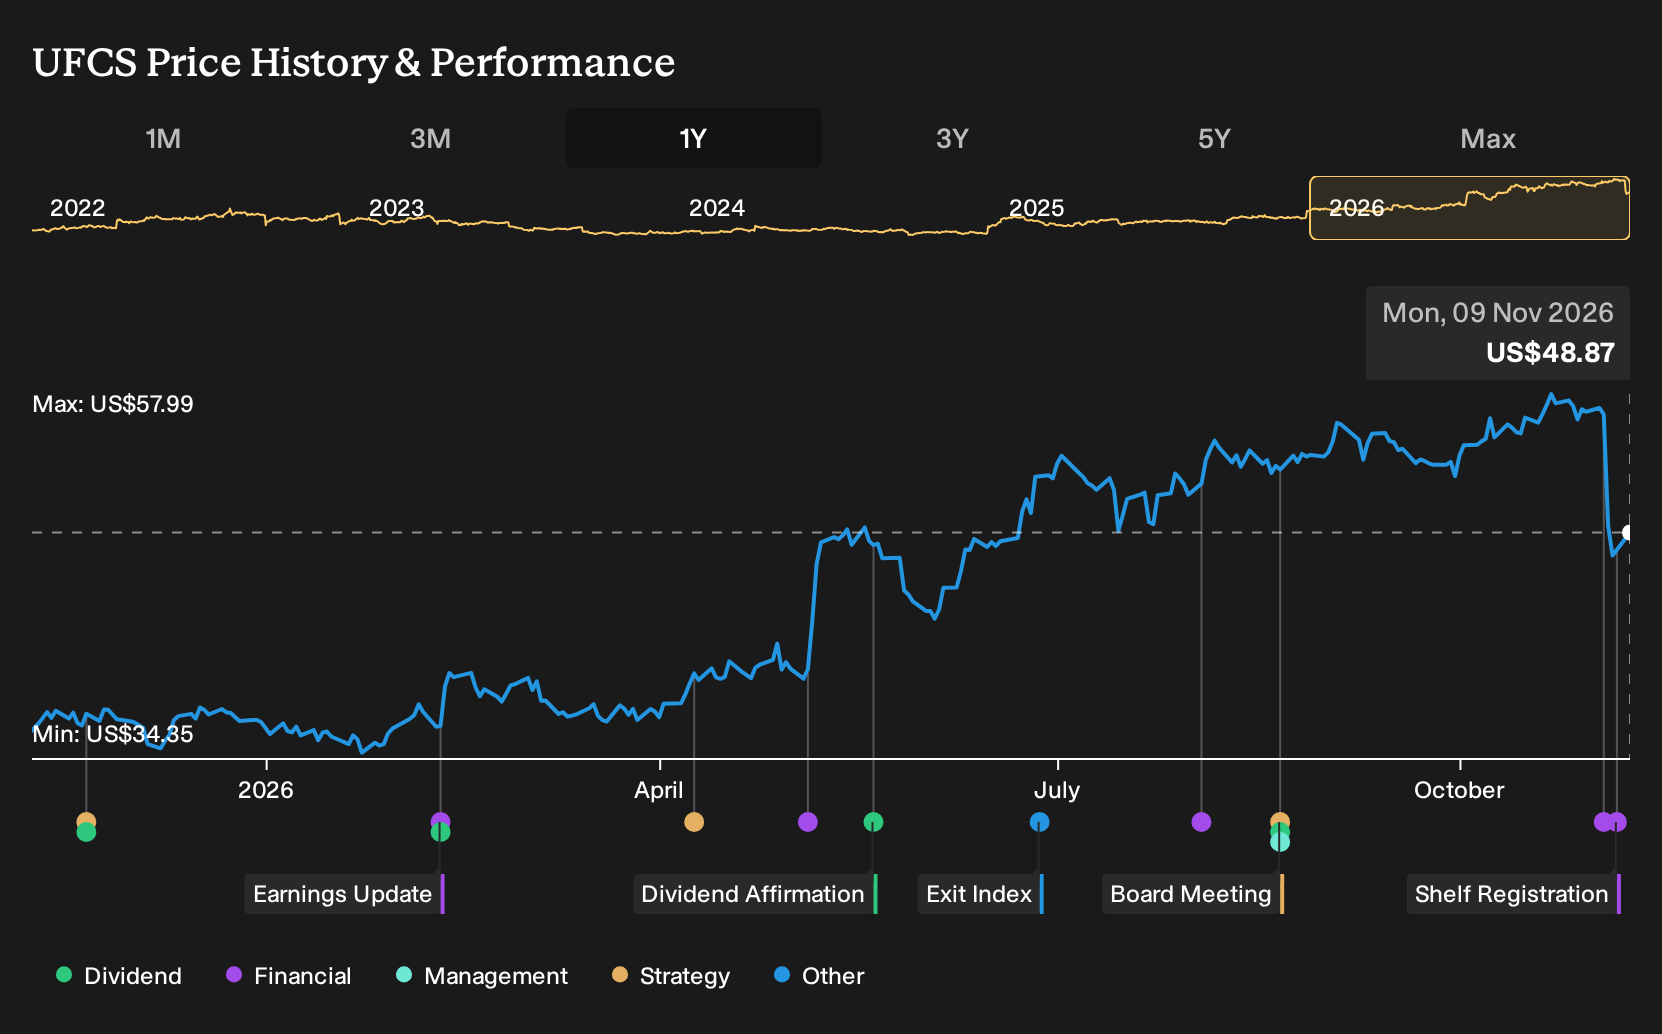
- United Fire Group recently reported third quarter 2026 net income of US$35.09 million with diluted EPS from continuing operations of US$1.34, alongside nine month net income of US$98.5 million and EPS of US$3.78.
- The company also filed a US$19.66 million shelf registration for 415,114 common shares tied to an ESOP offering, which highlights how capital raising and employee ownership are being used together to support its operating and compensation plans.
- The next step is an assessment of how United Fire Group’s investment narrative aligns with the latest earnings profile and the ESOP focused shelf registration.
United Fire Group Investment Narrative Recap
To own United Fire Group, you need to be comfortable with a property and casualty insurer that leans on underwriting discipline, expense efficiency and investment income to support returns, as captured in the analyst consensus Narrative on Simply Wall St. In the near term, the story turns on whether renewal pricing and loss ratios can stay tight enough to offset any moderation in rate momentum.
In the short term, the key catalyst is execution on underwriting quality and cost control, while the biggest risk is a sharp upswing in catastrophe losses or competitive pressure that weakens margins. The latest quarter does not look like a turning point, so the overall thesis and risks remain largely intact for now.
The most relevant development is the third quarter 2026 earnings update, where United Fire Group reported US$35.09 million in profit and diluted EPS from continuing operations of US$1.34. Over nine months, income of US$98.5 million and EPS of US$3.78 provide a clearer snapshot of the current earnings power behind the stock.
Those figures sit alongside catalysts and risks already flagged for the business, including competitive pressure in commercial lines and reinsurance, execution on technology upgrades and the potential for higher catastrophe losses. For investors, the central question is whether this earnings profile provides enough buffer if renewal rates soften or catastrophe activity lifts the combined ratio.
United Fire Group's current earnings are US$141.0 million and analysts expect revenue to grow by 17.9% per year, reaching US$2.4b of revenue and US$93.4 million of earnings by 2029, which implies an earnings decline of about US$47.6 million from today rather than an increase.
Uncover why United Fire Group's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your United Fire Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for United Fire Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Fire Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond United Fire Group?
Once you have a handle on United Fire Group, it can help to compare it with a few different styles of opportunities so you see where it fits in your portfolio.
- If you want potential upside with smaller companies that already have resilient finances, scan through the 11 elite penny stocks with strong financials and see which ones match your risk tolerance.
- For investors who care most about quality at a reasonable price, start with the 33 high quality undervalued stocks and look for businesses with cash generation and balance sheets that suit your goals.
- If capital preservation comes first and you prefer smoother ride candidates, filter for the 30 resilient stocks with low risk scores that offer lower risk scores and let you build around a steadier base.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com