


EN
Is Eldorado Gold (TSX:ELD) Below Fair Value Following Stronger Earnings And Lower 2026 Guidance?
Why Eldorado Gold is back on investors’ radar after mixed Q3 news
Eldorado Gold (TSX:ELD) just reported sharply higher net income and earnings per share for the third quarter of 2026, while at the same time cutting its full year production outlook for gold and other metals.
The mixed Q3 update landed alongside a sharp 5.10% 1 day share price return, pushing Eldorado Gold to CA$52.8 after a strong 17.31% 7 day share price move, while the 34.86% 1 year total shareholder return and very large 3 year total shareholder return suggest longer term momentum remains firmly in play, even after a recent 30 day and 90 day share price pullback.
Scan Eldorado Gold's peers reacting to the same commodity crosswinds by reviewing the 34 elite gold producer stocks, which is now drawing fresh attention from investors.
The sharp earnings jump, softer production outlook, and recent surge in Eldorado Gold now raise a sharper question. Is the bigger share price move already in the rearview mirror, or does valuation still hint at more room above?
Most popular Eldorado Gold narrative: 19% undervalued
At a last close of CA$52.8 versus a fair value of CA$65.31, the analyst consensus Narrative on Simply Wall St sees Eldorado Gold trading at a clear discount while anchoring that view in detailed production and cash flow assumptions, all run through an 8.43% discount rate.
The transition of Skouries from construction to producing its first copper gold concentrate in early September 2026 and targeting commercial production in Q4 2026 introduces a long life, low to negative cost asset that could lift Eldorado Gold’s margins and support higher earnings once full revenue recognition begins.
The ramp-up of McIlvenna Bay after first copper concentrate in June 2026 and first zinc concentrate in July 2026, with management aiming for commercial production in Q3 2026 and a cash flow positive profile by late 2026, adds new copper and zinc streams that can broaden revenue and support cash generation.
See why 47 investors see Eldorado Gold as 19% undervalued.
Result: Fair Value of CA$65.31 (UNDERVALUED)
Still, the Eldorado Gold narrative can crack if Skouries and McIlvenna Bay face further cost overruns or if persistent inflation keeps group cash costs elevated.
Find out about the key risks to this Eldorado Gold narrative.
Another view on Eldorado Gold’s valuation
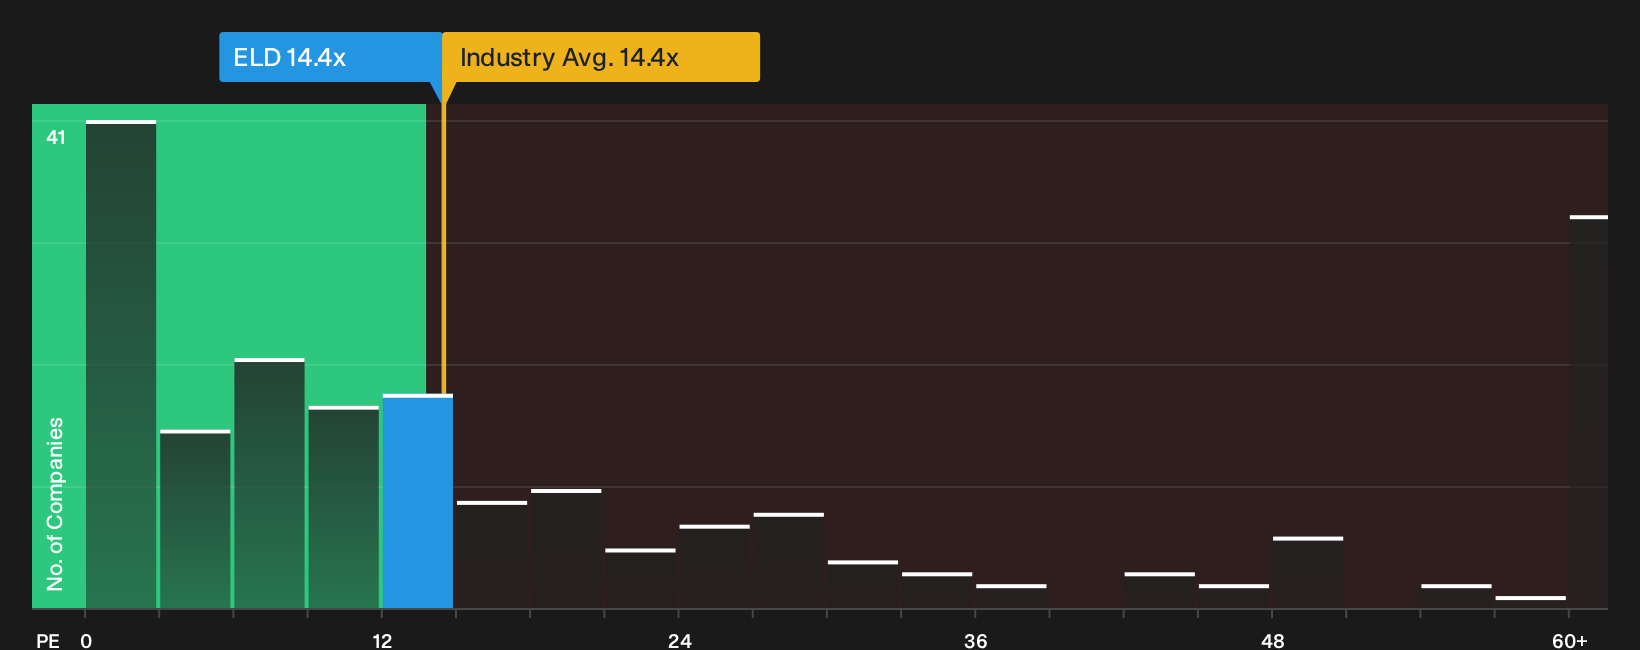
The Simply Wall St fair value workup leans bullish on Eldorado Gold, yet the simple P/E check tells a different story. At 14.4x earnings, the stock trades above both peer averages at 11.3x and the Canadian Metals and Mining group at 13.7x, even while the fair ratio sits at 20.2x.
In practice, that means the share price already bakes in richer expectations than many comparable miners, but still leaves a gap to the fair ratio that could either close through earnings catching up or the multiple moving. For anyone weighing that trade off, the question is whether this premium feels like a margin of safety or a margin of error.
To see how this simple earnings yardstick stacks up against a fuller valuation breakdown, including the fair ratio, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of optimism and worry around Eldorado Gold feels familiar, do not sit on the fence. Instead, pull up the full breakdown of risks and rewards and weigh the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Eldorado Gold?
You have already done the hard part by digging into Eldorado Gold. Do not stop there when a broader watchlist could sharpen every allocation decision you make.
- Target bargain opportunities by scanning companies that combine quality fundamentals with softer pricing through the 6 high quality undervalued stocks.
- Strengthen your income stream by reviewing a curated set of higher yielding payouts inside the 3 dividend fortresses.
- Protect your downside first by focusing on businesses screened for resilience and lower risk profiles via the 9 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com