


EN
Revenue Growth But Net Loss Has The MannKind Stock Case Changed
- MannKind reported Q3 2026 revenue of US$101.87 million and a net loss of US$23.22 million, compared with revenue of US$82.13 million and net income of US$7.99 million in the prior year quarter.
- The shift from profit to loss occurred even as nine month revenue rose to US$301.42 million from US$237.01 million. This highlights that higher operating costs or other expenses are weighing on MannKind’s earnings profile.
- We will examine how MannKind's investment narrative holds up in the context of higher revenue alongside a move from profit to loss.
MannKind Investment Narrative Recap
MannKind is still an execution story. To stay invested, you need to believe the higher Q3 2026 revenue of US$101.87 million and nine month revenue of US$301.42 million can eventually cover the current loss profile. The near term catalyst is whether Afrezza, Furoscix and Tyvaso DPI can collectively absorb rising R&D and SG&A without further widening losses.
The biggest risk right now is simple. Costs tied to product launches and pipeline work could stay elevated, which would keep MannKind in the red and limit balance sheet flexibility. This quarter’s shift from profit to loss reinforces that risk but does not appear to change the core product led thesis.
The analyst consensus narrative on Simply Wall St leans heavily on Afrezza’s lifecycle expansion, Furoscix ReadyFlow and Technosphere partnerships as the operational drivers. In that context, the Q3 2026 earnings release matters less for the top line, which is growing, and more for how long management plans to keep funding this build out at the current expense level.
Q3’s reported net loss of US$23.22 million, and nine month loss of US$58.87 million, keeps attention on cash needs and on the timing of any move toward sustained profitability. For you as a shareholder, the key question after this update is whether MannKind can turn these same products into better operating leverage before funding or competitive risks become more pressing.
MannKind's narrative projects US$549.9 million revenue and US$33.5 million earnings by 2029. This projection is based on an assumption of 11.8% yearly revenue growth and an earnings increase of about US$77.1 million from earnings today, which currently reflect a US$43.6 million loss.
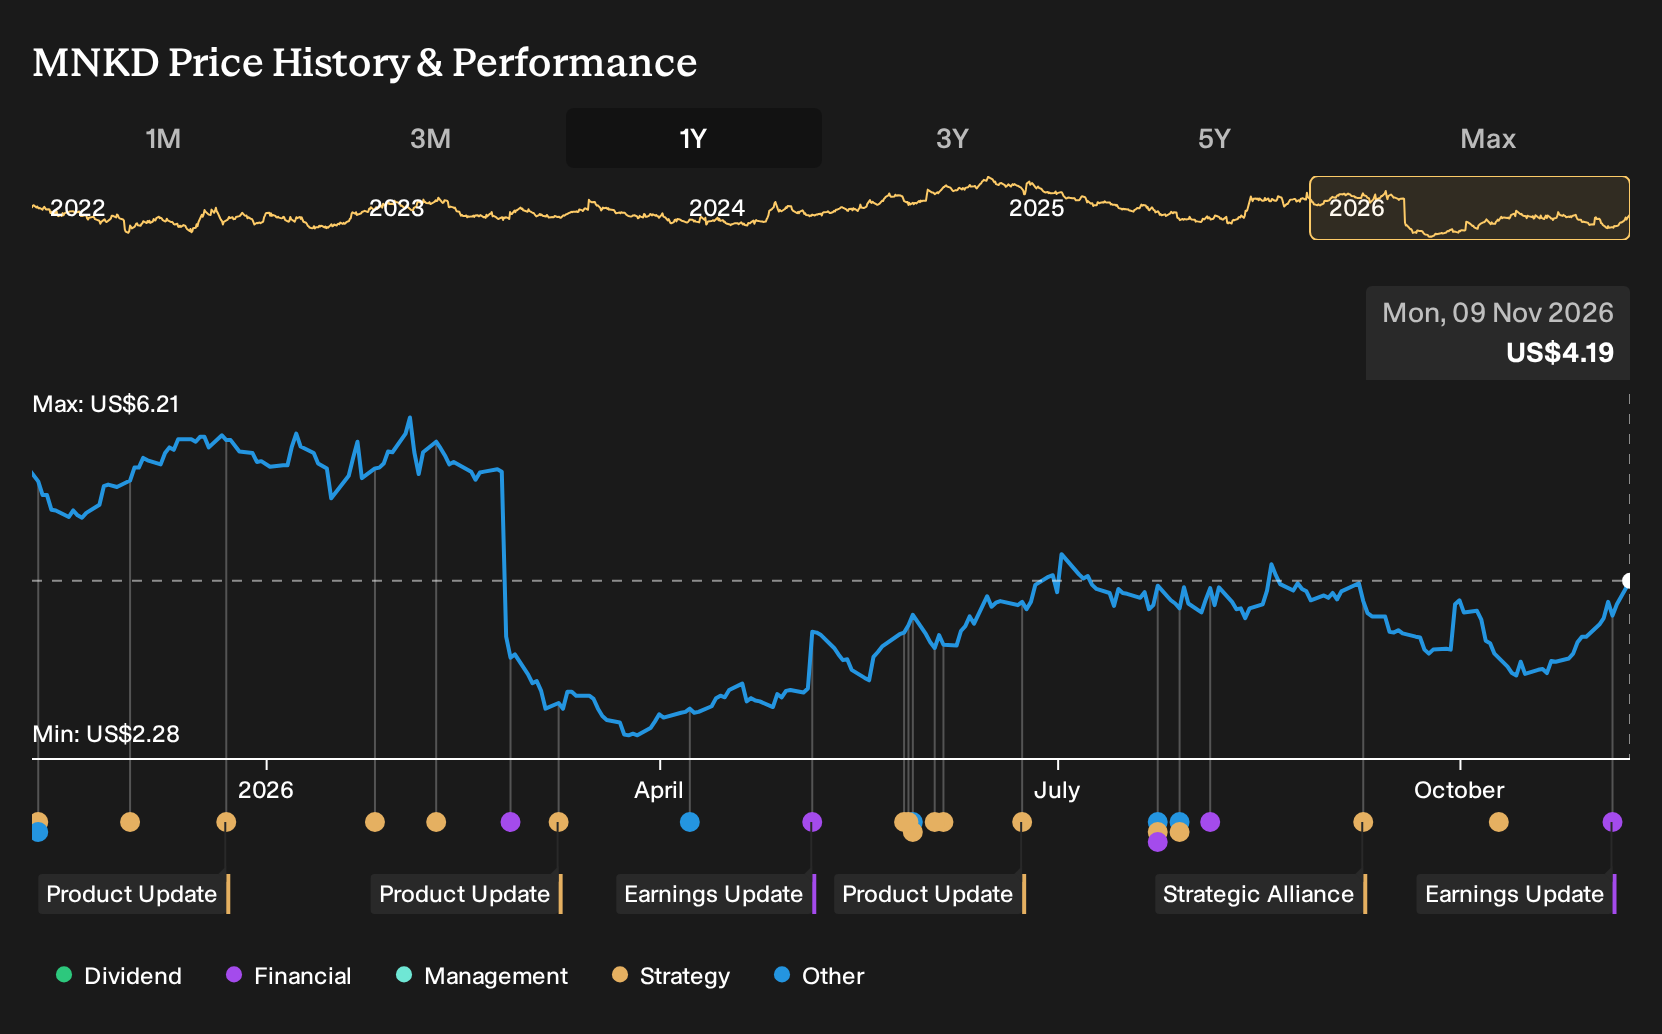
Uncover why MannKind's fair value indicates a 90% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view around MannKind focuses on payer access rather than product traction. The most pessimistic analysts were working off slower revenue growth of 6.9% a year and earnings of about US$82.8 million by 2029 before this Q3 update. That is far below the bullish US$33.5 million baseline and shows how far opinions can diverge. Use this earnings release as a prompt to compare these contrasting forecasts and assess which outlook you consider more realistic.
Explore 2 other MannKind fair value estimates, including one that suggests it could be worth just $4.18.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own analysis.
- A great starting point for your MannKind research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MannKind. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MannKind's overall financial health at a glance.
Looking For More Investment Ideas Beyond MannKind?
If MannKind has you thinking more broadly about where to put fresh capital, it can help to scan a wider field of opportunities with different risk and income profiles.
- If capital preservation is top of mind, start with a basket of steadier businesses through a 30 resilient stocks with low risk scores that prioritizes resilient balance sheets and lower volatility.
- For investors hunting for quality at a discount, cast a wider net across a 33 high quality undervalued stocks that filters for strong fundamentals at prices that look more conservative.
- If you want ideas that the market may be overlooking, scan a 19 high quality undiscovered gems that focuses on under-the-radar stocks with solid financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com