


EN
Ferrovial (BME:FER) Could Be 10% Undervalued Following Scrip Dividend And Stock Split
What Ferrovial’s scrip dividend and stock split mean for shareholders
Ferrovial (BME:FER) has lined up two shareholder focused moves: a €600 million interim scrip dividend and a 1 to 1.1976 stock split or significant stock dividend, both scheduled around early November 2026.
Recent interest around Ferrovial has arrived after a mixed year for investors. The share price is at €54.04 after a strong 30 day share price return of 21.17%, even though the 90 day share price return declined 4.89% and the year to date share price return is down 2.35%. At the same time, the 1 year total shareholder return of 1.38% and 5 year total shareholder return of 125.08% point to a much stronger long run experience as the newly announced scrip dividend and stock split reshape expectations around future income and liquidity.
Scan how Ferrovial’s capital return moves compare with other companies offering 215 dividend fortresses, which are designed to reward income focused investors.
Ferrovial appears to be a solid infrastructure operator offering both highways and airports, and it is now introducing a scrip dividend and stock split. At €54.04, is that apparent strength already fully reflected in the price?
Most Popular Narrative: 10% Undervalued
Ferrovial’s analyst consensus Narrative on Simply Wall St points to a fair value of €59.81, compared with the latest close at €54.04. That gap reflects how analysts weigh long dated concessions, construction exposure and funding risks in one coherent story.
The current valuation implies the share price does not fully reflect the cash flow potential of Ferrovial’s North American tolling assets, capital recycling program and planned shareholder returns, so the stock embeds a discount to this narrative’s view of fair value.
Recycling over €1b from Heathrow and AGS Airports into new projects while still ending H1 2026 with about €1.3b net cash excluding projects, together with planned 2024 to 2026 dividends of €2.2b, indicates capacity to fund growth and shareholder distributions without equity issuance, which can support earnings per share and cash flow yields.
See why 9 investors see Ferrovial as 10% undervalued.
Result: Fair Value of €59.81 (UNDERVALUED)
Still, the Ferrovial story can unravel quickly if New Terminal One cost issues deepen or if I 24 and I 285 require more equity than planned.
Find out about the key risks to this Ferrovial narrative.
Another view on Ferrovial’s valuation
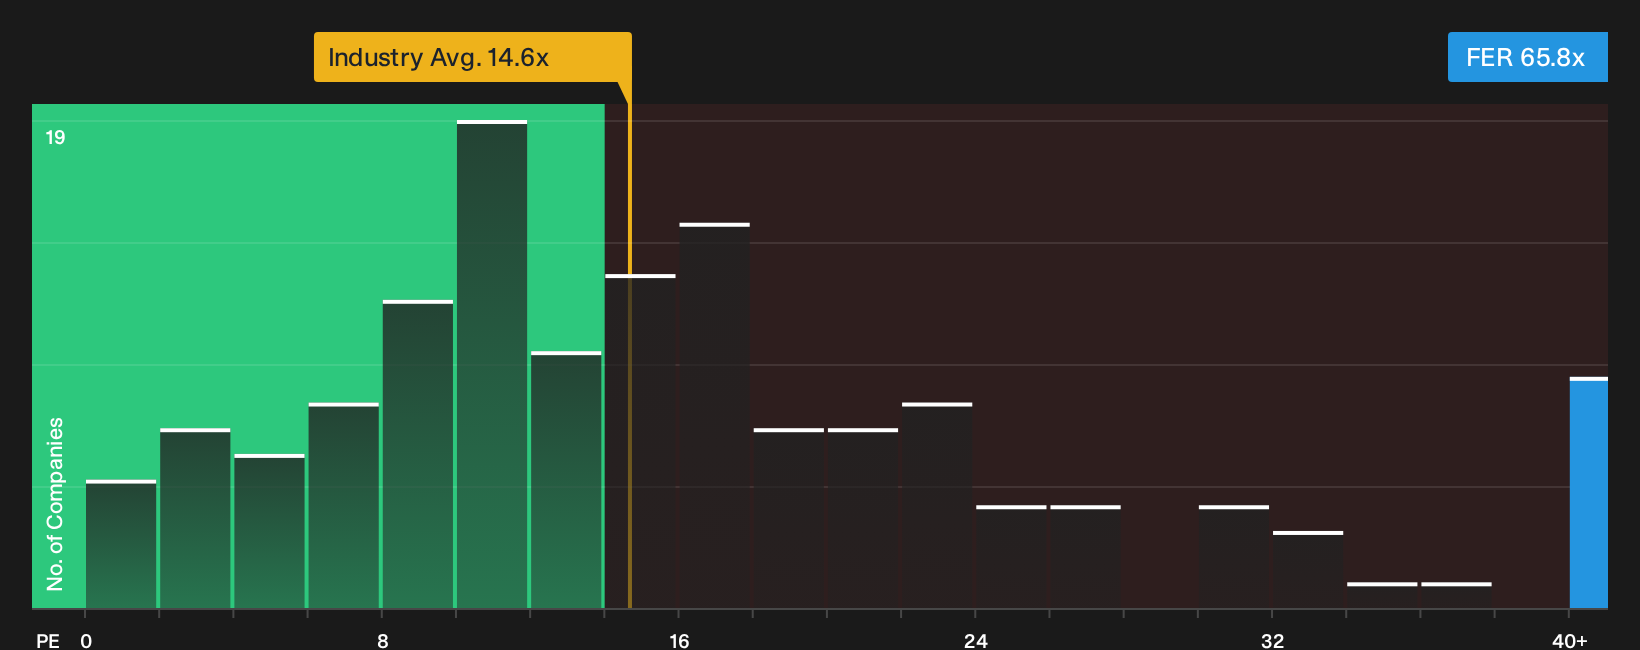
On earnings multiples, Ferrovial looks anything but cheap. The stock trades on a P/E of 65.8x, while the European construction group average sits at 14.7x and its peer set sits at 23.6x. The Simply Wall St fair ratio sits at 26.9x, which highlights how much optimism is already in the price.
If the share price were to drift closer to that fair ratio, holders would feel that adjustment directly in returns. The question for you is whether Ferrovial’s concessions story justifies staying so far above both sector norms and that 26.9x marker.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Ferrovial’s valuation and dividends are one thing; your own judgement built on the full data is another. Act while the details are fresh in your mind and weigh both sides of the story using the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Ferrovial?
If Ferrovial has sharpened your focus on quality, use this momentum. Line up your next watchlist candidates now instead of waiting for the crowd.
- Target potential mispricing by scanning companies that combine stronger fundamentals with attractive valuations through the 206 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (194 results) that can better withstand shocks and still fund future plans.
- Spot opportunities others might miss by combing through a 572 high quality undiscovered gems before attention and capital rush in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com