


EN
3 Great Undervalued Stocks To Own In November 2026
With Federal Reserve governor Christopher Waller openly backing another rate hike and even floating a larger December move if inflation data stays hot, investors face a market that keeps repricing risk. Higher borrowing costs can pressure lofty valuations, yet they also spotlight companies where cash generation looks strong relative to the share price. This article highlights three stocks that screen as attractively priced on cash flows.
The three examples that follow are only a small sample of what screens as undervalued on cash flows, since the full filter surfaced 421 more companies with similarly interesting cash generation profiles that are not covered here. To identify and analyze those additional ideas yourself, go straight to the Undervalued Stocks Based On Cash Flows screener.
China Tower (SEHK:788)
Overview: China Tower runs telecom towers and related digital infrastructure across China, earning recurring fees from long-term site, power, and maintenance services.
Operations: Almost all revenue, around CN¥98.1b, comes from telecommunications tower infrastructure services and related businesses across mainland China.
Market Cap: HK$158.2b
For this screener, China Tower matters because its long-term leasing model ties directly into recurring cash generation, and the analyst consensus Narrative on Simply Wall St argues that ongoing network build-out is central to that story.
"The ongoing rollout and densification of 5G infrastructure in China, now reflected in China Tower adding 364,000 new 5G base stations in 2025 and 187,000 in the first half of 2026 with over 95% delivered through co-location, continues to support leasing demand that can help sustain tower and DAS revenue and support earnings."
What happens if one subtle shift in customer spending patterns changes how much of that infrastructure build actually flows through to margins?
That margin question is exactly what the full narrative for China Tower unpacks. It shows where China Tower’s cash story could accelerate, stall, or quietly decouple from 5G buildout headlines.

Nitto Boseki (TSE:3110)
Overview: Nitto Boseki is a Japanese materials group that supplies glass fiber for electronic materials, medical reagents, textiles, chemicals, and insulation products.
Market Cap: ¥451.3b
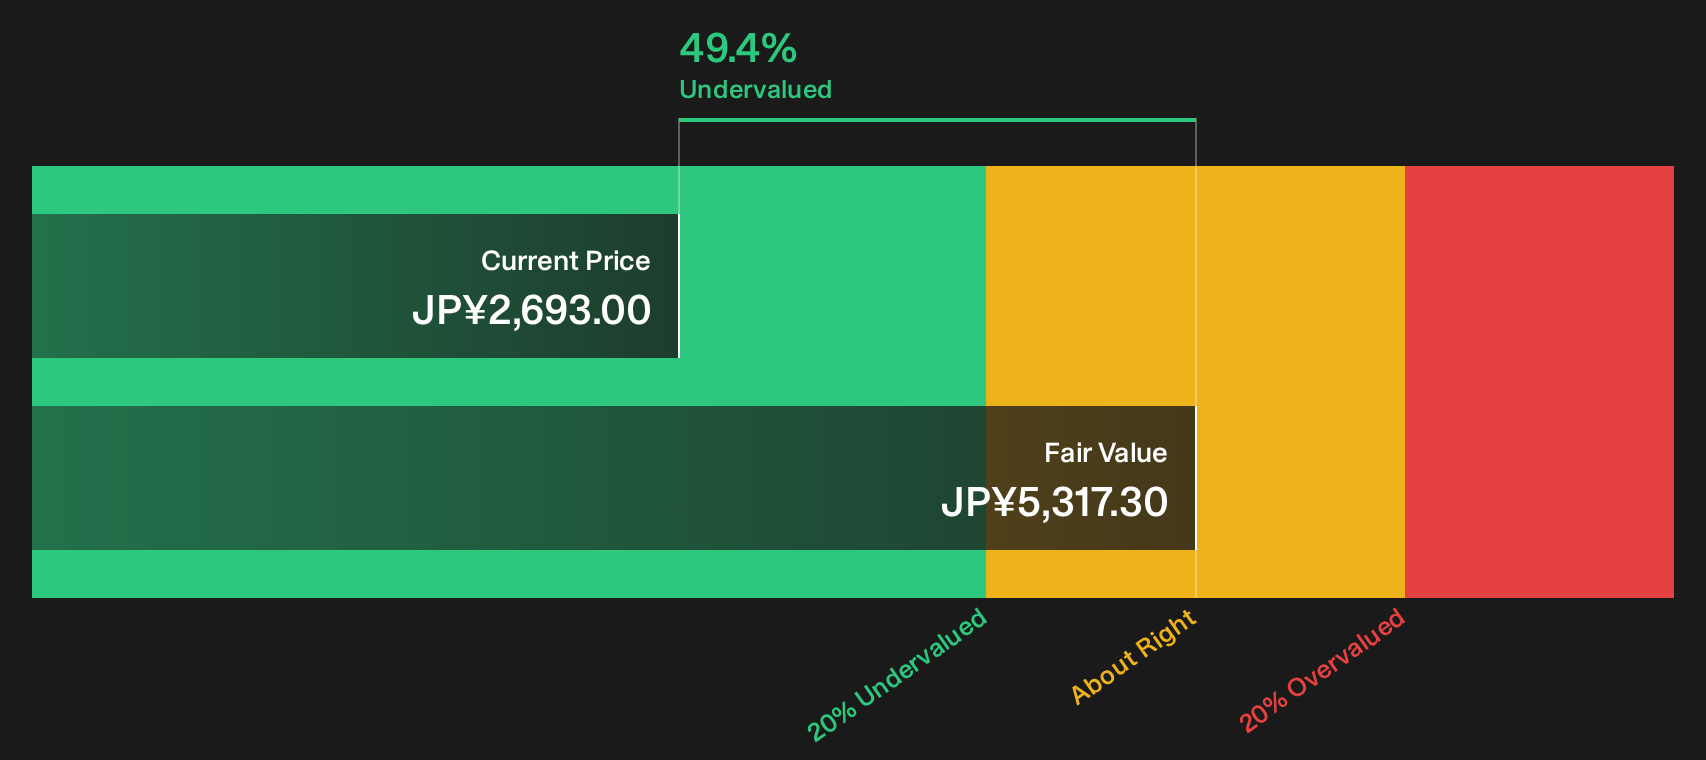
Nitto Boseki fits this cash flow screen because its glass fiber for electronic materials tends to produce steady, contract-like earnings, yet the shares trade well below SWS DCF value. Recent triple digit earnings growth adds weight to that cash story, depending on how one unseen pressure shapes the resilience of that electronics cash stream.
That unseen pressure is exactly what the 4 key rewards and 2 important warning signs (2 are major!) weighs up, so you can see whether Nitto Boseki’s cash engine is accelerating or quietly stalling.
Tieto Oyj (HLSE:TIETO)
Overview: Tieto Oyj provides software, Banking as a Service platforms and digital engineering services to regulated industries that value reliable recurring cash flows.
Operations: The business generates about €693 million from Tech Consulting, €568 million from Banktech, €263 million from Indtech and €231 million from Caretech, before eliminations of €26 million.
Market Cap: €2.0b
Tieto Oyj matters for this cash flow focused screen because its Banktech platforms produce contract based subscription income, and the analyst consensus Narrative on Simply Wall St frames that stream as a key support for valuation grounded in discounted future cash generation.
"The rapid increase in AI and advanced analytics adoption across client industries is reflected in Tieto Oyj's contract pipeline, where embedded AI is highlighted in offerings such as Lifecare Smart Notes and Banktech financial crime prevention, which can influence future revenue and support margins as customers move from pilots to scaled deployments."
The real test comes if one shift in long term client demand alters how much of that Banktech backlog actually converts into high margin cash.
If that shift is what you care about, the full narrative for Tieto Oyj shows where Tieto Oyj’s cash engine could be accelerating, masking risk, or quietly decoupling from expectations.

Seeking Fresh Alternatives Before They Fly
Markets move fast, and the best breakout ideas rarely stay under the radar for long. Scan fresh momentum, spot dropping risk, and position before the crowd, then act now.
- Hunt for high quality opportunities that still look overlooked using the curated 572 high quality undiscovered gems before those stories get fully caught in the spotlight.
- Target durable income streams with the hand picked 215 dividend fortresses while yields remain attractive and prices have not fully priced in their resilience.
- Ride structural demand in essential materials by reviewing the focused 16 top copper producer stocks before renewed momentum in the sector filters through to valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com