


EN
Genesis Energy (NZSE:GNE) Could Be 8% Below Fair Value Following Leadership Reshuffle
Genesis Energy (NZSE:GNE) is reshaping its top team after new non discrimination rules split its retail and wholesale arms, creating separate Chief Customer Officer and Chief Commercial Officer roles while removing the Chief Revenue Officer position.
Recent trading shows a mixed picture for Genesis Energy, with a 1-day share price return of 1.69% at NZ$2.41 and a 7-day gain of 0.84%. The 30-day and 90-day share price returns declined 2.03% and 7.31% respectively. Total shareholder return reached 6.42% over one year and 29.12% across three years, indicating that short-term momentum has cooled, while longer-term holders have still seen positive overall value including dividends.
Scan beyond Genesis Energy and evaluate other regulated utilities adjusting their executive playbooks with our hand picked 202 resilient stocks with low risk scores.
Genesis Energy now looks like a solid utility reshaping its leadership to fit tighter rules. The real question is whether that steady profile is already fully captured in today’s NZ$2.41 share price.
Most Popular Narrative: 8% Undervalued
On the analyst consensus Narrative on Simply Wall St, Genesis Energy screens as modestly undervalued, with a fair value of NZ$2.61 against the recent NZ$2.41 close, and that gap rests on a detailed build out and cash flow plan.
The capital program to FY32 combines around NZ$2b of growth capex in renewables and firming assets with up to NZ$800m of stay in business spend. It is supported by operating free cash flow, a NZ$400m equity raise and continued Dividend Reinvestment Plan issuance, and is designed to grow Genesis Energy’s asset base and earnings capacity while supporting credit metrics that can help keep the cost of capital and net profit outcomes in balance.
See why 21 investors see Genesis Energy as 8% undervalued.
Result: Fair Value of NZ$2.61 (UNDERVALUED)
Still, this story can change quickly if Huntly’s shift away from baseload gas reduces firming revenue faster than expected, or if Kupe earnings fall short of projections.
Find out about the key risks to this Genesis Energy narrative.
Another View: Genesis Energy Looks Expensive On Earnings
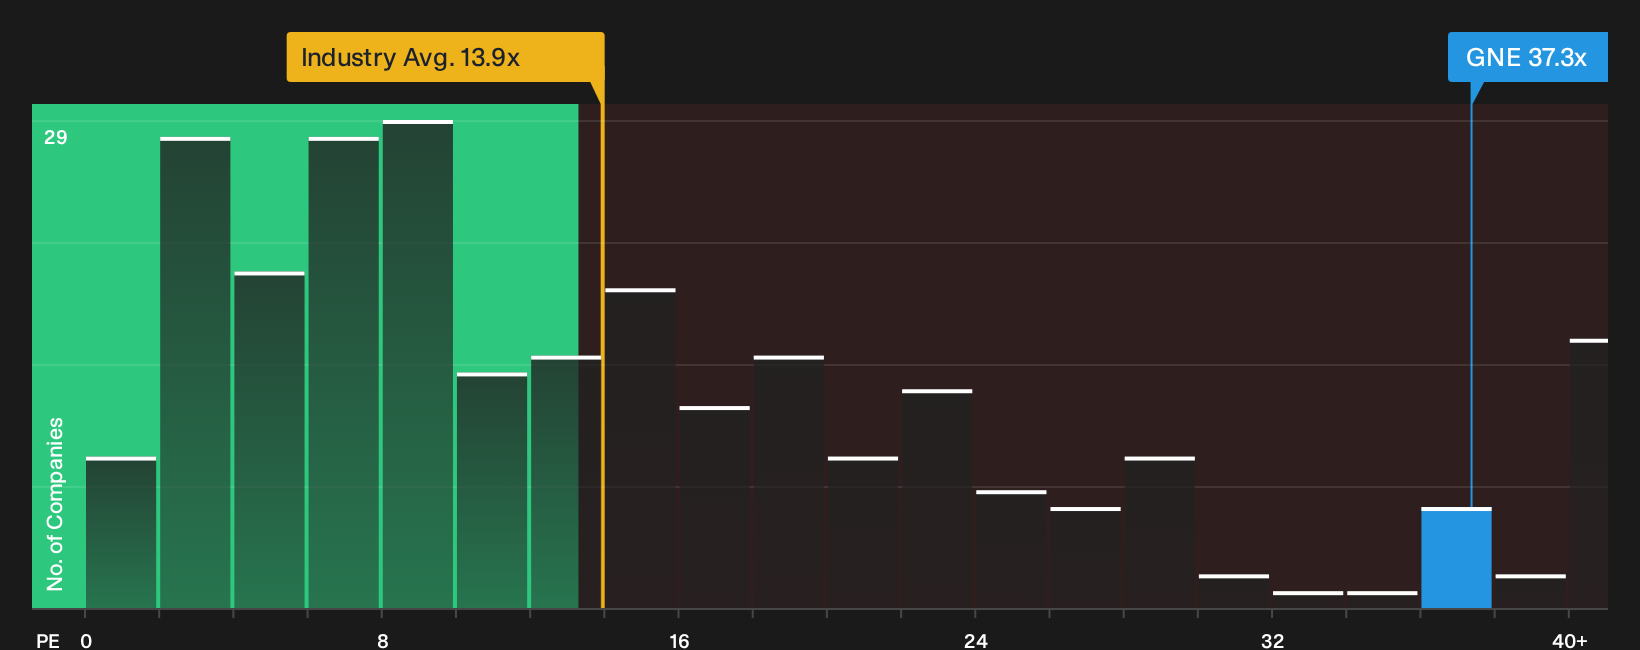
While the Simply Wall St cash flow work points to a fair value of NZ$2.61, the earnings multiples tell a tighter story. Genesis Energy trades on a P/E of 37.2x, compared with 20.4x for peers, 13.9x for the global electric utilities group, and a fair ratio of 28.6x that the market could move toward. That gap points to valuation risk if sentiment shifts back toward more typical earnings multiples, so how much weight do you want to give the premium?
See what the numbers say about this price in more detail with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Genesis Energy story points both ways, with risks and rewards pulling against each other. Move quickly and test the data against your own expectations. To pressure test your view against a fuller breakdown of both sides, start with these 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Genesis Energy?
If Genesis Energy has sharpened your thinking, do not stop here. The real edge comes from comparing several well filtered opportunities side by side.
- Spot potential mispricings early by scanning a curated set of quality companies with upside potential using the 206 high quality undervalued stocks.
- Strengthen your income stream by focusing on resilient payers with higher yields through the 215 dividend fortresses.
- Stay on the front foot by tracking financially robust businesses with clean balance sheets using the list of solid balance sheet and fundamentals (194 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com