


EN
Norwegian Cruise Line Holdings (NCLH) Lifted Guidance, Is It Fully Priced?
Earnings, Guidance And Leadership Moves Put Norwegian Cruise Line Holdings In Focus
Norwegian Cruise Line Holdings (NCLH) just delivered third quarter results showing higher revenue and net income than a year earlier, along with fresh guidance that points to high occupancy and a detailed finance leadership transition.
Norwegian Cruise Line Holdings now trades at US$18.43, with a 1 month share price return of 18.37%. This contrasts with a year to date share price decline of 19.10% and a 3 year total shareholder return of 40.69%. This suggests that momentum has picked up recently even as investors are still weighing longer term risk and recovery narratives around the business.
Spot fresh momentum in Norwegian Cruise Line Holdings, then scan a curated group of travel and leisure plays with resilient fundamentals using our 19 high quality undiscovered gems.Norwegian Cruise Line Holdings now has rising earnings, fresh guidance and an incoming CFO, yet the share price is still below its year to date starting point. Is this a strong operator at a fair price today?
Most Popular Narrative: 1% Undervalued
Norwegian Cruise Line Holdings closed at $18.43 compared with a fair value estimate of $18.63 in the analyst consensus Narrative on Simply Wall St. This frames the upside as modest and heavily tied to execution on its turnaround plan.
Structural SG&A and marketing savings, including more than US$500m of identified cost actions since 2024 and an expected 15% reduction in salary and benefits, are already reflected in lower adjusted NCC ex fuel guidance and provide a foundation for future net margin and EPS improvement if revenue stabilizes.
See why 55 investors see Norwegian Cruise Line Holdings as 1% undervalued.
Result: Fair Value of $18.63 (ABOUT RIGHT)
Still, the narrative around Norwegian Cruise Line Holdings can be knocked off course if high leverage keeps interest costs heavy or if yield pressure at the core Norwegian brand lingers longer than analysts expect.
Find out about the key risks to this Norwegian Cruise Line Holdings narrative.
Another View: Cash Flows Paint A Harsher Picture
While Norwegian Cruise Line Holdings looks roughly in line with analyst fair value estimates, the SWS DCF model lands in a very different place. On that cash flow view, the shares at $18.43 trade well above an estimated value of $2.74, which points to limited cushion if future performance disappoints.
That gap between earnings based fair value and cash flow based fair value raises a simple question for you as an investor. Which set of assumptions feels more realistic for Norwegian Cruise Line Holdings over the long haul: the current profit profile, or the cash generation implied by the DCF model.
Look into how the SWS DCF model arrives at its fair value.
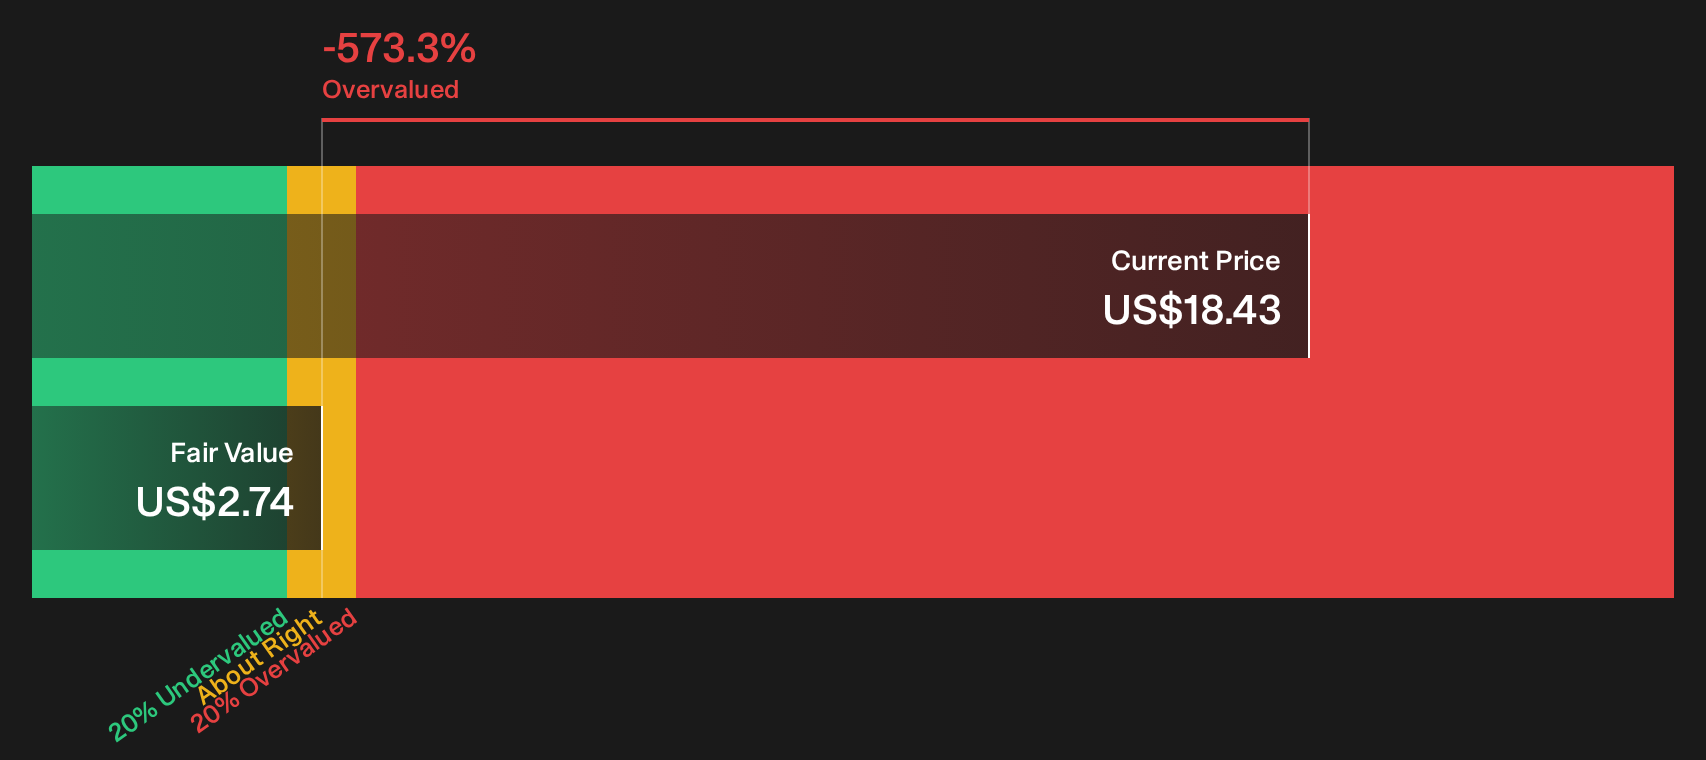
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Norwegian Cruise Line Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether this mix of fresh earnings, guidance and valuation noise makes Norwegian Cruise Line Holdings look attractive or overhyped right now? Act quickly, stress test the upside and downside, then weigh the 3 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Norwegian Cruise Line Holdings?
Norwegian Cruise Line Holdings might be on your radar now, but you give up a lot of potential ideas if you stop your research here.
Use the Simply Wall St screener to spot other opportunities that match your style before the crowd catches on.
- Target quality at a discount by scanning a focused list of companies that combine strong fundamentals with attractive pricing using the 33 high quality undervalued stocks.
- Prioritize staying power and resilience by zeroing in on businesses with healthier finances through the list of solid balance sheet and fundamentals (25 results).
- Lean into stability and income potential by reviewing companies with robust payout profiles via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com