


EN
Raised Guidance Could Be A Big Moment For L3Harris Stock (LHX)
- L3Harris Technologies recently issued US$1.0b of senior notes split between 5.200% 2029 and 5.400% 2032 maturities, and reported third quarter 2026 results with sales of US$6,060m and net income of US$632m.
- The business paired raised full year 2026 earnings guidance with US$121m of new U.S. Army radio production orders, reinforcing demand for its communications portfolio and highlighting active balance sheet management through refinancing of 2026 and 2027 notes.
- We will now see how L3Harris Technologies' stronger guidance and recent Army radio orders could reshape the existing investment narrative.
Scan other defense and communications contractors showing similar funding and contract momentum by reviewing the curated 30 resilient stocks with low risk scores, often preferred by investors who care about resilient balance sheets and steadier risk profiles.
L3Harris Technologies Investment Narrative Recap
L3Harris Technologies appeals to shareholders who buy into a long pipeline of defense electronics work converting into steady orders, revenue and cash generation. According to jack_LTH_stocks, an investor in the Simply Wall St Community, the story hinges on execution across missile, space and communications programs, not just broader defense spending. The near term catalyst is continued order flow and backlog conversion supporting the higher 2026 revenue and EPS guidance.
The main operational risk is timing and funding of government programs, which can affect how quickly that backlog turns into cash. Recent US$1.0b note issuance appears to be housekeeping around 2026 and 2027 maturities rather than a major shift in the short term outlook, so it does not materially change that core risk reward balance.
The US$121m Army radio orders announced on 2 November appear tightly linked to that execution story, especially around the Communications & Spectrum Dominance segment. These Low Cost Data Radio contracts tie directly into the edge communications and waveform capabilities that jack_LTH_stocks highlights as central to the long term case.
For you as a shareholder, the key question is whether L3Harris can keep turning wins like LOCODA into repeat programs that support its raised 2026 guidance while managing the higher fixed coupons on the new notes. The orders help near term revenue visibility, but program delivery, margins and any future budget delays remain important operational swing factors.
On jack_LTH_stocks’ numbers, the stock reaches a fair value of US$300.00 if L3Harris Technologies can compound revenue at 13.3% a year and eventually sustain an 8.1% profit margin. Together, these assumptions underpin the narrative’s view of stronger long term earnings power.
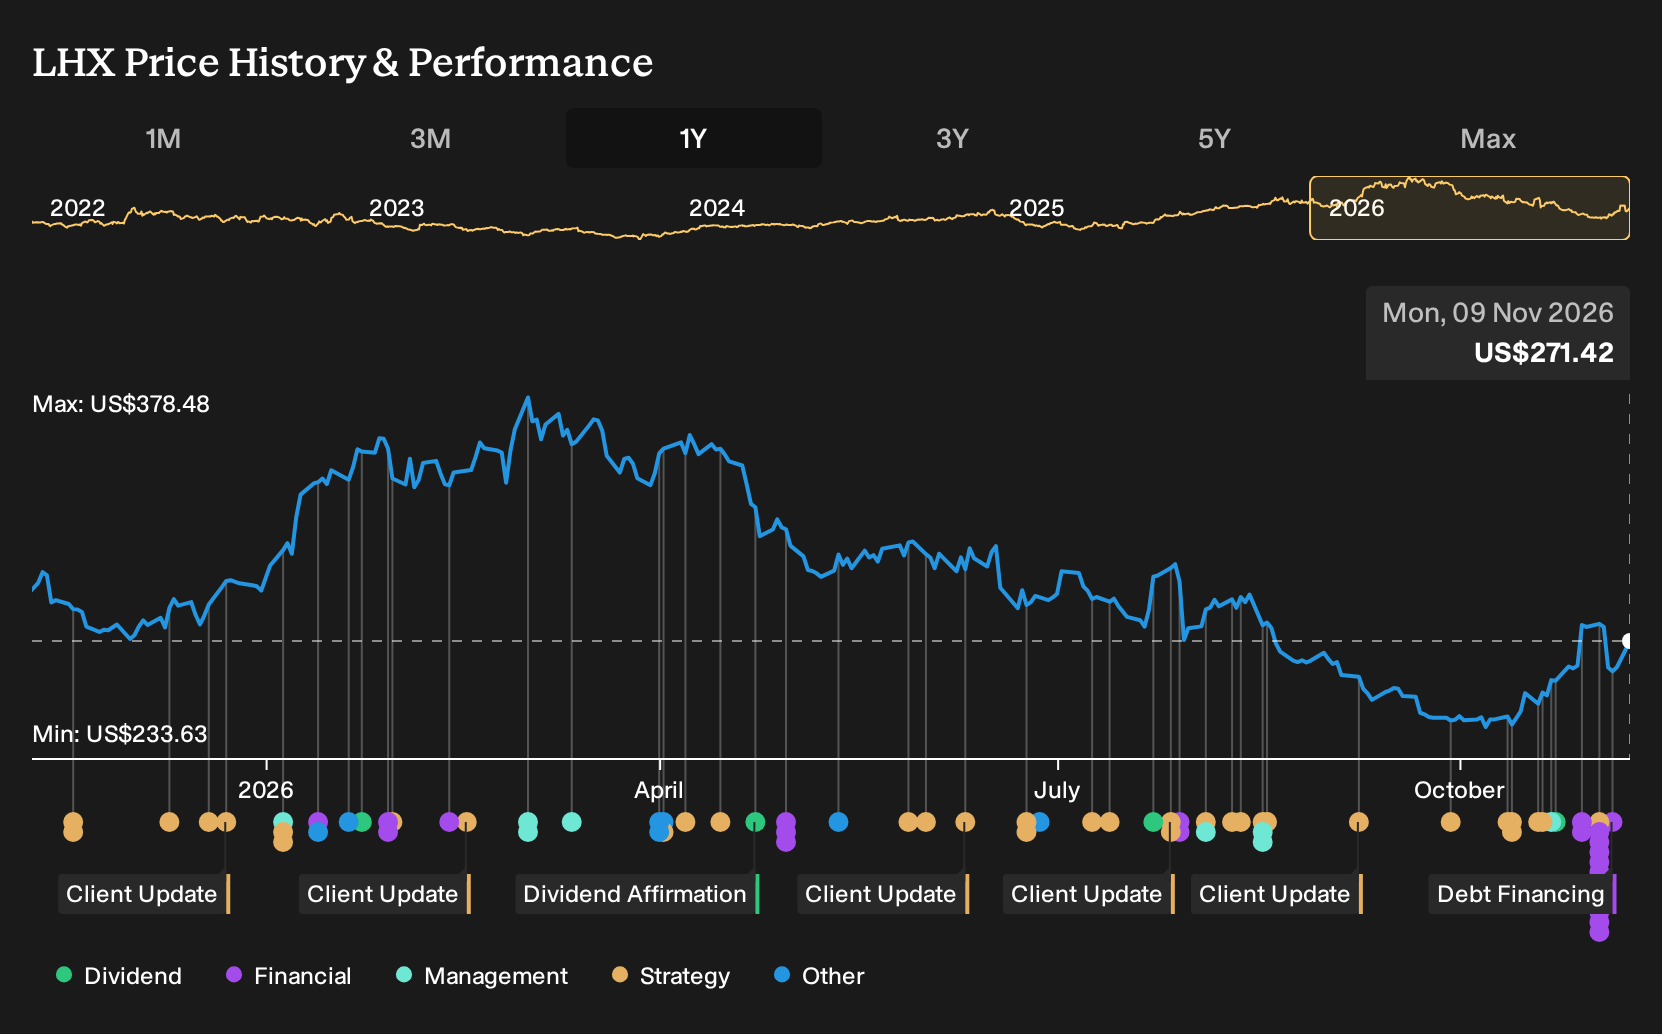
Uncover how L3Harris Technologies' fair value indicates an 11% potential upside to its current price that could narrow quickly if sentiment follows the raised 2026 guidance.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on near term orders and more on L3Harris Technologies’ missile capacity build out. Before this news, they were already modelling revenue of about US$29.4b and earnings of roughly US$3.3b by 2029. You can use those ambitious assumptions to test how much this new debt and Army radio win might reshape your own view.
Explore 3 other L3Harris Technologies fair value estimates, including one that suggests as much as 52% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your L3Harris Technologies research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for L3Harris Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate L3Harris Technologies' overall financial health at a glance.
Looking for more L3Harris Technologies sized ideas?
If the L3Harris Technologies story has sharpened your thinking, use that same framework on a wider watchlist by screening for other businesses that match your preferred mix of quality, risk and income.
- For investors who want potential upside without ignoring balance sheet strength, scan a curated 19 high quality undiscovered gems that match solid fundamentals with underfollowed stories.
- If your priority is durability through different cycles, filter for companies with stronger finances by reviewing the list of solid balance sheet and fundamentals (25 results) that can help anchor a more conservative portfolio.
- Income focused investors can concentrate on cash return potential by screening for the 6 dividend fortresses and assessing which payouts best fit their goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com