


EN
Mixed Q3 Earnings Could Be A Game Changer For Europris Stock (OB:EPR)
- Europris reported third quarter 2026 sales of NOK 3,473.01 million and net income of NOK 129.07 million, with basic EPS from continuing operations at NOK 0.79. For the first nine months of 2026, the company reported sales of NOK 10,466.77 million and net income of NOK 378.06 million, with EPS of NOK 2.31.
- The contrast between softer third quarter profits and higher net income over the first nine months of 2026 shows how Europris is balancing short term trading pressure with a longer period of improved earnings.
- The focus now turns to how Europris's investment narrative holds up when compared with softer third quarter profitability and firmer year to date earnings.
Europris Investment Narrative Recap
To stay invested in Europris, you need to be comfortable with a discount retailer that is still pushing through a Swedish turnaround while keeping its Norwegian base steady. The third quarter showed softer profitability, but the nine month figures point to earnings that held up better over a longer stretch, so the latest report does not radically change that story.
The key short term catalyst remains execution on store remodels, assortment changes and systems upgrades. The analyst consensus Narrative on Simply Wall St links these to potential improvements in revenue quality and EBIT. The biggest near term risk is that ÖoB losses and heavy Swedish investment continue to weigh on free cash flow and keep reported earnings choppy.
Among the recent information, the detailed earnings release for the third quarter and first nine months of 2026 matters most. It puts concrete numbers around how Europris is absorbing Swedish investment, with NOK 3,473.01 million in quarterly sales and NOK 10,466.77 million across nine months, alongside net income of NOK 129.07 million and NOK 378.06 million respectively.
These figures let you test the catalysts in the analyst consensus Narrative on Simply Wall St against reality. You can compare the reported net income and EPS to the idea that integration work, ERP and supply chain upgrades and joint sourcing are meant to improve margins over time. At the same time, you can keep a close eye on whether currency effects and ÖoB remodeling still represent the main operational risk.
Europris' current analyst narrative points to NOK 17.3b in revenue and NOK 1.5b in earnings by 2029, based on forecast revenue growth of 4.5% a year and an earnings increase of about NOK 640m from earnings today of NOK 860.3m.
Uncover why Europris' fair value indicates a 16% potential upside to its current price before this discount closes.
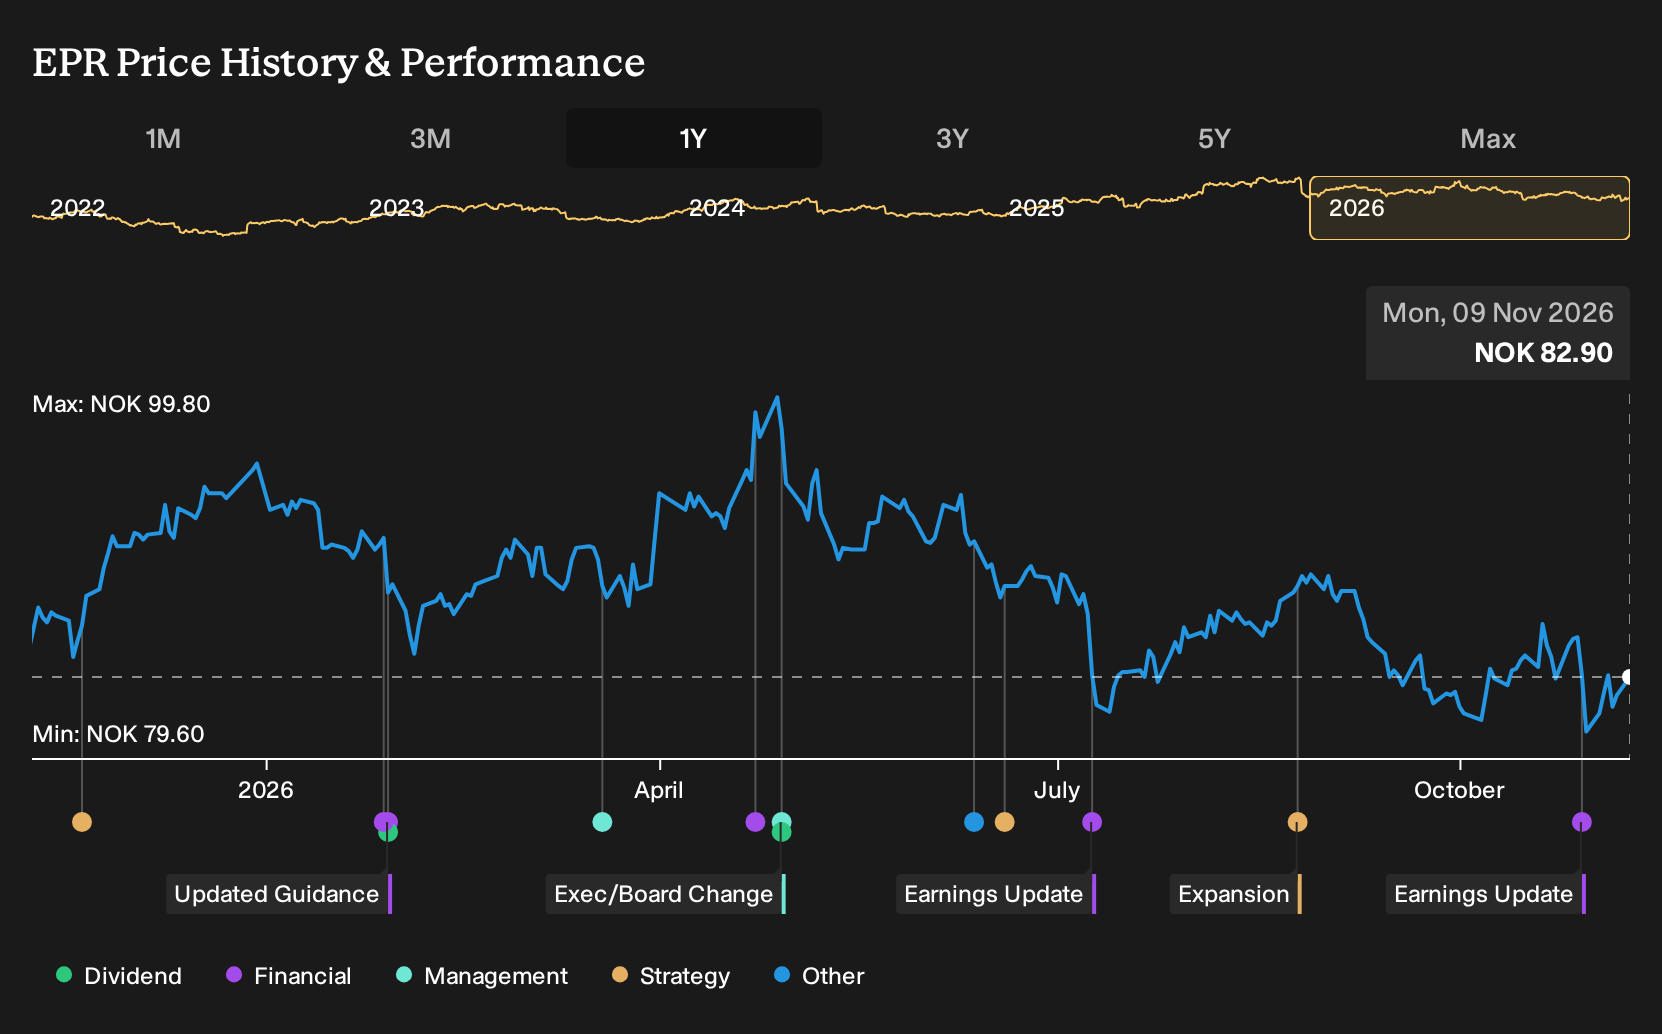
Exploring Other Perspectives
Four fair value views from the Simply Wall St Community span Europris at roughly 95.2 to 242.94, so private investors are clearly far apart on what counts as attractive. When you set that spread against currency swings and the still unfinished ÖoB turnaround, you get real questions about how earnings quality could evolve. Explore those different angles before firming up an opinion.
Explore 3 other Europris fair value estimates, including one that suggests as much as 193% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Europris research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Europris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Europris' overall financial health at a glance.
Looking for more investment ideas beyond Europris?
If Europris is already on your radar, it can help to line it up against other opportunities that share some of the same strengths. A focused stock screener lets you quickly compare balance sheets, income quality and risk across a much wider field, so you can see where Europris really fits in your portfolio.
- If capital protection matters most to you, you can filter for resilient businesses with steadier profiles through the 202 resilient stocks with low risk scores.
- For investors who care about financial strength, you can scan a list of solid balance sheet and fundamentals (194 results) to find companies that aim to pair robust finances with earnings power.
- If you like the idea of backing strong operators before the crowd arrives, you can run a 572 high quality undiscovered gems to surface companies with quality fundamentals that the market may not be fully pricing in yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com