


EN
Hornbeck Offshore Services (HOS) On Shell Deals And A Fresh Loss Looks Undervalued
Hornbeck Offshore Services (HOS) has given investors a lot to process this month. Fresh third quarter results showed higher revenue alongside a swing to a sizeable loss, arriving just days after new long term service agreements with Shell.
Those Shell contracts and the abrupt swing to a quarterly loss have arrived against a weak share price backdrop, with Hornbeck Offshore Services showing a 7 day share price return of down 16.6% and a year to date share price return of down 47.9%. This is pointing to fading momentum as investors reassess both execution risk and the earnings path from here.
Spot short term dislocations like Hornbeck Offshore Services by scanning our hand picked 33 high quality undervalued stocks with solid cash flows and balance sheets.Hornbeck Offshore Services now trades at a steep discount to both intrinsic value estimates and analyst targets after a sharp slide. Is that gap compensation for real loss risk, or has caution swung too far?
Most Popular Narrative: 59% Undervalued
Hornbeck Offshore Services last closed at $5.38 while the analyst consensus Narrative on Simply Wall St anchors on a fair value of $13, using an 8.15% discount rate and detailed revenue and earnings forecasts to justify that gap.
The current valuation implies that the market is placing limited value on Hornbeck Offshore Services already having multi-year contracts, initial cost savings and guidance for sizeable 2027 adjusted EBITDA.
See why 1 investors see Hornbeck Offshore Services as 59% undervalued.
Result: Fair Value of $13 (UNDERVALUED)
Still, the Hornbeck Offshore Services story depends on how effectively the merger is integrated and whether heavy dry dock downtime eats into margins, liquidity and the value of that US$1.9b backlog.
Find out about the key risks to this Hornbeck Offshore Services narrative.
Another View: Multiples Paint a Tougher Picture for Hornbeck Offshore Services
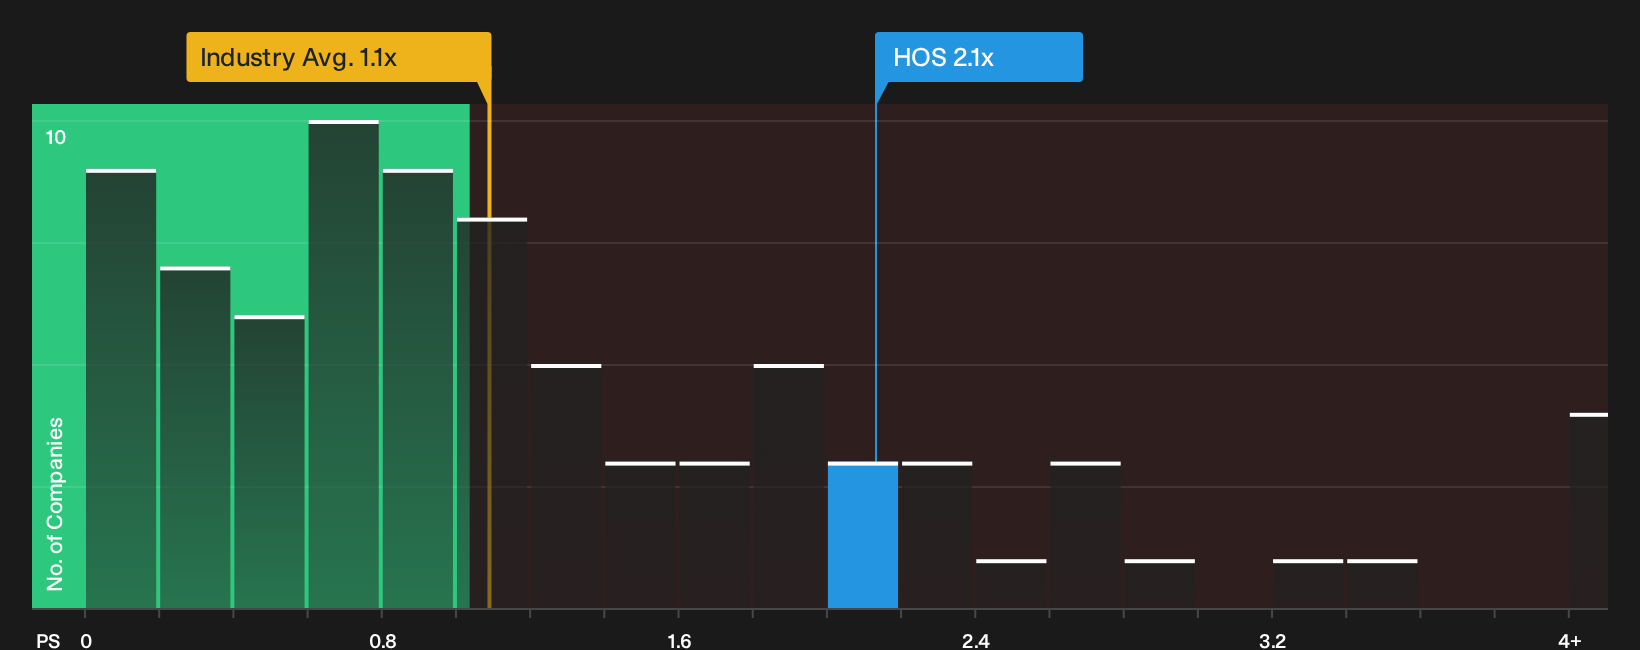
The discounted cash flow work and analyst target point to Hornbeck Offshore Services trading well below estimated value. The simple sales multiple tells a different story. HOS changes hands at a P/S of 2.1x, almost double the US Energy Services industry and peer average of 1.1x, which suggests less room for error if the growth narrative slips. Which signal carries more weight for you: the cash flow model, or what similar businesses trade on today?
To dig into how that sales ratio stacks up against what the market could move towards as a fair ratio, and what that gap might mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mood so far feels cautious, treat that as a prompt rather than a conclusion and pressure test the numbers yourself before the next move. To see what optimistic investors are focusing on, review the 2 key rewards.
Looking for more investment ideas beyond Hornbeck Offshore Services?
If Hornbeck Offshore Services has sharpened your focus, do not stop there. Broaden your watchlist with other targeted opportunities that match your risk and return preferences.
- Target potential mispricing by scanning the 19 high quality undiscovered gems that combine strong fundamentals with limited market attention.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (25 results) that highlights businesses with sturdy finances and fewer balance sheet surprises.
- Dial down volatility by assessing a 30 resilient stocks with low risk scores that filters companies with lower risk scores and more consistent profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com