


EN
Is Upgraded Earnings Guidance Altering The Investment Case For Toyota Boshoku Shares?
- Toyota Boshoku reported half year sales of JPY 1,068,337 million and net income of JPY 22,484 million, affirmed a JPY 43.00 second quarter dividend, and issued full year guidance including expected basic EPS of JPY 285.56.
- The combination of higher half year earnings, an unchanged interim dividend, and explicit full year profit targets highlights how Toyota Boshoku is balancing operating performance with consistent shareholder payouts.
- We will now look at how Toyota Boshoku's upgraded earnings outlook shapes the broader investment narrative for the business.
Compare Toyota Boshoku's mix of confirmed dividends and earnings guidance with other companies that pair reliable payouts with profit targets using our hand-picked 27 dividend fortresses
What Is Toyota Boshoku's Investment Narrative?
To own Toyota Boshoku, you need to be comfortable with a fairly capital intensive auto components group that lives or dies on execution for large global customers. The half year figures and upgraded full year guidance put operating delivery at the center of the story. Management is pointing to ¥2,110,000m in revenue and basic EPS of ¥285.56, which now frames expectations for margins, pricing power with automakers, and how efficiently the production footprint is being run.
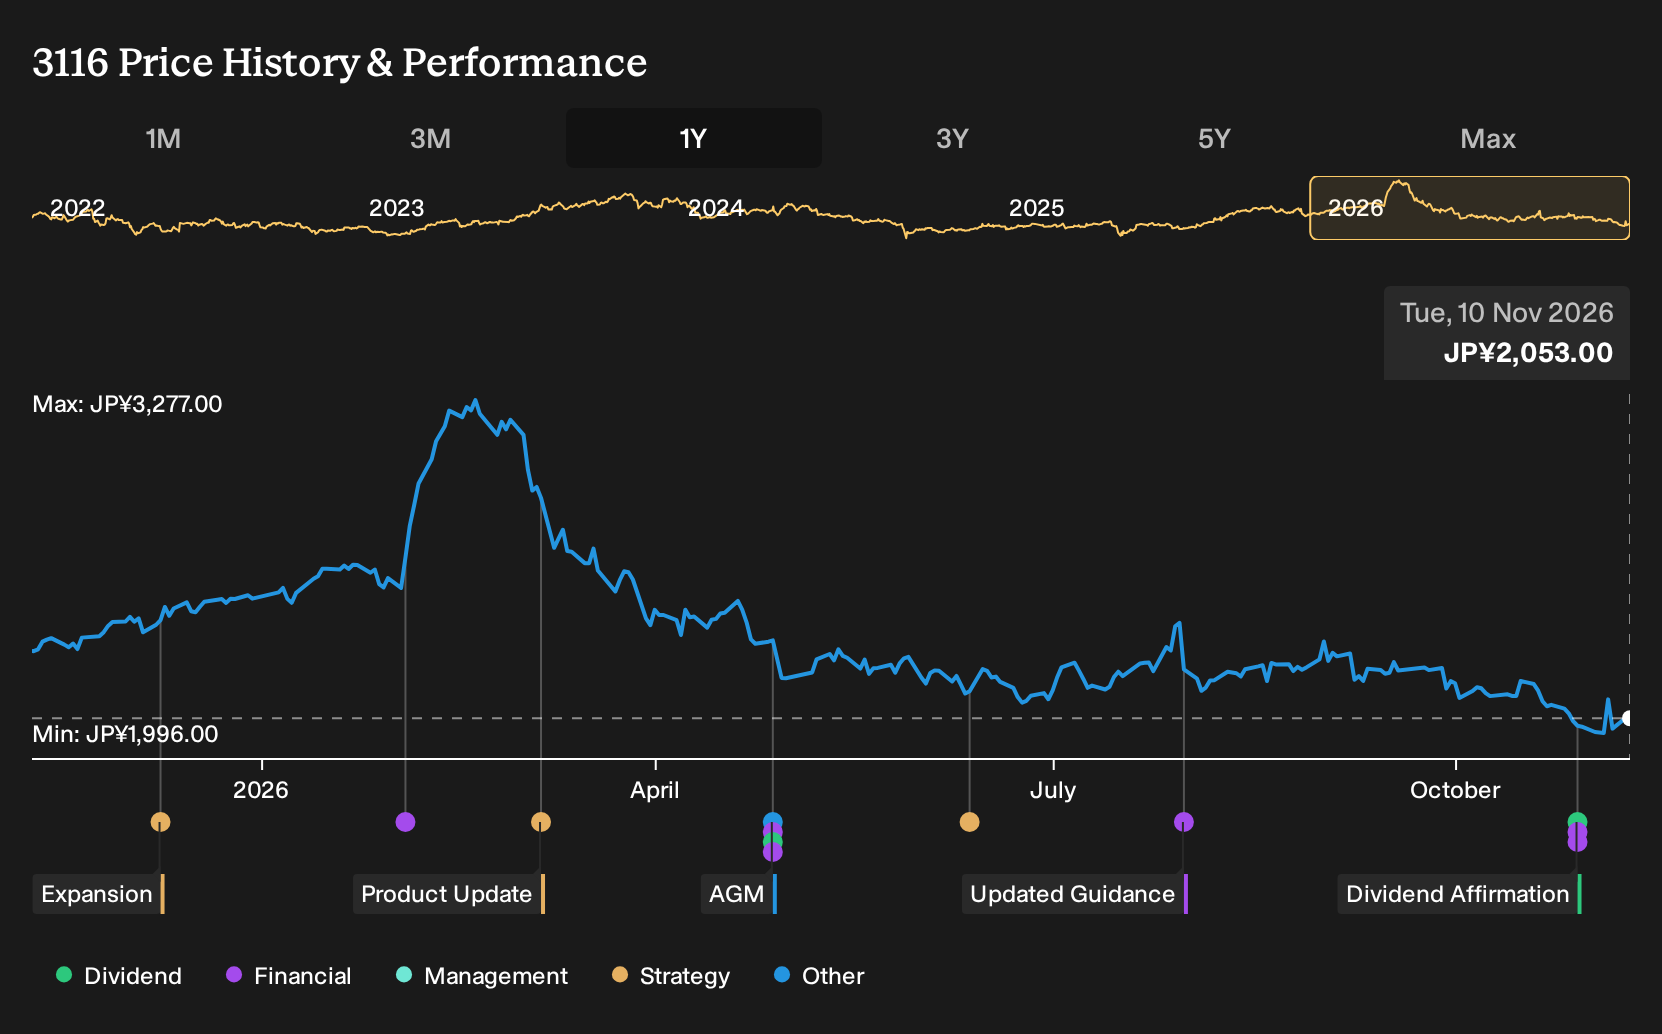
The affirmed ¥43.00 second quarter dividend fits into that picture as a signal on near term cash discipline, even with an historically unstable payout record flagged in the data. Softer share performance over 1 and 3 years shows how easily sentiment can lag the earnings line. Looking ahead, short term catalysts focus on meeting those profit targets, keeping net margins moving in the right direction, and managing an inexperienced management team through what is still a demanding supply chain set up.
Even so, there is one structural issue around Toyota Boshoku that tends to get less attention until you look closely at ...
There's only one way to know the right time to buy, sell or hold Toyota Boshoku. Head to Simply Wall St's company report for the latest analysis of Toyota Boshoku's Fair Value.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Toyota Boshoku research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Toyota Boshoku. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toyota Boshoku's overall financial health at a glance.
Looking For More Investment Ideas Beyond Toyota Boshoku?
If you want to put Toyota Boshoku in context and build a broader watchlist, it can help to scan for other businesses that match the kind of balance between earnings, income quality, and shareholder returns you are looking for.
- If you want to tilt toward pricing that looks modest relative to fundamentals, take a look at the 20 high quality undervalued stocks that pass our filters for quality and valuation.
- For readers who care most about resilient finances and less about headlines, start with the 18 resilient stocks with low risk scores that screen well on our risk checks.
- To round things out with potential outliers the market has not focused on yet, scan through the 76 high quality undiscovered gems that pair solid metrics with limited coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com