


EN
VICI Properties (VICI) Stock Still Looks Reasonable After Its $2 Billion Buyback
VICI Properties has delivered a 12.4% total return over the past 5 years while the stock has been weak over the past year, which puts a spotlight on whether its current share price lines up with the earnings power investors are paying for. With fresh headlines around a new buyback plan and shifting expectations for its rental income, the question now is how comfortably the present valuation sits against the cash flows that support those earnings.
- Over 5 years, VICI Properties has returned 12.4%, which makes today’s valuation debate less about short term moves and more about what that longer run says about the durability of its earnings base.
- Recent announcements around a multi year share repurchase plan and tenant mix changes can reshape how quickly earnings per share grow and how predictable those cash flows look to equity holders.
- The analysts covering VICI Properties have run their own numbers. See what analysts think VICI Properties's shares could be worth.
The issue now is whether the current price for VICI Properties is justified by the earnings that underpin it.
To stress test whether VICI Properties’ earnings-based valuation feels fair, it often helps to compare it with other real estate focused stocks screened for 33 high quality undervalued stocks
Is VICI Properties Still Cheap on Earnings?
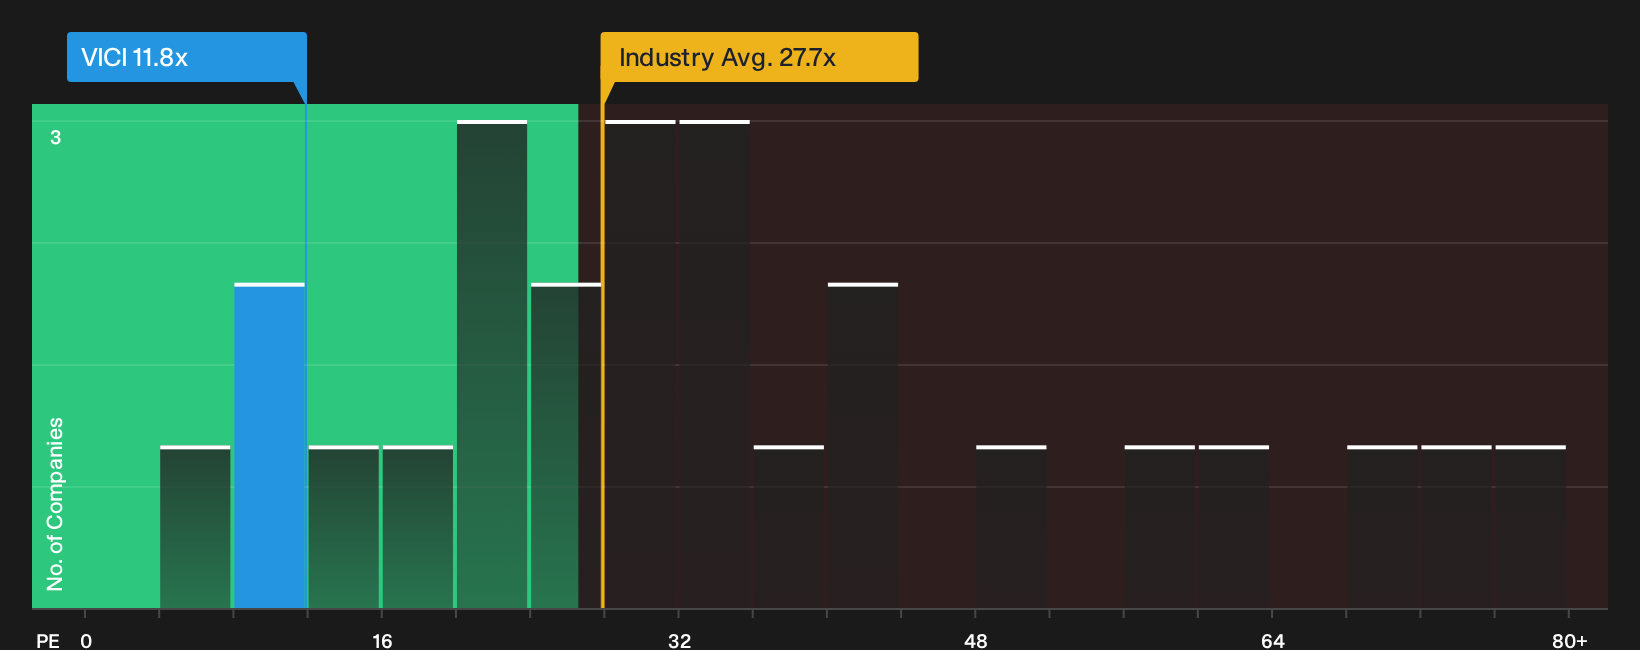
P/E makes sense for VICI Properties because earnings are a direct read across from its rental income and financing decisions. On that yardstick, VICI trades on a P/E of 11.8x, which is below the Specialized REITs group on 15.1x and well under a peer set around 33.4x. The modeled fair P/E, which weighs VICI’s profitability profile, sector, scale and risk, sits higher than where the stock changes hands. As a result, the current multiple screens as undervalued against that more tailored yardstick.
The board has approved a multi year US$2b buyback while also dealing with Caesars related lease uncertainty. The market is weighing that capital return against tenant risk and interest costs, which still leaves the P/E multiple at a discount to what the fundamentals based fair ratio would suggest. Explore the numbers behind VICI Properties's P/E valuation.
The VICI Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for VICI Properties pick up where the P/E discussion stops and spell out the earnings paths that would need to play out for the current share price to look high or low. Instead of giving you just one output number from a ratio or model, they unpack the growth, margin and cash flow expectations that sit behind it so you can watch over time whether those assumptions actually hold.
One of the top community narratives on VICI Properties: 40% undervalued
According to andre_santos, an investor in the Simply Wall St Community, VICI Properties screens as undervalued once cash flows and dividend capacity are modeled out.
"Given this assumption and the fact that VICI has a Cost of Equity of 7.50% we can calculate its fair value using a DDM valuation method..."
Discover why this Narrative puts VICI Properties at 40% undervalued.
Before acting on VICI Properties' valuation, there is one more factor to check
The numbers only tell part of the story, because the people steering VICI Properties and the way their pay is structured can strongly influence how those figures evolve over time. See who runs VICI Properties and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com