


EN
Xenon Pharmaceuticals (XENE) Stock Looks Above Fair Value Next To Book Value
Xenon Pharmaceuticals has delivered a 36.2% gain over the past three years, and recent drug pipeline updates have kept the story moving. The natural question is whether that performance is now fully reflected in its book value. For anyone tracking biotech valuations, the key issue is how a balance sheet anchored in neuroscience programs lines up with a share price that reacts quickly to trial headlines.
- Xenon Pharmaceuticals has returned 36.2% over three years, which puts real weight on whether the current share price still has support from its underlying net assets.
- With an FDA filing for azetukalner already in and multiple pain candidates moving toward Phase 2, expectations around future cash needs and potential revenue streams can influence how much of a premium investors are willing to place on the company relative to its recorded equity.
- There is a second opinion on Xenon Pharmaceuticals worth weighing. See what analysts think Xenon Pharmaceuticals's shares could be worth.
The issue now is whether Xenon Pharmaceuticals' current market value is adequately underpinned by its book value when set against the industry average.
If you want a broader watchlist of biopharma names while you assess whether Xenon Pharmaceuticals' 36.2% three year return still matches up with its book value, start with 33 high quality undervalued stocks.
Does Xenon Pharmaceuticals Look Pricey on Book Value?
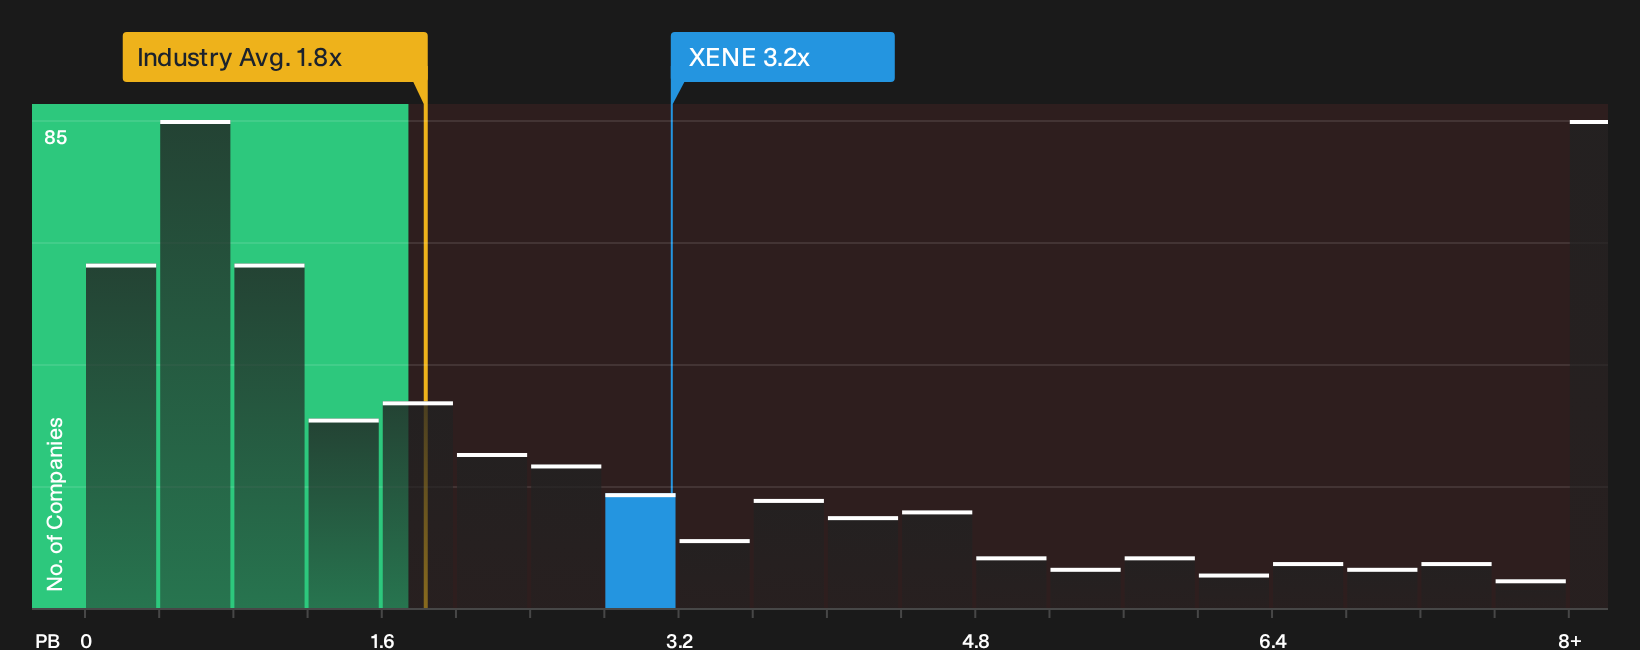
P/B suits Xenon Pharmaceuticals because the business is still loss making on earnings, so the balance sheet is the cleaner anchor. The stock trades on a P/B of 3.2x, compared with a Biotechs industry average of about 1.8x and a peer group closer to 6.2x. That puts the share price at a clear premium to the sector’s asset base, while still sitting below what some similar companies command.
Because Xenon Pharmaceuticals recently filed its azetukalner NDA and is preparing pain assets for Phase 2, investors appear willing to pay above the sector’s book value norm for that pipeline. The key question for you is whether the neuroscience portfolio and future funding needs justify a valuation that already screens as overvalued against the wider Biotechs group on P/B alone. Explore the numbers behind Xenon Pharmaceuticals's P/B valuation.
The Xenon Pharmaceuticals Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the price to book puzzle around Xenon Pharmaceuticals' shares leaves off. Each one explains which broad assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s level. It also treats fair value as a thesis that you can watch over time rather than a one day snapshot, with all content hosted on Simply Wall St's Community page.
One of the top narratives on Xenon Pharmaceuticals: 55% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"The current valuation implies that the market is heavily discounting the psychiatry program and assigning limited credit to Xenon Pharmaceuticals’ cash runway into 2029…"
Discover why this Narrative puts Xenon Pharmaceuticals at 55% undervalued.
The share price is only one piece of the Xenon Pharmaceuticals puzzle
Before you get too fixated on where Xenon Pharmaceuticals trades on book value, it is worth asking who is steering the business and how their incentives line up with yours. See who runs Xenon Pharmaceuticals and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com