


EN
3 Crude Tanker Stocks Retail Investors May Revisit After The TD3C Benchmark Dispute
The legal fight over the TD3C crude tanker benchmark has turned a niche freight index into a live risk story for anyone exposed to crude shipping, derivatives and benchmark providers. When a reference price tied to about €17.4b in contracts is questioned, investors start to ask who might be helped, who might be hurt and who is being mispriced. This article walks through three stocks from our crude oil tanker owners and operators screener that appear positively exposed to this news, and explains how the benchmark integrity debate could influence earnings quality, balance sheet resilience and perceived risk across the sector.
The stocks highlighted below are just a first cut, since the full screen surfaced 10 more companies with equally interesting crude tanker narratives that are not covered here. To go straight to the source and identify your own high conviction tanker plays, analyze the Listed Crude Oil Tanker Owners and Operators screener.
Euroholdings (EHLD)
Overview: Euroholdings provides seaborne transportation through a product tanker and two feeder containerships, moving refined fuels, manufactured goods and perishables.
Operations: The business currently generates about $23.7 million from operating container carriers, tying Euroholdings’ top line closely to freight and charter rates.
Market Cap: $32.7 million
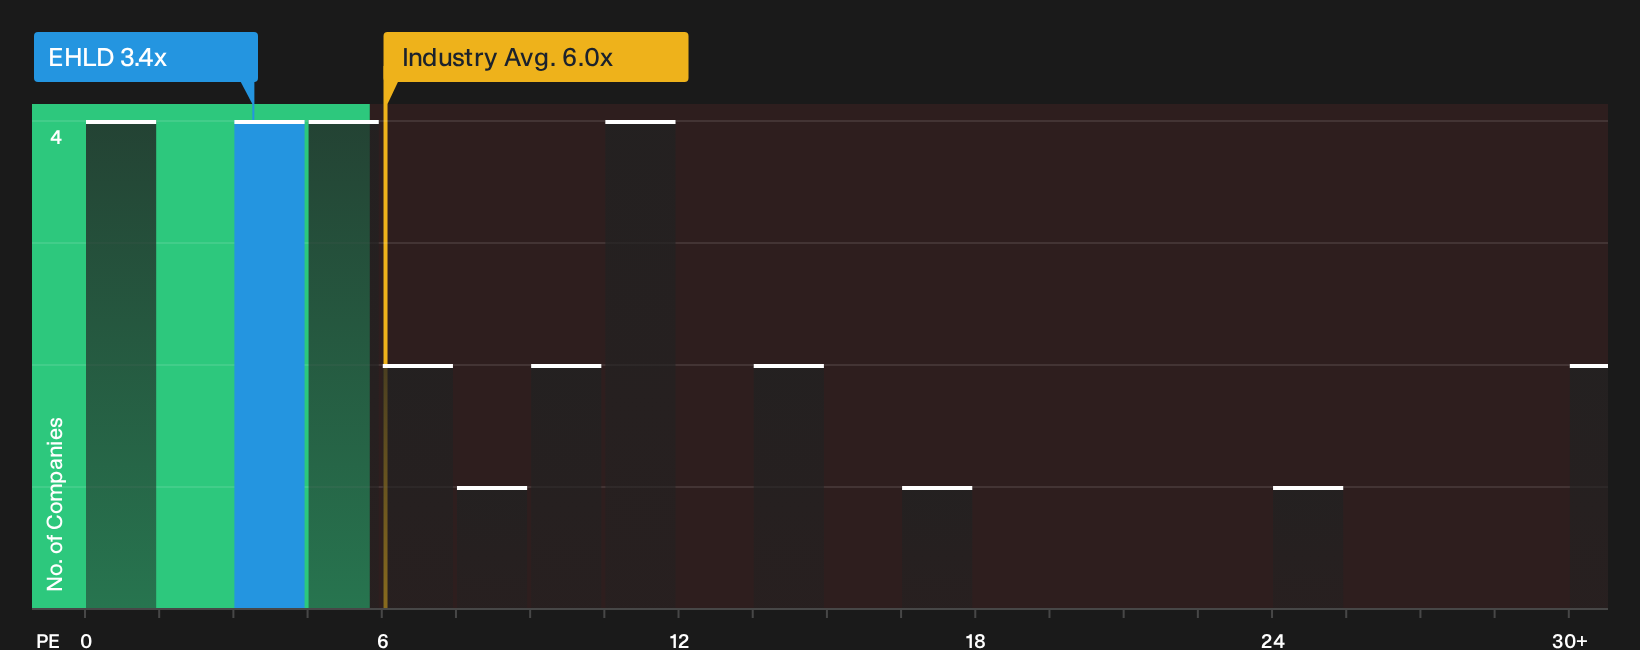
Euroholdings links directly to the listed crude tanker theme through its product tanker and container ships. This gives investors exposure to freight driven earnings with a P/E of 3.4x, high 40.2% net margins and a near 5% yield. However, dividend coverage and funding quality mean tanker rate swings could matter more than one unseen pressure on those headline profits.
Those headline profits could be masking fragile coverage, so pressure test Euroholdings with the 1 key reward and 4 important warning signs (1 is major!)
Toro (TORO)
Overview: Toro Corp acquires, owns, charters and operates a small fleet of MR crude and product tankers worldwide, providing direct tanker freight exposure.
Operations: Toro generates about $8 million from its Eco Tanker segment and $9 million from LPG carriers, with roughly $24 million booked in Cyprus.
Market Cap: $123.5 million
Toro Corp offers pure-play MR tanker exposure at a time when freight benchmarks are under scrutiny. Revenue is closely linked to real-world charter activity rather than a single disputed index. Investors get a focused tanker operator that has been adding vessels and liquidity, with earnings and cash flow sensitivity hinging on how charter pricing evolves if one unresolved pricing pressure shifts.
If you want to see how that plays through Toro’s numbers, scan the analysis report for Toro to identify where charter rates may be masking or amplifying risk.

Performance Shipping (PSHG)
Overview: Performance Shipping operates Aframax and Suezmax crude tankers worldwide, giving shareholders direct exposure to tanker freight rate cycles.
Operations: The business has generated about $113 million from container vessels, indicating meaningful scale tied to seaborne transport demand.
Market Cap: $25.9 million
Performance Shipping offers pure tanker exposure through Aframax and Suezmax vessels at a time when benchmark reliability is being questioned and physical freight still sets the real cash flows. Investors watching crude-linked shipping may focus on how changes in underlying market pressures could influence the way those cash flows are valued.
To see how that freight cash flow story might be priced into the balance sheet, read the analysis report for Performance Shipping for the next layer of insight.

Seeking Alternatives Before The Crowd?
Fresh opportunities can move quickly while attention stays locked on crude tankers. Some ideas gain momentum quietly, then are already moving once everyone catches on. Do the work now to position yourself early.
- Spot potential breakouts among smaller, liquid companies before momentum headlines catch up by reviewing the curated 11 elite penny stocks with strong financials list designed for punchy risk and disciplined fundamentals.
- Look for AI themes that could shift from under the radar to widely followed by scanning the refined 42 profitable AI stocks that aren't just burning cash that screens for real earnings, not hype.
- Consider exposure to potential income anchors while yield windows still matter by checking the hand picked 6 dividend fortresses built around durability and meaningful payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com