


EN
Wolfspeed (WOLF) Stock May Be Undervalued As New Silicon Carbide Launch Lands
Wolfspeed has delivered a 46.1% share price gain over the past year, which puts fresh attention on whether that move lines up with what its earnings currently support. With the stock around US$26.12, the question is how much of the recent excitement around silicon carbide technology is already embedded in the valuation.
- The 46.1% 1 year return raises the bar for Wolfspeed, because a stronger share price can leave less room for error if its earnings do not keep pace.
- The launch of transparent silicon carbide products and a multiyear supply deal for electric vehicle inverters can shape expectations for future profitability and the timing of Wolfspeed's earnings power.
- The analysts covering Wolfspeed have run their own numbers. See what analysts think Wolfspeed's shares could be worth.
The issue now is whether Wolfspeed's current share price is adequately supported by its earnings when judged against the Fair Ratio benchmark.
If this Wolfspeed move has you questioning what a fair earnings based valuation looks like elsewhere in semiconductors, it can help to compare against 53 AI infrastructure stocks.
Is Wolfspeed a Bargain on Earnings?
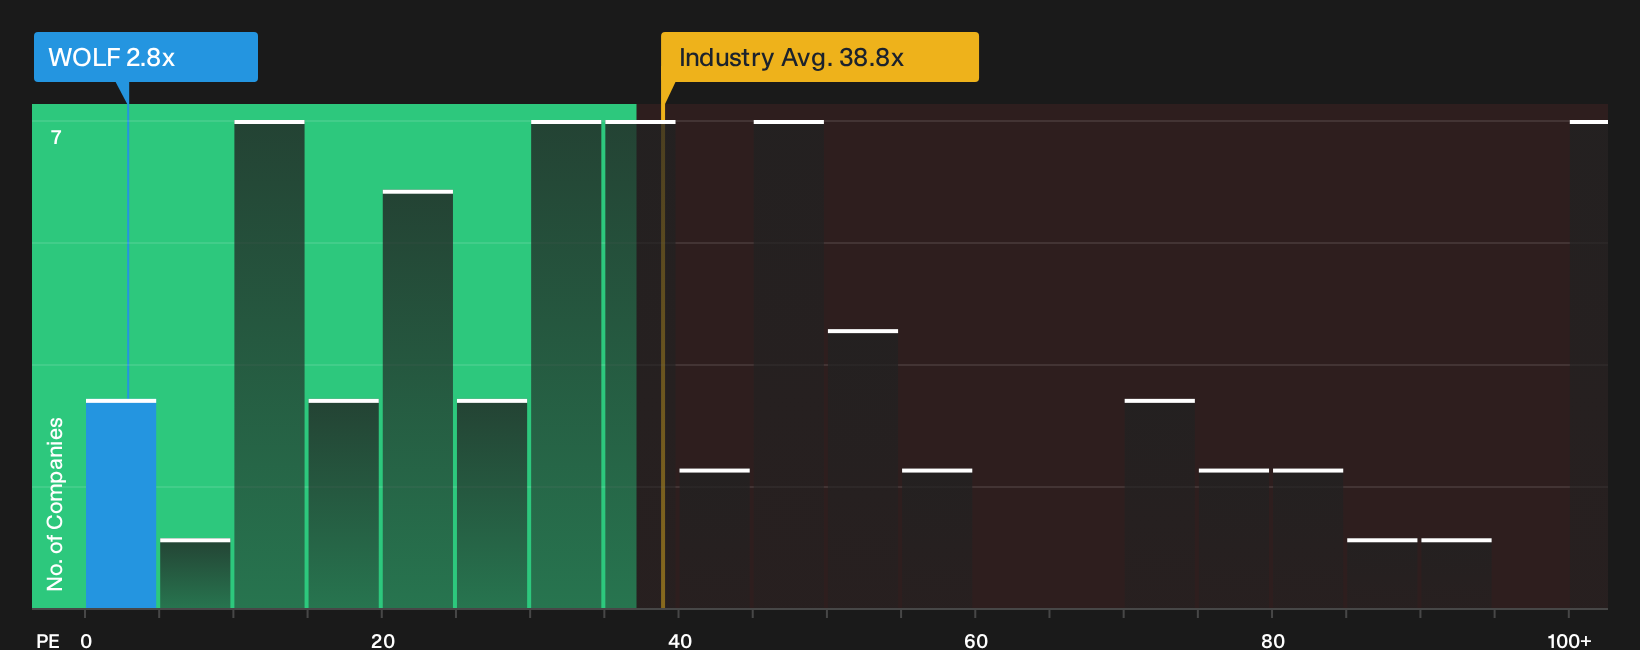
The P/E ratio lines up cleanly with how most investors think about Wolfspeed, because it links today’s share price directly to its current earnings base. On this measure, Wolfspeed trades on a P/E of about 2.8x, while the broader semiconductor industry sits near 38.8x and the peer group average is about 44.5x, so the stock changes hands at a steep discount to many chip makers that investors track.
Because the Fair Ratio benchmark blends in Wolfspeed’s own growth profile, profitability record, sector, scale and risk, it points to a higher P/E than the market currently applies. This suggests the shares screen as undervalued on this framework. Despite the recent excitement around transparent silicon carbide and the long term BorgWarner supply agreement, the low multiple implies the market is still cautious on how quickly those contracts and products might translate into durable earnings. Explore the numbers behind Wolfspeed's P/E valuation.
The Wolfspeed Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Wolfspeed valuation puzzle leaves off and spell out which paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than it is today on the market. Rather than pointing to a single P/E or model output, each scenario lays out its own fair value assumptions so you can keep checking those against Wolfspeed's actual results as they arrive.
One of the top narratives on Wolfspeed: roughly fairly valued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Wolfspeed is investing heavily in Gen 5 MOSFETs, 10 kilovolt MOSFETs and 200 millimeter silicon carbide capacity that are still in the early stages of commercial ramp…"
Discover why this Narrative puts Wolfspeed at roughly fairly valued.
One more Wolfspeed angle that might matter even more
Before moving on from Wolfspeed, it is worth asking who is steering the business, how they are rewarded for outcomes, and whether those incentives truly line up with the shareholders footing the bill. See who runs Wolfspeed and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com