


EN
Pennant Group (PNTG) Stock Could Be Overvalued After A 195% Run
Pennant Group has delivered a powerful share price run over the past few years, and that kind of move naturally puts the spotlight on what investors are paying for its earnings today. With fresh integration news and recent swings in the chart, the question now is how well the current price lines up with the profits the business is generating.
- The stock has climbed 195.0% over the past 3 years, which raises the stakes on whether the earnings profile is strong enough to back up that kind of move.
- Management has largely finished integrating hospice and home health assets from Amedisys and Optum, which can influence how investors think about future margins, capital needs and ultimately the earnings base that supports Pennant Group's valuation.
- Your read on Pennant Group is one view; the desks covering it have another. See what analysts think Pennant Group's shares could be worth.
The issue now is whether the earnings that Pennant Group produces today are enough to justify the current share price on this earnings focused lens.
If you want to test the same earnings focused question behind Pennant Group against a wider field, compare it with 33 high quality undervalued stocks.
Does Pennant Group Look Pricey on Earnings?
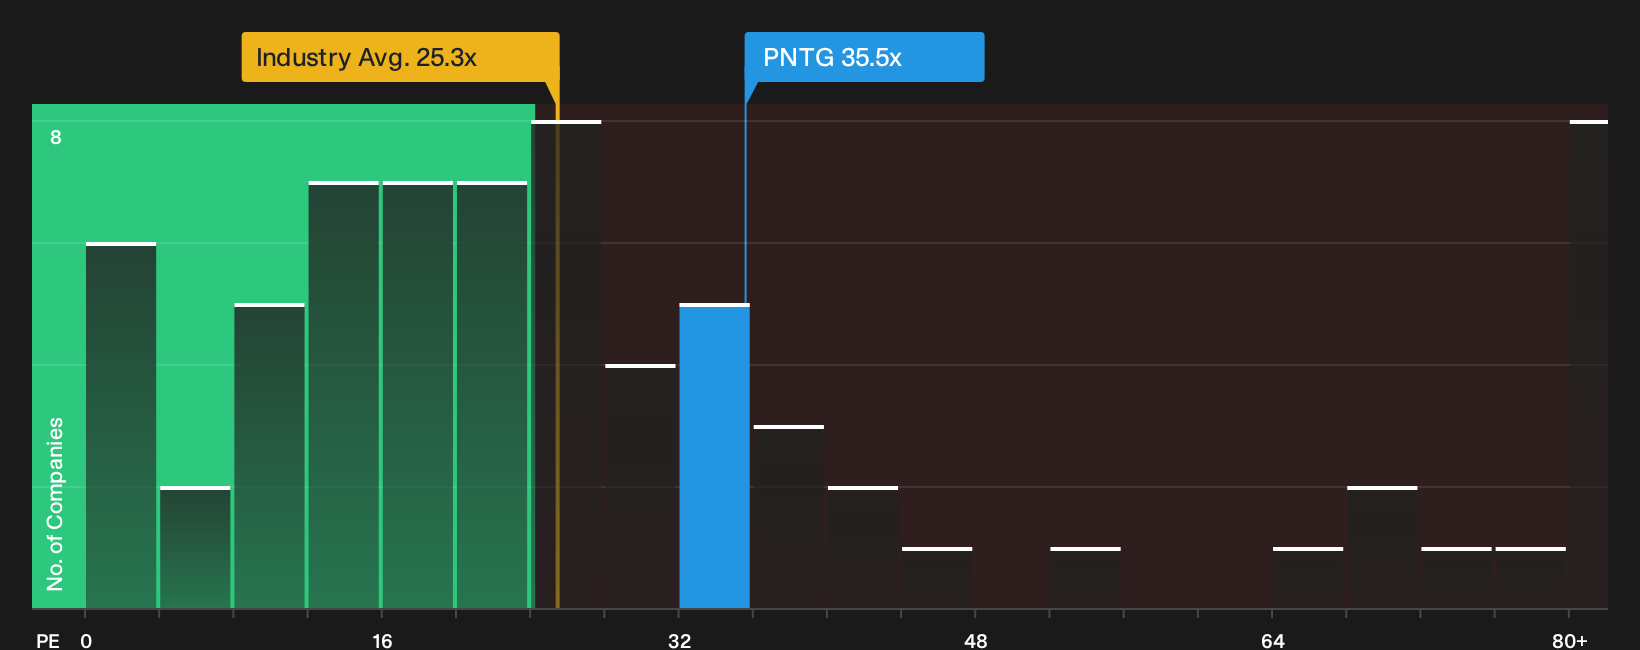
The P/E ratio is a simple way to check what you are paying for each dollar of Pennant Group earnings today. On this lens, the stock trades on about 35.5x, which is higher than the broader Healthcare sector average of roughly 25.3x and sits well below the peer group reference of about 64.8x.
Because management has just finished folding in the Amedisys and Optum assets, that premium to the sector suggests investors are already paying up for the current earnings stream and the integration story. The valuation model that blends the company’s growth profile, margins, size and risk points to a lower P/E being more in line with those fundamentals. On this framework, the present 35.5x reading screens as overvalued. Despite the latest revenue beat and integration update lifting sentiment, the current P/E still prices Pennant Group on the rich side of what this model would flag as a more grounded level. Explore the numbers behind Pennant Group's P/E valuation.
The Pennant Group Narrative: What Would Justify Today's Price?
Narratives for Pennant Group pick up where the valuation puzzle leaves off by spelling out what would need to happen to growth, margins and earnings for the stock to be worth materially more or less than today’s price on Simply Wall St's Community page. Each scenario ties a specific fair value to a clear set of potential catalysts and risks, which gives you a reference point to see which version of Pennant Group's story is actually showing up in the numbers over time.
One of the top narratives on Pennant Group: 18% undervalued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"The main thing that has to go right is for Pennant Group to keep translating its acquisitional growth and locally led operating model into higher same-store margins..."
Discover why this Narrative puts Pennant Group at 18% undervalued.
Pennant Group's price is only one piece of the investment puzzle
Valuation helps you frame what Pennant Group costs today, but the research also flags specific business risks that could matter just as much to your decision. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com